

|
시장보고서
상품코드
2124677
미국의 인쇄 라벨 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Print Label - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
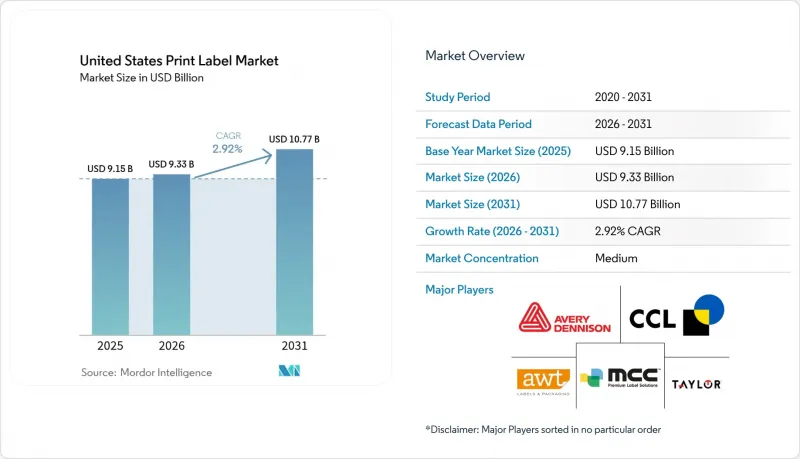
에 의하면, 미국의 인쇄 라벨 시장 규모는 2025년 91억 5,000만 달러로 평가되었고, 2026년 93억 3,000만 달러에서 2031년까지 107억 7,000만 달러로 확대될 것으로 예측되며, 2026-2031년 기간 CAGR은 2.92%를 나타낼 전망입니다.
본 보고서는 기판별(종이 및 판지, PET, PVC, 바이오 및 퇴비화 가능한 필름 등), 인쇄 기술별(오프셋, 플렉소, 스크린, 디지털 인쇄 등), 라벨 유형별(습식 접착, 감압 접착, 라이너리스, 인몰드, 수축 슬리브 등), 최종 사용자 산업별(식품, 음료, 산업용 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국의 인쇄 라벨 시장 동향 및 인사이트
디지털 인쇄 기술의 보급 현황
디지털 인쇄는 수량 기준으로는 시장 전체의 10분의 1 미만에 불과하지만, 이미 미국 인쇄 라벨 시장 가치의 약 5분의 1을 차지하고 있습니다. 각 컨버터의 보고에 따르면, 디지털 인쇄 수주의 대부분은 5,000장 미만이며 48시간 이내에 출하됩니다. 이는 판이 필요한 플렉소 인쇄로는 달성할 수 없는 지표이기 때문에 브랜드 소유자는 SKU의 급속한 확대나 제조 공정의 최종 단계에서 맞춤화를 실현하기 위해 높은 가격을 지불하고 있습니다. 플렉소 인쇄를 통한 흰색 및 스팟 컬러와 디지털 오버프린트를 결합한 하이브리드 인쇄기를 통해 컨버터는 기존 협폭 웹 설비의 감가상각을 진행하면서, 높은 수익률을 자랑하는 단기 납기 로트를 확보할 수 있습니다. 인라인 마감(다이컷, 라미네이팅, 호일 스탬핑)을 통해 2차 공정이 불필요해지고, 세팅 시 발생하는 폐기물이 대폭 감소하여 지속가능성 평가 지표 향상에도 기여합니다. 각 장비 공급업체들은 더 넓은 웹 폭을 지원하는 디지털 인쇄기를 출시하고 있으며, 이로 인해 제곱미터당 비용이 낮아지고, 중기적으로는 미국 인쇄 라벨 시장에서 디지털 인쇄의 점유율이 확대될 것으로 예측됩니다.
헬스케어 및 화장품 라벨 분야의 디지털 인쇄 보급
'의약품 공급망 보안법'에 따른 일련번호 부여 기한으로 인해, 제약 공장은 2024년 11월까지 판매 가능한 모든 단위에 전미 의약품 코드(NDC), 로트 번호, 유효 기간 데이터를 인코딩해야 할 의무가 있습니다. 이로 인해 대량의 가변 정보를 기재할 수 있는 점착 라벨이나 소책자형 라벨에 지속적인 호재가 이어지고 있습니다. 이와 병행하여, FDA가 클래스 II 및 III 의료기기에 대해 ‘의료기기 고유 식별자(UDI)’ 시행을 강화함에 따라, 오토클레이브나 감마선 멸균 환경을 견딜 수 있는 내구성 있는 라벨에 대한 수요가 확대되었습니다. 화장품 브랜드는 ‘화장품 규제 현대화법’ 및 캘리포니아주의 ‘알 권리법’에 따른 새로운 성분 표시 규정에 직면하여 SKU 재검토 및 소량 생산이 촉발되었습니다. 또한, 생물학적 치료제 파이프라인에서는 극저온용 접착제 및 부정 개봉 방지 씰이 요구되고 있어, 이 채널에서 판매되는 각 라벨의 부가가치를 높이고 있습니다. 이러한 요인들이 결합되어 미국 내 인쇄 라벨 시장에서 최종 사용자 대상 연평균 성장률(CAGR)이 가장 높은 분야를 뒷받침하고 있습니다.
종이 및 수지 원자재 비용 변동
표백 크라프트 펄프 가격은 2024년 중반에 정점을 찍었으며, 2025년 초에도 2023년 평균 가격보다 18% 높은 수준을 유지했습니다. 반면, 아크릴 수지 및 핫멜트 수지 지수는 가격 급등 이전 수준보다 12% 높은 수준을 유지하고 있어, 고정 가격 계약을 맺은 컨버터의 이익률을 압박하고 있습니다. 헤지 프로그램이 없는 중소규모 컨버터들은 특수 필름의 리드타임이 3배로 늘어나고, 사용 후 PET 재활용 소재가 1미터톤당 200-400달러의 프리미엄 가격으로 거래되는 상황에서 운전 자금 변동에 시달리고 있습니다. 재고 완충분이 자금을 묶어두고, 설비 투자를 제한하며, 지속 가능한 소재로의 전환을 지연시키고 있기 때문에 미국 인쇄 라벨 시장의 예상 연평균 성장률(CAGR)은 0.3포인트 하향 조정되었습니다.
부문별 분석
폴리에틸렌 테레프탈레이트(PET)는 2025년에 37.83%의 시장 점유율을 유지했으며, 투명성과 재활용성을 중시하는 음료, 퍼스널케어, 의약품 용도에서 주력 기판으로 자리 잡고 있습니다. 이러한 우위 덕분에 PET는 금액 및 수량 양면에서 미국 인쇄 라벨 시장 규모에서 가장 큰 점유율을 계속 차지하고 있습니다. 그러나 EPR(생산자 책임 확장) 요금 체계와 소매업체의 평가 기준에 따라, ASTM D6400 퇴비화 기준을 충족하는 폴리젖산(PLA) 및 셀룰로오스계 필름의 점진적인 성장이 촉진되고 있습니다. 바이오 제품은 2031년까지 연평균 3.57%의 성장률을 기록하며, 기존의 모든 폴리머를 능가하는 속도로 성장할 것으로 전망됩니다. 이러한 제품들이 표준 PET보다 40%-60% 높은 프리미엄 가격을 제시하고 있기 때문에 각 컨버터 기업들은 주류 생산 라인을 희생하지 않으면서도 전용 생산 셀을 구축하도록 유도받고 있습니다. 중기적으로는 지자체의 퇴비화 인프라 확충이 미국 인쇄 라벨 시장에서 이러한 신소재가 시험적 주문 단계에서 표준 사양으로 전환되는 속도를 결정짓게 될 것입니다.
재활용 가능한 라벨 기술에 대한 투자가 활발해지고 있습니다. 클린 플레이크형 접착 시스템 덕분에 알칼리 세척 중에 점착 라벨이 떠오르게 되어, 병-병 루프(bottle-to-bottle loop)에서 버진 PET와 동등한 수지 품질을 실현했습니다. 이러한 혁신은 PET의 주도적 지위를 강화할 뿐만 아니라, 가정 쓰레기에서 회수율이 낮은 폴리프로필렌에 대한 시장 점유율을 지키는 데에도 기여합니다. 앞으로 연방 정부의 재생재 함유율 의무화가 시행되면, 버진 원료의 가격이 재설정되고, 각 브랜드사의 소비 후 재생 PET 및 바이오 대체 소재로의 전환이 가속화되어, 미국 인쇄 라벨 시장에서 소재의 우선순위가 재편될 가능성이 있습니다.
2025년에는 플렉소 인쇄가 시장 점유율의 45.63%를 차지했습니다. 이는 각 컨버터 업체들이 좁은 폭 인쇄기, 애닐록스 롤러 재고, 인라인 마감 설비에 수십 년에 걸쳐 투자를 지속해 왔기 때문입니다. 이러한 매몰 비용 덕분에 1만 장을 초과하는 주문에서 1,000장당 라벨 단가를 낮게 유지할 수 있어, 미국 인쇄 라벨 시장 점유율을 지배하는 대량 생산 식품 및 음료 프로그램에서 플렉소 인쇄의 입지가 확고해졌습니다. 그러나 디지털 인쇄의 예상 연평균 성장률(CAGR)이 3.21%라는 점은 소량 생산 및 가변 데이터에 대한 수요가 뚜렷하게 증가하고 있음을 보여줍니다. 현재 하이브리드 인쇄기는 단색 배경이나 흰색 밑바탕 인쇄에는 플렉소 인쇄를, 버전 관리에는 디지털 헤드를 결합함으로써 이 두 기술의 경계를 사실상 모호하게 만들고 있습니다.
잉크젯 제조업체들이 더 넓은 웹 모델을 출시하고 최대 직선 속도를 향상시킴에 따라, 플렉소와 디지털의 경제적 손익분기점은 점차 상승하고 있습니다. 동시에 LED 경화형 잉크의 도입으로 신형 플렉소 인쇄기의 에너지 효율이 향상되어 총비용 차이가 좁혀지고 있습니다. 현재 워크플로우 자동화 및 색상 관리 소프트웨어에 투자하는 컨버터는 두 기술 분야 모두에서 이익을 확보할 수 있을 것입니다. 그러나 대응이 늦어지는 기업은 미국 인쇄 라벨 시장이 진화함에 따라 디지털 기반의 신규 진출기업들에게 고부가가치 작업을 빼앗길 위험이 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the United States print label market size is projected to expand from USD 9.15 billion in 2025 and USD 9.33 billion in 2026 to USD 10.77 billion by 2031, registering a CAGR of 2.92% between 2026 to 2031.
This report is Segmented by Substrate Material (Paper and Paperboard, PET, PVC, Biobased and Compostable Films, and More), Print Technology (Offset, Flexography, Screen, Digital Printing, and More), Label Type (Wet-Glued, Pressure-Sensitive, Liner-Less, In-Mold, Shrink Sleeve, and More), End-User Industry (Food, Beverage, Industrial, and More). Market Forecasts are Provided in Terms of Value (USD).
United States Print Label Market Trends and Insights
Digital Print Technology Penetration
Digital printing already accounts for roughly one-fifth of United States print label market value even though it represents less than one-tenth of unit volume. Converters report that most digital orders run below 5,000 pieces and ship within 48 hours, metrics unattainable for plate-based flexography, so brand owners pay a premium for rapid SKU proliferation and late-stage customization. Hybrid presses that combine flexographic white or spot colors with digital overprints allow converters to amortize their existing narrow-web infrastructure while capturing high-margin short runs. Inline finishing die-cutting, lamination, and foil stamping eliminates secondary steps, slashing makeready waste and supporting sustainability scorecards. Equipment vendors are responding with wider-web digital units, which should lower the cost per square meter and lift digital's share of the United States print label market over the medium term.
Healthcare and Cosmetics Label Uptake
Serialization deadlines under the Drug Supply Chain Security Act forced pharmaceutical plants to encode National Drug Code, lot, and expiration data on every saleable unit by November 2024, providing a durable tailwind for pressure-sensitive and booklet labels that can carry significant variable information. Parallel FDA enforcement of Unique Device Identification for Class II and III medical devices expanded demand for durable labels resistant to autoclave and gamma-sterilization environments. Cosmetics brands faced new ingredient-disclosure rules under the Modernization of Cosmetics Regulation Act and California's Right to Know statute, triggering SKU revisions and smaller-batch production. The biological therapeutics pipeline also calls for cryogenic adhesives and tamper-evident seals, lifting the value density of each label sold into this channel. Collectively these factors support the fastest end-user CAGR inside the United States print label market.
Volatile Paper and Resin Input Costs
Bleached-kraft pulp prices peaked in mid-2024 and were still 18% above 2023 averages in early 2025, while acrylic and hot-melt resin indices held 12% higher than pre-spike levels, compressing converter margins on fixed-price contracts. Smaller converters without hedging programs endure working-capital swings when specialty film lead times triple and post-consumer recycled PET trades at premiums of USD 200-400 per metric ton. Inventory buffers tie up cash, limit capital upgrades, and slow the shift to sustainable materials, shaving 0.3 percentage points off the forecast CAGR for the United States print label market.
Other drivers and restraints analyzed in the detailed report include:
- E-commerce and Logistics Label Volumes
- EPR-Driven Shift to Linerless and Recyclable Labels
- Skilled Narrow-Web Labor Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene terephthalate sustained a 37.83% market share in 2025, making it the anchor substrate for beverage, personal-care, and pharmaceutical applications that value clarity and recyclability. That prominence keeps PET as the single largest slice of the United States print label market size at both dollar and volume levels. Yet EPR fee structures and retailer scorecards are steering incremental growth toward polylactic-acid and cellulose-based films that meet ASTM D6400 compostability criteria. Biobased offerings are set to grow 3.57% per year to 2031, outpacing every legacy polymer. The premium they command, often 40%-60% higher than standard PET, encourages converters to carve out specialized production cells rather than cannibalize mainstream lines. Over the medium term, broader municipal composting infrastructure will determine how fast these new materials convert trial orders into baseline specifications in the United States print label market.
Investments in recyclable label technologies are picking up. Clean-flake adhesive systems now allow pressure-sensitive labels to float off during caustic washing, unlocking equivalent resin quality to virgin PET for bottle-to-bottle loops. Such innovations not only reinforce PET leadership but also protect its share against polypropylene, which suffers from lower curbside recovery rates. Looking ahead, federal recycled-content mandates, if enacted, could reprice virgin inputs and accelerate brand migration toward both post-consumer recycled PET and bio-based substitutes, reshaping the material hierarchy inside the United States print label market.
Flexography generated 45.63% of market share in 2025 because converters retain decades of investment in narrow-web presses, anilox inventories, and inline finishing assets. These sunk costs keep cost-per-thousand labels low on jobs beyond 10,000 units, anchoring flexo's role in high-volume food and beverage programs that dominate the United States print label market share figure. However, digital printing's 3.21% forecast CAGR demonstrates a clear pivot toward short runs and variable data requirements. Hybrid presses now marry flexo for solid backgrounds and white underprints with digital heads for versioning, effectively blurring the boundary between the two technologies.
The economic breakeven between flexo and digital continues to creep upward as inkjet manufacturers release wider-web models and raise maximum linear speed. Concurrently, LED-curable inks improve energy efficiency on newer flexo units, narrowing the total-cost gap. Converters that invest today in workflow automation and color-management software will capture margin from both halves of the technology split, but laggards risk ceding premium work to digitally native entrants as the United States print label market evolves.
Complete Report Scope:
- By Substrate Material
- Paper and Paperboard
- Polyethylene Terephthalate (PET)
- Polypropylene (PP and BOPP)
- Polyvinyl Chloride (PVC)
- Biobased and Compostable Films
- Other Substrate Materials
- By Print Technology
- Offset
- Flexography
- Screen
- Digital Printing
- Other Print Technologies
- By Label Type
- Wet-glued Labels
- Pressure-Sensitive Labels
- Liner-less Labels
- In-mold Labels
- Shrink Sleeve Labels
- Other Label Types
- By End-user Industry
- Food
- Beverage
- Healthcare and Pharmaceutical
- Cosmetics and Personal Care
- Industrial
- Other End-user Industries
List of Companies Covered in this Report:
- Avery Dennison Corporation
- Multi-Color Corporation
- Fort Dearborn Company LLC
- AWT Labels and Packaging
- Brady Corporation
- RR Donnelley and Sons Company
- Taylor Corporation
- Weber Packaging Solutions
- Grand Rapids Label
- DRG Technologies Inc.
- CCL Industries Inc.
- Constantia Flexibles Group GmbH
- Label Masters LLC
- 3M Company
- Resource Label Group LLC
- Fortis Solutions Group LLC
- Brook and Whittle Holdings Corp.
- Inland Label and Marketing Services LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Digital Print Technology Penetration
- 4.2.2 Healthcare and Cosmetics Label Uptake
- 4.2.3 E-commerce and Logistics Label Volumes
- 4.2.4 EPR-Driven Shift to Linerless and Recyclable Labels
- 4.2.5 Smart and IoT Labels for Supply-Chain Traceability
- 4.2.6 Near-Shoring Driving Short-Run Variable-Data Print
- 4.3 Market Restraints
- 4.3.1 Durability Limits in Harsh Conditions
- 4.3.2 Volatile Paper and Resin Input Costs
- 4.3.3 Skilled Narrow-Web Labor Shortages
- 4.3.4 Recycling-Stream Fragmentation
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Substrate Material
- 5.1.1 Paper and Paperboard
- 5.1.2 Polyethylene Terephthalate (PET)
- 5.1.3 Polypropylene (PP and BOPP)
- 5.1.4 Polyvinyl Chloride (PVC)
- 5.1.5 Biobased and Compostable Films
- 5.1.6 Other Substrate Materials
- 5.2 By Print Technology
- 5.2.1 Offset
- 5.2.2 Flexography
- 5.2.3 Screen
- 5.2.4 Digital Printing
- 5.2.5 Other Print Technologies
- 5.3 By Label Type
- 5.3.1 Wet-glued Labels
- 5.3.2 Pressure-Sensitive Labels
- 5.3.3 Liner-less Labels
- 5.3.4 In-mold Labels
- 5.3.5 Shrink Sleeve Labels
- 5.3.6 Other Label Types
- 5.4 By End-user Industry
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Healthcare and Pharmaceutical
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Industrial
- 5.4.6 Other End-user Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Avery Dennison Corporation
- 6.4.2 Multi-Color Corporation
- 6.4.3 Fort Dearborn Company LLC
- 6.4.4 AWT Labels and Packaging
- 6.4.5 Brady Corporation
- 6.4.6 RR Donnelley and Sons Company
- 6.4.7 Taylor Corporation
- 6.4.8 Weber Packaging Solutions
- 6.4.9 Grand Rapids Label
- 6.4.10 DRG Technologies Inc.
- 6.4.11 CCL Industries Inc.
- 6.4.12 Constantia Flexibles Group GmbH
- 6.4.13 Label Masters LLC
- 6.4.14 3M Company
- 6.4.15 Resource Label Group LLC
- 6.4.16 Fortis Solutions Group LLC
- 6.4.17 Brook and Whittle Holdings Corp.
- 6.4.18 Inland Label and Marketing Services LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


