

|
시장보고서
상품코드
2124782
영국의 골판지 포장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United Kingdom Corrugated Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
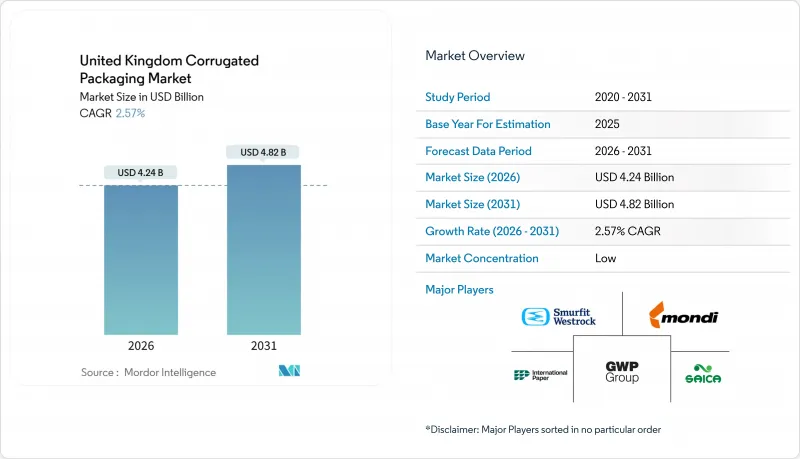
에 의하면, 영국의 골판지 포장 시장 규모는 2026년에 42억 4,000만 달러에 달하고, 2031년까지 48억 2,000만 달러에 이를 것으로 예상되며, 예측 기간 중 연평균 복합 성장률(CAGR)은 2.57%를 나타낼 전망입니다.
본 보고서는 제품 유형(슬롯 박스, 텔레스코픽·멀티피스 박스, 트레이, 기타), 보드 유형(단벽, 이중벽, 삼중벽), 플루트 프로파일(A, B, C, E, F, 기타), 최종 사용자 산업(식품, 음료, 의약품, 기타),인쇄 기술(플렉소 인쇄, 디지털 인쇄, 리소그래피, 기타)별로 세분화되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
영국의 골판지 포장 시장 동향 및 인사이트
전자상거래 소포 처리량의 급증
2024년에는 온라인 소매 시장 침투율이 영국 총 매출의 27.8%에 달하면서, 자동 분류 부하를 견디면서도 부피 중량 요금을 최소화할 수 있는 경량 B 플루트 및 F 플루트 메일러에 대한 수요를 촉진했습니다. 브랜드들의 ‘Ships in Own Container(전용 용기 발송)’ 프로그램 참여로 인해, 슬롯이 있는 스트레스 프리 상자의 잠재 고객층이 확대되면서 가변 데이터 및 QR 코드용 디지털 인쇄 도입이 점차 진행되고 있습니다.
재활용 가능한 섬유 기반 포장에 대한 선호
‘2024년 폐기물 분리수거 규정’에 따라 2025년 3월까지 대부분의 기업에 대해 종이 및 골판지의 분리수거가 의무화되었으며, 이로 인해 베일의 순도가 향상되고 재생 섬유 가격이 약 8-12% 상승했습니다. 확대 생산자 책임(EPR) 수수료로 인해 단일 소재 설계가 유리해지는 비용 격차가 발생했으며, 각 브랜드는 플라스틱 트레이를 골판지 대체품으로 교체하도록 권장받고 있습니다.
폐지 가격 및 공급 변동
2023년 가정용 종이 회수량은 전년 대비 3.3% 감소한 189만 4,000톤을 기록했으며, 재활용률이 74.3%에 달했음에도 불구하고 원료 공급량이 압박을 받았습니다. 2025년 초에는 포장·회수·노트(PRN) 가격이 톤당 5파운드 아래로 떨어지면서, 지방 자치 단체의 폐지(OCC) 분리 수거에 대한 인센티브가 약화되었고, 가공업체들은 펄프 조달 위험을 헤지할 수밖에 없게 되었습니다.
부문별 분석
2025년에는 슬롯이 있는 상자가 시장 점유율의 42.43%를 차지했습니다. 이는 고속 조립 라인과의 호환성은 물론, 식품, 음료, 산업용 운송 등 폭넓은 분야에서 사용된 점이 반영된 결과입니다. 영국의 트레이, 폴더, 시트와 관련된 골판지 포장 시장 규모는 매장 내 인건비를 절감하고 진열대에서의 가시성을 높이는 ‘진열 준비 완료(shelf-ready)’ 진열에 대한 소매업체 수요에 힘입어 연평균 성장률(CAGR) 3.66%로 확대될 것으로 전망됩니다. 테스코와 세인즈베리가 정한, 미싱 선이 있는 찢어내기 스트립 및 보강된 코너 포스트에 관한 사양은 소재의 등급 향상을 촉진하고 있으며, 아마존의 ‘자사 컨테이너로 배송’ 기준에 따라 1차 포장이 배송용 케이스 역할을 겸하게 되었습니다. 또한, 혼잡한 전자상거래 스토어프론트에서 제품을 차별화하기 위해 오프셋 인쇄와 라미네이팅 처리가 적용된 그래픽을 채택한 선물용 및 판촉용 포장 형태에서도 수요가 발생하고 있습니다.
1인 가구를 위한 소용량 포장을 요구하는 브랜드 소유주들에 의해 수천 개의 SKU가 탄생하고 있으며, 트레이와 폴더는 납기 기간이 짧은 디지털 인쇄에 최적입니다. 영국의 골판지 포장 시장에서 텔레스코픽 박스와 멀티피스 박스의 점유율은 여전히 미미하지만, 중장비 수출업체들은 1회 출하당 5만 파운드(6만 3,500달러) 이상의 가치가 있는 민감한 장비의 운송에 이러한 깊이 조절형 설계를 의존하고 있습니다. 예측 기간 동안 출판사들은 마이크로 플루트 소재의 우편 발송용 상자가 보급될 것으로 전망하고 있지만, 자동 케이스 조립기가 분당 60개 이상의 케이스를 처리하는 상황에서는 슬롯이 있는 상자가 여전히 큰 점유율을 유지하고 있습니다.
2025년, 싱글월 골판지는 무게, 비용, 적재 성능의 균형이 잘 잡혀 있어 영국의 골판지 포장 시장 점유율의 38.32%를 차지했습니다. 대조적으로, 자동차, 항공우주, 기계 분야의 화주들이 목재 크레이트에서 전환함에 따라, 3중 골판지는 연평균 성장률(CAGR) 4.32%로 시장 점유율을 확대되고 있습니다. CorrBoard와 VPK Packaging의 신규 생산 능력 확대로 인해, 미터당 10kN을 초과하는 모서리 충격 저항 기준을 충족하는 BB 및 BC 이중벽 골판지에 대한 접근성이 확대되고 있습니다. 더블월 제품군은 가전제품 분야에서 여전히 중요하지만, 경량화가 진행됨에 따라 많은 용도에서 고성능 라이너를 갖춘 최적화된 싱글월 등급으로의 전환이 진행되고 있습니다.
산업 부문의 화주들은 해상 운송 중 진동, 습기, 관통의 위험에 노출될 가능성이 있는 수출 화물의 경우 트리플 월을 선호하여 사용하고 있습니다. 영국의 골판지 포장 시장에서 트리플 월의 취급량은 여전히 싱글 월보다 적지만, 단위당 수익이 높고 이익률도 안정적이기 때문에 변환 업체들의 관심을 끌고 있습니다. CorrBoard의 자동 팔레타이징에 대한 투자는 내구성이 높은 골판지의 중기적 전망을 뒷받침하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the United Kingdom corrugated packaging market size stands at USD 4.24 billion in 2026 and is expected to reach USD 4.82 billion by 2031, reflecting a 2.57% CAGR over the forecast period.

This report is Segmented by Product Type (Slotted Box, Telescope/Multi-Piece Boxes, Trays, and More), Board Type (Single Wall, Double Wall, and Triple Wall), Flute Profile (A, B, C, E, F, and More), End-User Industry (Food, Beverages, Pharmaceuticals, and More) and Print Technology (Flexography, Digital, Lithography, and More). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Corrugated Packaging Market Trends and Insights
Surge in E-Commerce Parcel Volumes
Online retail penetration touched 27.8% of total U.K. sales in 2024, stimulating demand for lightweight B- and F-flute mailers that withstand automated sortation forces while minimizing dimensional-weight charges. Brand participation in "Ships in Own Container" programs expands the addressable pool for frustration-free slotted boxes, supporting incremental adoption of digital printing for variable data and QR codes.
Preference for Recyclable Fiber-Based Packaging
The Separation of Waste Regulations 2024 mandates dedicated paper and card collection for most businesses by March 2025, lifting bale purity and boosting recovered-fiber prices by roughly 8-12%. Extended Producer Responsibility fees establish a cost gradient that favors mono-material designs, encouraging brands to substitute plastic trays with corrugated equivalents.
Volatility in Recovered Paper Prices and Supply
Household paper collection fell 3.3% year on year to 1.894 million t in 2023, compressing raw-material availability even as recycling rates reached 74.3%. Packaging Recovery Note prices dropped below GBP 5 per tonne in early 2025, undermining the incentive for local authorities to segregate OCC and forcing converters to hedge pulp inputs.
Other drivers and restraints analyzed in the detailed report include:
- Lightweighting Initiatives
- Rising Demand from Processed Food Brands
- Substitution Threat from Flexible Plastics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Slotted boxes represented 42.43% of market share in 2025, reflecting their compatibility with high-speed erecting lines and broad use across food, beverage, and industrial shipping. The United Kingdom corrugated packaging market size attached to trays, folders and sheets is projected to expand at a 3.66% CAGR, fueled by retailer mandates for shelf-ready presentation that trims in-store labor and boosts on-shelf visibility. Tesco and Sainsbury's specifications for perforated tear strips and reinforced corner posts reinforce material upgrades, and Amazon's ship-in-own-container standard pushes primary packs to double as shipping cases. Additional demand stems from gift and promotional formats that employ litho-laminated graphics to differentiate products in crowded e-commerce storefronts.
Brand owners chasing smaller pack counts for single-person households generate thousands of SKUs, making trays and folders ideal for short-run digital printing. The United Kingdom corrugated packaging market share enjoyed by telescope and multi-piece boxes remains modest, yet heavy-machinery exporters rely on these adjustable depth designs for delicate equipment valued at more than GBP 50,000 (USD 63,500) per shipment. Over the forecast horizon, publishers forecast micro-flute mailers to proliferate, yet slotted boxes retain scale where automated case erectors handle more than 60 cases per minute.
Single-wall board captured 38.32% of the United Kingdom corrugated packaging market share in 2025, balancing weight, cost, and stacking performance. In contrast, triple-wall constructions are gaining at a 4.32% CAGR as automotive, aerospace, and machinery shippers shift away from timber crates. CorrBoard and VPK Packaging's new capacity expands access to BB and BC double-wall flutes that meet edge-crush thresholds above 10 kN per meter. Double-wall variants remain relevant for household appliances, but lightweighting is pushing many applications toward optimized single-wall grades with high-performance liners.
Industrial shippers prefer triple-wall for export cargo that can face vibration, humidity, and puncture hazards during ocean transit. The United Kingdom corrugated packaging market's triple-wall volume remains smaller than single-wall volumes, yet its higher unit revenue and stable margins drive converter interest. Investments in automated palletization at CorrBoard reinforce the medium-term outlook for heavy-duty board.
Complete Report Scope:
- By Product Type
- Slotted Box
- Telescope/Multi-Piece Boxes
- Trays, Folder and Sheets
- Other Product Types
- By Board Type
- Single Wall
- Double Wall
- Triple Wall
- By Flute Profile
- A Flute
- B Flute
- C Flute
- E Flute
- F Flute
- Other Flute Profile
- By End-user Industry
- Food
- Beverages
- Pharmaceuticals
- Personal Care and Household
- Industrial
- E-commerce
- Electrical and Electronics
- Other End-user Industries
- By Print Technology
- Flexography
- Digital
- Lithography
- Other Print Technology
List of Companies Covered in this Report:
- Mondi Group
- Smurfit WestRock
- International Paper Company
- Saica Group S.L.
- GWP Group Limited
- The Box Factory Limited
- Cepac Limited
- Board24 Limited
- Rigid Containers Limited
- Boxes and Packaging (Oxford) Limited
- Kentpak Limited
- Keenpac UK Limited
- Atlas Packaging Limited
- Reedbut Group Limited
- Preston Board & Packaging Ltd
- Schumacher Packaging Ltd
- Kite Packaging Ltd
- CorrBoard UK Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge In E-Commerce Parcel Volumes
- 4.2.2 Preference For Recyclable Fibre-Based Packaging Amid UK Regulations
- 4.2.3 Lightweighting Initiatives Lowering Logistics Emissions
- 4.2.4 Rising Demand From Processed Food And Beverage Brands
- 4.2.5 Expansion Of Shelf-Ready Corrugated Formats In Retail
- 4.2.6 Plastic Packaging Tax Redirecting Capital Toward Corrugated Lines
- 4.3 Market Restraints
- 4.3.1 Volatility In Recovered Paper (OCC) Prices And Supply
- 4.3.2 Substitution Threat From Flexible Plastics In Fragile Goods
- 4.3.3 Urban Curbside Collection Limits For Mixed Paper Streams
- 4.3.4 Energy-Price Fluctuations Squeezing Corrugator Margins
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Slotted Box
- 5.1.2 Telescope/Multi-Piece Boxes
- 5.1.3 Trays, Folder and Sheets
- 5.1.4 Other Product Types
- 5.2 By Board Type
- 5.2.1 Single Wall
- 5.2.2 Double Wall
- 5.2.3 Triple Wall
- 5.3 By Flute Profile
- 5.3.1 A Flute
- 5.3.2 B Flute
- 5.3.3 C Flute
- 5.3.4 E Flute
- 5.3.5 F Flute
- 5.3.6 Other Flute Profile
- 5.4 By End-user Industry
- 5.4.1 Food
- 5.4.2 Beverages
- 5.4.3 Pharmaceuticals
- 5.4.4 Personal Care and Household
- 5.4.5 Industrial
- 5.4.6 E-commerce
- 5.4.7 Electrical and Electronics
- 5.4.8 Other End-user Industries
- 5.5 By Print Technology
- 5.5.1 Flexography
- 5.5.2 Digital
- 5.5.3 Lithography
- 5.5.4 Other Print Technology
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Mondi Group
- 6.4.2 Smurfit WestRock
- 6.4.3 International Paper Company
- 6.4.4 Saica Group S.L.
- 6.4.5 GWP Group Limited
- 6.4.6 The Box Factory Limited
- 6.4.7 Cepac Limited
- 6.4.8 Board24 Limited
- 6.4.9 Rigid Containers Limited
- 6.4.10 Boxes and Packaging (Oxford) Limited
- 6.4.11 Kentpak Limited
- 6.4.12 Keenpac UK Limited
- 6.4.13 Atlas Packaging Limited
- 6.4.14 Reedbut Group Limited
- 6.4.15 Preston Board & Packaging Ltd
- 6.4.16 Schumacher Packaging Ltd
- 6.4.17 Kite Packaging Ltd
- 6.4.18 CorrBoard UK Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


