

|
시장보고서
상품코드
2125610
중동 및 아프리카의 골판지 포장 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Middle-East And Africa Corrugated Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
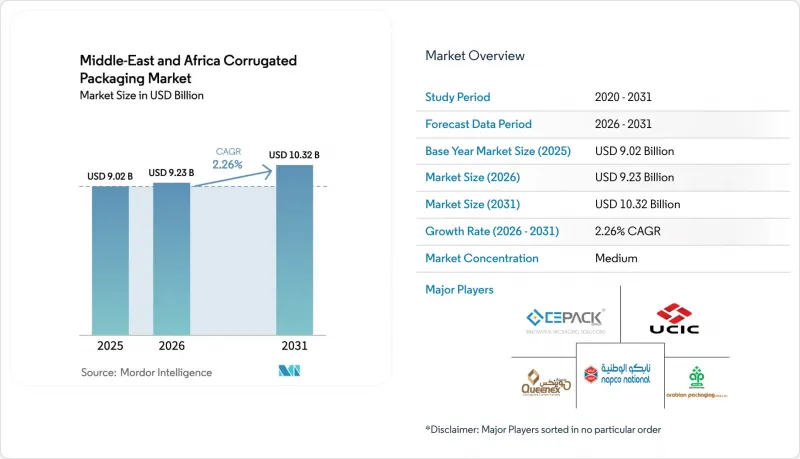
에 의하면, 중동 및 아프리카 골판지 포장 시장 규모는 2025년 90억 2,000만 달러, 2026년 92억 3,000만 달러에서 2031년까지 103억 2,000만 달러로 확대한다고 예측되고 있어 2026년부터 2031년까지 사이 CAGR은 2.26%를 나타낼 전망입니다.
본 보고서는 상자 유형(슬롯이 있는 컨테이너, 다이컷 컨테이너, 5패널 폴더 박스, 텔레스코픽 박스 등), 판지 등급(단층 판지, 이중층 판지 등), 플루트 크기(A 플루트, B 플루트 등), 최종 사용자 산업(식품, 음료 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
중동 및 아프리카 골판지 포장 시장 동향 및 인사이트
전자상거래의 급속한 성장이 라스트 마일 대응 포장을 견인
2024년, 이 지역의 온라인 소매 시장은 30% 성장하여 부피 중량 요금을 대폭 절감하고 역물류 처리에도 견딜 수 있는 다이컷 상자 수요를 끌어올렸습니다. 사우디아라비아에서 디지털 결제가 보급됨에 따라 2선 도시에서의 전자상거래 침투가 진행되고 있으며, 각 컨버터 기업들은 원자재 비용을 20-30% 절감하기 위해 F-플루트 및 마이크로플루트의 채택을 추진하고 있습니다. 아랍에미리트(UAE)에서는 크로스보더 전자상거래 마켓플레이스에서 위조 방지 기능과 다국어 지원 그래픽이 요구됨에 따라 가변 데이터 디지털 인쇄에 대한 관심이 높아지고 있습니다. drupa 2024에서 전시된 인라인 하이브리드 인쇄기는 500개 단위의 소량 생산이 가능하며, 마이크로 브랜드가 판 제작 리드타임 없이 그래픽을 개인화할 수 있게 되었습니다. 이러한 변화들이 맞물리면서, 각 컨버터 기업들은 수주 주기 단축, 플루트 폭 축소, 그리고 반품 창구 역할도 수행하는 인터랙티브 QR 코드에 대응할 수 있도록 설비 개편을 추진하고 있습니다.
FMCG 및 조직화된 소매업의 급속한 확장
사우디아라비아, 아랍에미리트, 이집트의 대형 마트 체인들은 여름 기온이 45℃를 넘는 지방 도시로 사업을 확장하고 있습니다. 골판지 포장 업체들은 사우디아라비아 식품의약청(SFDA)의 표시 기준을 준수하여 아랍어 표기를 기재하는 한편, 고습도 환경에서의 물류를 견딜 수 있는 제품을 제공해야 합니다. 이집트에서 식료품 소매업의 현대화에 따라 ISO 22000 규격에 부합하는 식품용 골판지가 주목받고 있습니다. 나이지리아는 장래성이 기대되는 반면, 항만 혼잡과 환율 변동에 직면해 있어, 이러한 요인들이 콜드체인에 대한 투자를 억제하고 있습니다. 그럼에도 불구하고, 걸프협력회의(GCC) 국가들의 종이 포장재 생산액은 2032년까지 128억 달러에 달할 것으로 예측되어, 소매 주도 수요가 지속될 것임을 시사하고 있습니다.
크래프트지 공급 및 가격 변동
이집트는 크라프트 라이너의 60%를 수입하고 있기 때문에 2024년에 파운드 대 유로 환율이 10% 하락함에 따라 도착 비용도 비슷한 수준으로 상승했습니다. 나이지리아의 가공업체들은 나이라 약세와 라고스 항구의 혼잡으로 인해 15-20%의 추가 비용을 부담해야 했습니다. 홍해를 경유하는 우회 항로로 인해 케냐로의 리드타임이 30일에서 50일로 연장되어, 파열 강도 저하 위험을 감수하고서라도 재생 섬유로 대체할 수밖에 없었습니다. 중동 제지 회사의 17억 8,000만 사우디 리얄 규모의 제지 공장 확장 투자 등은 지역 내 생산 능력을 통해 이러한 변동을 상쇄하는 것을 목표로 하고 있습니다.
부문별 분석
2025년, 슬롯이 있는 컨테이너는 중동 및 아프리카 골판지 포장 시장에서 43.0%의 점유율을 유지하며, 그 비용 효율성과 케이스 조립기와의 호환성을 입증하고 있습니다. 이러한 컨테이너는 사우디아라비아,아랍에미리트, 이집트, 남아프리카공화국에서 대량의 식품 및 음료 운송에 있어 여전히 표준적인 선택지로 자리 잡고 있습니다. 한편, 다이컷 컨테이너는 2031년까지 연평균 성장률(CAGR) 3.11%를 기록하며, 중동 및 아프리카 골판지 포장 시장 전체의 성장률을 상회할 것으로 전망됩니다. 전자상거래 플랫폼에서는 빈 공간을 줄이고 부피 중량 요금을 절감하는 동시에, 개봉 시 경험을 향상시키는 제품에 딱 맞는 포장이 요구되고 있습니다. drupa 2024에서 발표된 인라인 디지털 인쇄 시스템을 통해 컨버터는 단 500개 로트만으로도 QR 코드가 포함된 그래픽을 추가할 수 있게 되어, 금형 제작 지연 없이 마이크로 브랜드의 미적 요구를 충족시킬 수 있게 되었습니다. 5패널 접이식 상자는 평평하게 포장된 의류의 수출에 유용하며, 한편 텔레스코픽 박스는 2피스 구조를 통해 내압성을 확보하여 자동차 및 중장비 예비 부품의 운송에 활용되고 있습니다. 블리스 박스와 자동 조립식 컨테이너는 위변조 방지 기능, 완충성, 신속한 주문 처리를 중시하는 의약품 및 전자기기 틈새 시장에서 활용되고 있습니다.
중동 및 아프리카의 골판지 포장 시장에서 다이컷 디자인 시장 규모는 라스트 마일 네트워크 확충에 따라 꾸준히 확대될 것으로 예측됩니다. 걸프협력회의(GCC) 회원국의 각 컨버터 기업들은 접힘 내구성을 높이는 레이저 다이컷 라인을 도입하고 있으며, 이를 통해 테이프 사용량을 줄일 수 있는 셀프락식 플랩을 구현할 수 있게 되었습니다. 이러한 기술적 전환은 재활용이 불가능한 완충재 사용을 처벌 대상으로 하는 확대 생산자 책임(EPR) 규정에도 부합합니다. 그 결과, 디지털 결제, 역물류, 스마트폰 보급률이 높은 시장에서 다이컷의 채택이 가장 빠르게 확대될 전망입니다.
2025년, 중동 및 아프리카 골판지 포장 시장에서 단층 골판지는 48.2%의 점유율을 차지했습니다. 상온에서 식료품 유통에 충분한 200-300 psi의 파열 강도와 매끄럽고 인쇄에 적합한 표면 덕분에 식품, 음료, 일용소비재(FMCG) 각 분야에서 주력 제품으로 자리 잡고 있습니다. 이중벽 골판지는 중량급 가전제품 및 가전 기기의 포장에 적합하며, 400-500 psi의 강도를 갖추면서도 목재 상자에 비해 경량화를 실현하고 있습니다. 1,000 psi를 넘는 강도를 자랑하는 3중 벽 골판지는 AfCFTA(아프리카 대륙 자유무역지대)에 따른 기계·화학제품의 국경 간 무역에 힘입어 연평균 성장률(CAGR) 3.89%라는 가장 급격한 성장세를 보이고 있습니다. 중동 및 아프리카의 골판지 포장 시장에서 수출업체들이 목재 상자를 대체할 수 있는 훈증 처리가 필요 없고 가벼운 대체품을 찾음에 따라 삼중벽 골판지의 용도는 시장 규모가 확대될 것입니다. 중동 페이퍼 컴퍼니의 5호 기계는 내구성이 뛰어난 라이너 등급을 위해 설계되었으며, 이는 지역 제지 회사들이 3중 벽 골판지 생산 능력에 대한 지속적인 수요를 예상하고 있음을 나타냅니다. 솔리드 파이버 보드는 매우 높은 강성을 갖추고 있지만, 무게가 무겁다는 이유로 여전히 고부가가치 전자기기 용도로만 제한되어 있습니다.
가격에 민감한 아프리카의 주요 무역 루트에서는 당초 트리플 월에 30-40%의 추가 비용이 발생한다는 점에 거부감을 느낄 수 있겠지만, 총 도착 비용 분석에 따르면 운송비 절감과 파손 감소로 인해 초기 비용이 상쇄되는 것으로 나타났습니다. 사헬 횡단 도로의 개량과 아프리카의 뿔 지역 내 철도망 확충을 통해, 가혹한 취급 환경에서의 트리플 월의 내구성 우위가 더욱 두드러질 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the Middle East and Africa corrugated packaging market size is projected to expand from USD 9.02 billion in 2025 and USD 9.23 billion in 2026 to USD 10.32 billion by 2031, registering a CAGR of 2.26% between 2026 and 2031.

This report is Segmented by Box Type (Slotted Containers, Die-Cut Containers, Five-Panel Folder Boxes, Telescopic Boxes, and More), Board Grade (Single-Wall Board, Double-Wall Board, and More), Flute Size (A-Flute, B-Flute, and More), End-User Industry (Food, Beverage, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Middle-East And Africa Corrugated Packaging Market Trends and Insights
E-commerce Boom Driving Last-Mile-Friendly Packaging
Online retail in the region expanded by 30% in 2024, boosting demand for die-cut cartons that slash dimensional-weight fees and withstand reverse-logistics handling. Saudi Arabia's digital-payment adoption lifted e-commerce penetration in tier-2 cities, prompting converters to specify F-Flute and micro-flute profiles for 20-30% material savings. In the United Arab Emirates, cross-border marketplaces require tamper-evident, multilingual graphics, intensifying interest in variable-data digital printing. Inline hybrid presses shown at drupa 2024 allow runs of 500 units, letting micro-brands personalize graphics without plate lead times. Collectively, these shifts lead converters to retool for shorter order cycles, narrower flutes, and interactive QR-codes that double as returns portals.
Rapid Expansion of FMCG and Organised Retail
Hypermarket chains in Saudi Arabia, the United Arab Emirates, and Egypt are scaling into secondary cities where summer temperatures top 45 °C. Corrugated shippers must comply with Saudi Food and Drug Authority labelling, carry Arabic text, and survive high-humidity distribution. Egypt's grocery modernisation brings ISO 22000 food-grade board to the forefront. Nigeria, while promising, contends with port congestion and currency swings that suppress cold-chain investment. Still, Gulf Cooperation Council paper-packaging output is forecast to hit USD 12.8 billion by 2032, signalling sustained retail-led demand.
Volatility in Kraft Paper Supply and Prices
Egypt imports 60 % of its kraft liner, so a 10 % pound-euro slide in 2024 pushed up landed costs equivalently. Nigerian converters faced 15-20 % surcharges tied to naira depreciation and Lagos port congestion. Red Sea diversions extended Kenyan lead times from 30 to 50 days, forcing recycled-fiber substitution that compromised burst strength. Investments like Middle East Paper Company's SAR 1.78 billion mill expansion aim to offset such volatility via regional capacity.
Other drivers and restraints analyzed in the detailed report include:
- Government Incentives for Local Manufacturing and Recycling
- Export-Oriented Fresh-Produce Logistics Growth
- Competition from Flexible Plastic Packaging
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Slotted containers retained a 43.0 % share of the Middle East and Africa corrugated packaging market in 2025, testament to their cost efficiency and compatibility with case erectors. They remain the default for high-volume food and beverage shipments across Saudi Arabia, the United Arab Emirates, Egypt, and South Africa. Die-cut containers, however, chart a 3.11 % CAGR to 2031, outpacing the overall Middle East and Africa corrugated packaging market. E-commerce platforms mandate custom-fit packaging that trims void space and lowers dimensional-weight charges, while enhancing the unboxing moment. Inline digital-printing systems unveiled at drupa 2024 enable converters to add QR-coded graphics in runs as low as 500 units, meeting micro-brand aesthetics without tooling delays. Five-panel folders aid flat-packed apparel exports, whereas telescopic boxes serve automotive and heavy-machinery spares where two-piece construction ensures crush resistance. Bliss boxes and self-erecting containers sit in niche pharmaceutical and electronics channels that prize tamper evidence, cushioning, and rapid fulfilment.
The Middle East and Africa corrugated packaging market size for die-cut designs is projected to expand steadily as last-mile networks deepen. Converters in Gulf Cooperation Council cities are adding laser-die lines that sharpen crease tolerance, enabling self-locking flaps which reduce tape usage. This engineering shift also aligns with extended-producer-responsibility rules that penalize non-recyclable void-fill. As a result, die-cut adoption will rise fastest in markets where digital payments, reverse logistics, and smartphone penetration intersect.
Single-wall board accounted for 48.2 % of Middle East and Africa corrugated packaging market share in 2025. Its 200-300 psi burst strength, ample for ambient grocery distribution, and its smooth printable surface make it the workhorse across food, beverage, and FMCG lines. Double-wall board supports mid-weight consumer electronics and appliances, offering 400-500 psi while still cutting weight relative to wood crates. Triple-wall board, boasting over 1,000 psi, shows the sharpest growth at 3.89 % CAGR, propelled by AfCFTA cross-border machinery and chemicals trade. The Middle East and Africa corrugated packaging market size for triple-wall applications will accelerate as exporters seek fumigation-free, lighter alternatives to wooden crates. Middle East Paper Company's fifth machine is tailored for heavy-duty liner grades, a signal that regional mills expect sustained demand for triple-wall capacity. Solid fiber board, despite ultimate rigidity, stays relegated to high-value electronics due to its weight premium.
Price-sensitive African corridors may initially resist triple-wall's 30-40 % cost premium, yet total landed-cost analysis shows freight savings and damage reduction offsetting upfront spend. Trans- Sahel Road upgrades and rail links within the Horn of Africa will further underscore triple-wall's durability advantage in rough-handling environments.
Complete Report Scope:
- By Box Type
- Slotted Containers
- Die-cut Containers
- Five-panel Folder Boxes
- Telescopic Boxes
- Other Box Types
- By Board Grade
- Single-wall Board
- Double-wall Board
- Triple-wall Board
- Solid Fiber Board
- By Flute Size
- A-Flute
- B-Flute
- C-Flute
- E-Flute
- F-Flute
- Other Flutes
- By End-User Industry
- Food
- Beverage
- Consumer Electronics and Electrical Appliances
- Personal Care and Household Care
- Industrial and Chemicals
- Agriculture and Fresh Produce
- E-commerce and Retail
- Other End-Users
- By Geography
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- Egypt
- South Africa
- Nigeria
- Rest of Africa
- Middle East
List of Companies Covered in this Report:
- Arabian Packaging Co. LLC
- Queenex Corrugated Carton Factory LLC
- United Carton Industries Company
- Napco National CJSC
- Cepack Group SARL
- Falcon Pack IND LLC
- World Pack Industries LLC
- Universal Carton Industries Group LLC
- Express Pack Print LLC
- Green Packaging Boxes Industries LLC
- Tarboosh Packaging Co. LLC
- Unipack Containers & Carton Products LLC
- Al Rumanah Packaging LLC
- NBM Pack LLC
- Mondi plc
- Smurfit Kappa Group plc
- International Paper Company
- Middle East Paper Company
- INDEVCO Paper Containers SAL
- Obeikan Paper Industries Co.
- National Paper Company SAE
- RAK Packaging LLC
- Al Bayader International LLC
- Hadera Paper Ltd. (Amnir Corrugated)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Value-Chain Analysis
- 4.3 Regulatory Landscape
- 4.4 Technological Outlook
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Market Drivers
- 4.6.1 E-commerce Boom Driving Last-Mile-Friendly Packaging
- 4.6.2 Rapid Expansion of FMCG and Organised Retail
- 4.6.3 Government Incentives for Local Manufacturing and Recycling
- 4.6.4 Export-Oriented Fresh-Produce Logistics Growth
- 4.6.5 Inter-African Trade Surge Under AfCFTA
- 4.6.6 Digital Printing Adoption for Micro-Brands
- 4.7 Market Restraints
- 4.7.1 Volatility in Kraft Paper Supply and Prices
- 4.7.2 Competition from Flexible Plastic Packaging
- 4.7.3 Import-Dependent Raw-Material Logistics Risk
- 4.7.4 Water-Scarcity-Driven Mill Regulations
- 4.8 Pricing Analysis
- 4.9 Import and Export Analysis
- 4.10 PESTLE Analysis
- 4.11 Capital Expenditure Trends
- 4.12 Environmental Impact of Corrugated Box Production
- 4.13 Industry Ecosystem Analysis
- 4.14 Porter's Five Forces Analysis
- 4.14.1 Bargaining Power of Suppliers
- 4.14.2 Bargaining Power of Buyers
- 4.14.3 Threat of New Entrants
- 4.14.4 Threat of Substitute Products
- 4.14.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Box Type
- 5.1.1 Slotted Containers
- 5.1.2 Die-cut Containers
- 5.1.3 Five-panel Folder Boxes
- 5.1.4 Telescopic Boxes
- 5.1.5 Other Box Types
- 5.2 By Board Grade
- 5.2.1 Single-wall Board
- 5.2.2 Double-wall Board
- 5.2.3 Triple-wall Board
- 5.2.4 Solid Fiber Board
- 5.3 By Flute Size
- 5.3.1 A-Flute
- 5.3.2 B-Flute
- 5.3.3 C-Flute
- 5.3.4 E-Flute
- 5.3.5 F-Flute
- 5.3.6 Other Flutes
- 5.4 By End-User Industry
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Consumer Electronics and Electrical Appliances
- 5.4.4 Personal Care and Household Care
- 5.4.5 Industrial and Chemicals
- 5.4.6 Agriculture and Fresh Produce
- 5.4.7 E-commerce and Retail
- 5.4.8 Other End-Users
- 5.5 By Geography
- 5.5.1 Middle East
- 5.5.1.1 Saudi Arabia
- 5.5.1.2 United Arab Emirates
- 5.5.1.3 Turkey
- 5.5.1.4 Rest of Middle East
- 5.5.2 Africa
- 5.5.2.1 Egypt
- 5.5.2.2 South Africa
- 5.5.2.3 Nigeria
- 5.5.2.4 Rest of Africa
- 5.5.1 Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Arabian Packaging Co. LLC
- 6.4.2 Queenex Corrugated Carton Factory LLC
- 6.4.3 United Carton Industries Company
- 6.4.4 Napco National CJSC
- 6.4.5 Cepack Group SARL
- 6.4.6 Falcon Pack IND LLC
- 6.4.7 World Pack Industries LLC
- 6.4.8 Universal Carton Industries Group LLC
- 6.4.9 Express Pack Print LLC
- 6.4.10 Green Packaging Boxes Industries LLC
- 6.4.11 Tarboosh Packaging Co. LLC
- 6.4.12 Unipack Containers & Carton Products LLC
- 6.4.13 Al Rumanah Packaging LLC
- 6.4.14 NBM Pack LLC
- 6.4.15 Mondi plc
- 6.4.16 Smurfit Kappa Group plc
- 6.4.17 International Paper Company
- 6.4.18 Middle East Paper Company
- 6.4.19 INDEVCO Paper Containers SAL
- 6.4.20 Obeikan Paper Industries Co.
- 6.4.21 National Paper Company SAE
- 6.4.22 RAK Packaging LLC
- 6.4.23 Al Bayader International LLC
- 6.4.24 Hadera Paper Ltd. (Amnir Corrugated)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-needs Assessment


