|
시장보고서
상품코드
2125314
인도의 실시간 결제 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)India Real Time Payments - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
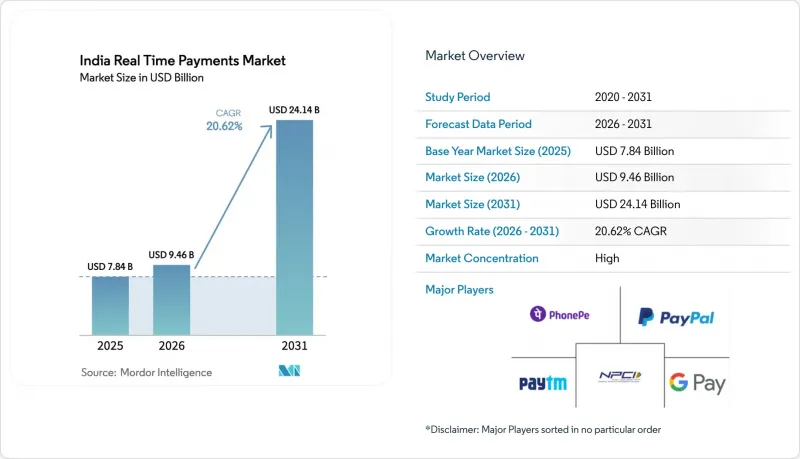
에 의하면, 인도의 실시간 결제 시장 규모는 2025년에 78억 4,000만 달러로 평가되었습니다. 2026년 94억 6,000만 달러에서 2031년까지 241억 4,000만 달러에 이를 것으로 추정되고 예측 기간(2026-2031년) CAGR은 20.62%를 나타낼 전망입니다.
본 보고서는 거래 유형(개인 간(P2P), 개인에서 기업(P2B)), 구성 요소(플랫폼/솔루션, 서비스), 배포 방식(클라우드, On-Premise), 기업 규모(대기업, 중소기업), 최종 사용자 산업(소매 및 전자상거래,BFSI, 유틸리티·통신, 헬스케어, 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러)으로 제시되어 있습니다.
인도의 실시간 결제 시장 동향 및 인사이트
NPCI의 인센티브와 가맹점에 대한 캐시백으로 인해 UPI 도입이 급증
2024-25 회계연도 정부의 150억 루피 인센티브 기금으로 지원된 캐시백 프로그램 덕분에 중소 도시의 거래 건수는 사상 최고치를 경신했으며, 신규 UPI 사용자의 80%가 대도시권 이외 지역에서 발생하고 있습니다. 2,000루피 미만의 거래에 대한 보조금은 가맹점 할인율을 0%로 유지하고 있으며, 이는 키라나 상점이나 노점상들이 QR 코드를 눈에 잘 띄는 곳에 게시하도록 유도하여, 소비자의 편의성이 높아짐에 따라 네트워크 효과의 선순환이 만들어지고 있습니다. 그 결과, P2B 거래량은 P2P 거래량보다 빠르게 증가하고 있으며, 각 PSP 업체들은 확대된 가맹점 네트워크를 활용하여 고객 확보 비용을 절감하고 있습니다. NPCI 보고서에 따르면, 2024년 하반기에는 활성 QR 코드 수가 126% 급증했으며, 어디서나 이용 가능한 QR 코드 결제를 위한 물리적 인프라가 구축되었습니다.
UPI-123PAY를 통한 정부 주도의 상호 운용성
UPI-123PAY를 통해 인도의 4억 명에 달하는 피처폰 사용자는 듀얼 톤 다중 주파수(DTMF) 안내를 통해 실시간 결제를 시작할 수 있게 되었으며, 농촌 지역의 디지털 참여를 제한하던 기기 격차가 해소되었습니다. 2025년 초에는 월간 거래 건수가 이미 1,000만 건을 넘어섰으며, 그 대부분은 스마트폰 보급률이 40% 미만인 주에 집중되었습니다. BSNL 및 Airtel과의 통신사 제휴를 통해 USSD 메시징의 끊김 없는 통신이 보장되고 있습니다. 또한, NPCI의 공통 라이브러리를 통해 네트워크 간 라우팅이 가능해져 벤더 종속을 방지하고, PSP 브랜드에 관계없이 일관된 사용자 경험을 보장하고 있습니다.
농촌 지역의 네트워크 지연이 거래 성공률에 영향을 미침
4G 통신 상황이 불안정한 마을에서는 성수기 실패율이 15%를 넘지만, 대도시권에서는 2-3%에 그치고 있습니다. 현재 60%의 진행률을 보이고 있는 BharatNet의 광섬유 구축을 통해 향후 개선이 예상되지만, 농업 분야의 결제 등 지연에 민감한 부문에서는 여전히 타임아웃 오류가 발생하고 있습니다. 각 PSP 업체들은 거래를 큐에 저장해 나중에 동기화하는 엣지 컴퓨팅 캐시의 시범 운영을 진행하고 있지만, 소액 거래가 주를 이루는 농촌 지역에서는 초기 투자 비용이 막대합니다.
부문별 분석
2025년 1월, P2B는 UPI 총 거래량의 28.45%를 차지했으며, 연평균 성장률(CAGR) 23.85%로 급성장하고 있습니다. 인도의 실시간 결제 시장에서 P2B 결제 시장 규모는 송금 중심의 P2P 결제 흐름보다 빠른 속도로 확대될 전망입니다. 이는 대중교통, 길거리 음식, 공과금 등을 한 번의 스캔으로 결제하는 등 새로운 소비자 습관을 반영한 것입니다. P2B의 평균 거래액은 1,471 루피로, 소액 거래로의 침투가 더욱 진행되고 있음이 확인되었습니다. RuPay 신용카드와의 연동을 통해 즉시 확인 기능을 유지하면서, P2B 지출에 리볼빙 신용의 유연성이 더해지게 됩니다.
그럼에도 불구하고, P2P는 2025년 거래 건수에서 71.55%라는 압도적인 점유율을 유지했으며, 급여 선지급, 집세, 가족 지원과 같은 확고한 이용 사례를 엿볼 수 있습니다. 네팔 및 싱가포르와의 UPI 연동을 통해 가능해진 대륙 간 송금은 해당 부문의 성장률이 정상화되더라도 P2P의 핵심적인 중요성을 유지할 것으로 전망됩니다. 전력망에서 벗어난 농촌 가구는 수확으로 얻은 수익을 신속하게 이체하기 위해 P2P에 의존하고 있으며, 이는 인도의 실시간 결제 시장에 내재된 사회적 포용의 사명을 부각시키고 있습니다.
연평균 성장률(CAGR) 28.05%로 확대될 것으로 예상되는 서비스 부문은 현재 사기 분석, 통합 대조, 대출 API로 구성되어 있습니다. Razorpay와 같은 결제 서비스 제공업체(PSP)는 2024 회계연도에 40개의 신규 서비스 라인을 출시했으며, 가맹점 할인율이 0%인 환경이 제공업체를 가치 피라미드의 최상위로 끌어올리고 있음을 보여줍니다. 인도의 실시간 결제 시장은 밀리초 단위로 거래를 평가하여, 의심스러운 자금 흐름이 결제 처리에 도달하기 전에 차단할 수 있는 AI 기반 리스크 모델의 혜택을 받고 있습니다.
플랫폼/솔루션 매출은 2025년 시장 규모의 63.20%를 차지하며, 새롭게 디지털화를 추진하는 가맹점을 유치하기 위한 관문 역할을 계속해서 수행했습니다. 모듈형 SDK 및 로우코드 통합 키트를 통해 소매업체 시장 출시 시간이 단축되었으며, 기본적인 결제 수락 도구에서 프리미엄 SaaS 구독에 이르는 퍼널이 형성되고 있습니다. 이러한 시너지 효과는 인도의 실시간 결제 업계의 장기적인 수익 창출의 핵심을 이루고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the India real-time payments market size was valued at USD 7.84 billion in 2025 and estimated to grow from USD 9.46 billion in 2026 to reach USD 24.14 billion by 2031, at a CAGR of 20.62% during the forecast period (2026-2031).
This report is Segmented by Transaction Type (Peer-To-Peer (P2P), Peer-To-Business (P2B)), Component (Platform / Solution, Services), Deployment (Cloud, On-Premise), Enterprise Size (Large Enterprises, Small and Medium Enterprises), End-User Industry (Retail and E-Commerce, BFSI, Utilities & Telecom, Healthcare, and More). The Market Forecasts are Provided in Terms of Value (USD).
India Real Time Payments Market Trends and Insights
Surge in UPI adoption driven by NPCI incentives and merchant cash-backs
Cash-back programs funded by the government's INR 1,500 crore incentive pool for FY 2024-25 have pushed transaction counts in smaller cities to new highs, with 80% of new UPI users emerging outside metros. The subsidy on sub-INR 2,000 tickets sustains a zero merchant discount rate, motivating kirana stores and street vendors to display QR codes prominently and creating a network-effect flywheel as consumer convenience rises. P2B volumes have consequently grown faster than P2P volumes, and PSPs have lowered customer-acquisition costs by leveraging expanded merchant footprints. NPCI reports a 126% surge in active QR codes during 2H 2024, supplying the physical infrastructure for omnipresent quick-response payments.
Government-mandated interoperability via UPI-123PAY
UPI-123PAY allows India's 400 million feature-phone users to initiate real-time payments through dual-tone multi-frequency (DTMF) prompts, closing the device-gap that had restricted digital participation in rural districts. Monthly volumes have already exceeded 10 million transactions in early 2025, concentrated in states with sub-40% smartphone penetration. Telecom alliances with BSNL and Airtel ensure unbroken USSD messaging, while NPCI's common library enables cross-network routing, preventing vendor lock-in and guaranteeing a consistent user experience regardless of PSP brand.
Rural network latency hitting transaction success rates
Peak-season failure rates exceed 15% in villages where 4G coverage remains inconsistent, compared to 2-3% in metros. BharatNet's optical-fiber roll-out, currently 60% complete, promises eventual relief, yet delay-sensitive sectors including agriculture payments continue to experience timeout errors. PSPs are testing edge-computing caches that queue transactions for later synchronization, though the upfront capital is substantial for low-ticket rural traffic.
Other drivers and restraints analyzed in the detailed report include:
- Instant settlement demand from gig-economy platforms drives the market
- QR-based offline payments growth in tier-3/4 towns
- Fraud via UPI collect requests & screen-scraping apps hinders the market
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
P2B accounted for 28.45% of total UPI volume in January 2025 and is sprinting ahead at a 23.85% CAGR. The India real-time payments market size for P2B payments is on track to expand faster than remittance-oriented P2P flows, reflecting new consumer habits such as paying for public transport, street food, and utilities with a single scan. Average P2B ticket value stands at INR 1,471, confirming deeper penetration into micro-transactions. RuPay credit-card integration will add revolving-credit elasticity to P2B spend while maintaining instant confirmation.
P2P nevertheless preserves a dominant 71.55% share of 2025 transactions, illustrating entrenched use cases like salary advances, rent, and family support. Transcontinental remittances facilitated by UPI ties with Nepal and Singapore are set to sustain core P2P relevance, even as the segment's growth rate normalizes. Rural off-grid households rely on P2P to move harvest proceeds rapidly, underlining the social-inclusion mandate built into the India real-time payments market.
The services layer, forecast to rise at 28.05% CAGR, now comprises fraud analytics, unified reconciliation, and lending APIs. PSPs such as Razorpay launched 40 new service lines in FY 24, showcasing how the zero merchant discount-rate environment is pushing providers up the value pyramid. The India real-time payments market benefits from AI-driven risk models that can score transactions within milliseconds and throttle suspicious flows before they hit settlement.
Platform/solution revenues still contribute 63.20% of the 2025 base and remain the gateway for onboarding newly digital merchants. Modular SDKs and low-code integration kits reduce time-to-market for retailers, creating a funnel from basic acceptance tools to premium SaaS subscriptions. This stacking effect is central to long-term monetization within the India real-time payments industry.
Complete Report Scope:
- By Transaction Type
- Peer-to-Peer (P2P)
- Peer-to-Business (P2B)
- By Component
- Platform / Solution
- Services
- By Deployment Mode
- Cloud
- On-Premise
- By Enterprise Size
- Large Enterprises
- Small and Medium Enterprises
- By End-User Industry
- Retail and E-Commerce
- BFSI
- Utilities and Telecom
- Healthcare
- Government and Public Sector
- Other End-user Industries
List of Companies Covered in this Report:
- Temenos AG
- ACI Worldwide Inc.
- Google LLC (Alphabet Inc.)
- Mastercard India Services Pvt Ltd
- PhonePe Private Limited
- Razorpay Technologies Pvt Ltd
- Pine Labs Pvt Ltd
- PayPal Payments Private Limited
- BharatPe
- WhatsApp Pay (Meta Platforms Inc.)
- Paytm Payments Bank Ltd
- Financial Software and Systems Pvt Ltd (FSS)
- Cashfree Payments
- Worldline India Pvt Ltd
- Amazon Pay (Amazon.com Inc.)
- Visa Worldwide (India) Pvt Ltd
- PayU Payments Pvt Ltd
- BillDesk (IndiaIdeas.com Ltd)
- CCAvenue (Infibeam Avenues Ltd)
- State Bank of India
- HDFC Bank Ltd
- ICICI Bank Ltd
- Axis Bank Ltd
- Volante Technologies Inc.
- NPCI (National Payments Corporation of India)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in UPI adoption driven by NPCI incentives and merchant cash-backs
- 4.2.2 Government-mandated interoperability via UPI-123PAY
- 4.2.3 Instant settlement demand from gig-economy platforms drives the market
- 4.2.4 QR-based offline payments growth in Tier-3/4 towns drives the market
- 4.2.5 RuPay credit-card linkage on UPI boosts ticket size
- 4.3 Market Restraints
- 4.3.1 Rural network latency hitting transaction success rates
- 4.3.2 Fraud via UPI collect requests and screen-scraping apps hinders the market
- 4.3.3 Interchange disputes curbing PSP monetisation
- 4.4 Value Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers/Consumers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Evolution of the Payments Landscape in India
- 4.8 Key Trends Accelerating Cashless Transactions
- 4.9 Assessment of Macro Economic Trends on the Market
- 4.10 Major Case Studies and Use-Cases
- 4.11 Real-Time Payments Share of Total Transactions
- 4.12 Real-Time Payments Share of Non-Cash Transactions
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Transaction Type
- 5.1.1 Peer-to-Peer (P2P)
- 5.1.2 Peer-to-Business (P2B)
- 5.2 By Component
- 5.2.1 Platform / Solution
- 5.2.2 Services
- 5.3 By Deployment Mode
- 5.3.1 Cloud
- 5.3.2 On-Premise
- 5.4 By Enterprise Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium Enterprises
- 5.5 By End-User Industry
- 5.5.1 Retail and E-Commerce
- 5.5.2 BFSI
- 5.5.3 Utilities and Telecom
- 5.5.4 Healthcare
- 5.5.5 Government and Public Sector
- 5.5.6 Other End-user Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Temenos AG
- 6.4.2 ACI Worldwide Inc.
- 6.4.3 Google LLC (Alphabet Inc.)
- 6.4.4 Mastercard India Services Pvt Ltd
- 6.4.5 PhonePe Private Limited
- 6.4.6 Razorpay Technologies Pvt Ltd
- 6.4.7 Pine Labs Pvt Ltd
- 6.4.8 PayPal Payments Private Limited
- 6.4.9 BharatPe
- 6.4.10 WhatsApp Pay (Meta Platforms Inc.)
- 6.4.11 Paytm Payments Bank Ltd
- 6.4.12 Financial Software and Systems Pvt Ltd (FSS)
- 6.4.13 Cashfree Payments
- 6.4.14 Worldline India Pvt Ltd
- 6.4.15 Amazon Pay (Amazon.com Inc.)
- 6.4.16 Visa Worldwide (India) Pvt Ltd
- 6.4.17 PayU Payments Pvt Ltd
- 6.4.18 BillDesk (IndiaIdeas.com Ltd)
- 6.4.19 CCAvenue (Infibeam Avenues Ltd)
- 6.4.20 State Bank of India
- 6.4.21 HDFC Bank Ltd
- 6.4.22 ICICI Bank Ltd
- 6.4.23 Axis Bank Ltd
- 6.4.24 Volante Technologies Inc.
- 6.4.25 NPCI (National Payments Corporation of India)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment