|
시장보고서
상품코드
2125359
화학 산업용 밸브 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Chemical Industry Valves - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
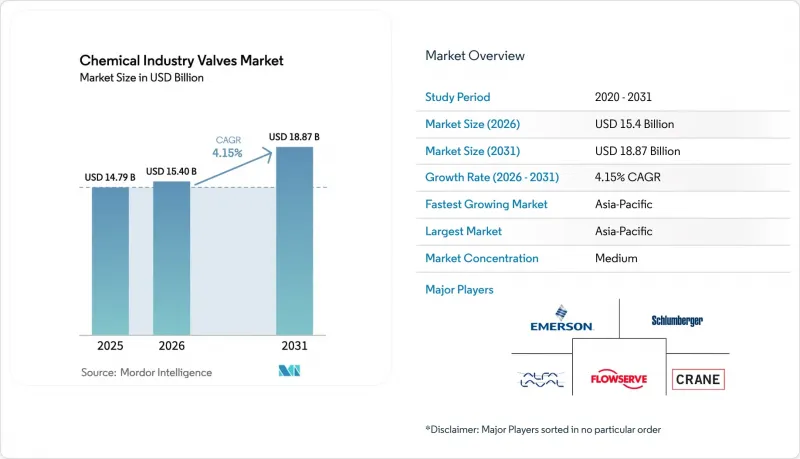
에 의하면, 화학 산업용 밸브 시장 규모는 2025년 147억 9,000만 달러로 평가되었고, 2026년에는 154억 달러로 추정되고, 2026-2031년 CAGR 4.15%로 성장을 지속할 전망이며, 2031년에는 188억 7,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 밸브 유형별(볼, 버터플라이, 게이트, 글로브, 체크 등), 재질별(스테인리스 스틸, 주철, 합금계, 플라스틱/PVC, 극저온용, 특수 합금), 밸브 크기별(1인치 이하, 1-6인치, 6-25인치, 25-50인치, 50인치 이상과), 작동 기술별(수동, 공압, 전동, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
화학 산업용 밸브 시장 인사이트 및 동향
인더스트리 4.0·스마트 제어 도입 가속화
압력, 진동, 위치 센서를 탑재한 디지털 대응 밸브는 현재 분산형 제어 시스템과 원활하게 통합되어 있으며, 예측 정비를 가능하게 함으로써 예기치 못한 가동 중단 시간을 25-30% 줄이는 동시에, API 624 저배출 규정에 요구되는 감사 추적을 제공합니다. 사업자들은 사이버 침입을 방지하기 위해 밸브 펌웨어에 블록체인 기반 인증 기능을 추가하고 있지만, 연간 5만-20만 달러에 달하는 사이버 보험 비용은 소규모 화학 플랜트에 있어 여전히 장벽으로 작용하고 있습니다. 각 벤더는 중요한 안전 루프를 기업 네트워크에서 격리하는 에어 갭(air gap)형 아키텍처를 도입하고, 성능과 위험 완화의 균형을 맞추어 이에 대응하고 있습니다. 스마트 밸브의 도입은 고령 기술자들의 은퇴 속에서 인력 배치를 효율화하고, 화학 산업용 밸브 시장의 만성적인 기술 인력 부족을 완화합니다. 개념 증명(PoC) 파일럿 프로젝트가 여러 거점으로 확대됨에 따라, 아시아태평양 및 북미 전역에서 도입 대상이 급속히 확대되고 있습니다.
전 세계 HSE 규제 및 배출 기준의 강화
API 641, ISO 15848, 유럽연합(EU)의 산업 배출 지침에 따라 조달 기준이 재검토되어, 누출률이 100ppm 미만인 트리플 오프셋형 버터플라이 밸브와 금속 시트형 볼 밸브가 중요시되고 있습니다. 위반 건당 10만-50만 달러의 벌금이 부과됨에 따라 사업자들은 완전히 인증된 제품군의 도입을 강요받고 있으며, 풍부한 인증 데이터를 보유한 다국적 기업과 밸브 제품군 하나당 200만 달러가 넘는 시험 비용에 직면한 틈새 기업 간의 경쟁 격차가 확대되고 있습니다. 규정 준수 요건으로 인해 성숙한 플랜트의 교체 주기가 단축되는 한편, 유럽과 북미에서는 수소 대응 솔루션에 대한 그린필드 수요가 자극되고 있습니다. 저배출 설계에 대한 20-30%의 프리미엄 가격은 벌금 회피 및 누출 배출세 감축을 통해 상쇄되어, 사양 채택의 추세를 더욱 강화하고 있습니다.
니켈·몰리브덴 가격 변동이 합금 비용을 끌어올립니다.
상하이 금속 시장(Shanghai Metals Market)에 따르면, 2024년에 니켈 가격은 35-40%, 몰리브덴 가격은 25-30% 변동하여 니켈 합금 밸브의 견적 가격이 18% 상승했습니다. 특수 밸브 제조 비용 중 최대 70%를 원자재가 차지하기 때문에 공급업체들은 이익률을 유지하기 위해 분기별 가격 인상 조항이나 최소 주문 수량을 도입하고 있습니다. 이에 반해 최종 사용자는 입찰 주기를 연장하거나 가격 하락 시 선물 임베디드을 통해 대응하고 있어, 수요 변동을 초래하고 생산 계획 수립을 복잡하게 만들고 있습니다. 이러한 제약 요인으로 인해 비용 효율을 중시하는 프로젝트에서 내식성 소재의 채택이 제한되고 있으며, 단기적으로는 화학 산업용 밸브 시장의 성장세가 소폭 둔화되고 있습니다.
부문 분석
화학 산업용 밸브 시장에서 볼 밸브 시장 규모는 2025년에 27억 3,000만 달러에 달했으며, 18.44%라는 가장 높은 점유율을 차지했습니다. 이는 부식성 매체에서 신뢰할 수 있는 차단 성능과 광범위한 ANSI 압력 등급에 대한 대응 능력에 힘입은 결과입니다. 멀티포트형 및 극저온용 모델은 연속 공정 및 배치 공정에서 입지를 더욱 공고히 하고 있습니다. 각 공급업체들은 볼 밸브에 스마트 디지털 포지셔너를 결합하여 제공하고 있으며, 이를 통해 유지보수 작업을 20% 절감할 수 있어 주요 석유화학 기업들로부터 확고한 지지를 얻고 있습니다.
한편, 진공 밸브는 2031년까지 연평균 성장률(CAGR) 4.92%를 기록할 전망이며, 다른 모든 카테고리를 능가하는 성장이 예상됩니다. 반도체 화학 기상 증착(CVD) 라인이나 제약 업계의 동결 건조 챔버에서는 게이트 밸브나 기존의 차단 밸브로는 실현할 수 없는 초저누설률이 요구되고 있습니다. 플로우서브(FlowServ)의 고순도 스테인리스 스틸 내부 부품을 특징으로 하는 스프링리스 설계는 10억 분의 1 단위의 오염 임계치를 목표로 하는 팹(반도체 제조 공장)으로부터 지지를 받는 성능의 비약을 여실히 보여주고 있습니다. 이러한 급속한 성장은 중국, 일본, 미국에서 반도체 투자를 유치하려는 각국 정부의 이니셔티브에 힘입어 더욱 가속화되고 있으며, 수년에 걸친 진공 밸브의 교체 주기가 조성되고 있습니다.
스테인리스 스틸은 내식성과 비용 효율성의 균형을 활용하여 2025년 화학 산업용 밸브 시장에서 41.29%라는 압도적인 점유율을 유지했습니다. 중성 pH의 유기물 처리에서는 316L이 여전히 표준 사양인 반면, 염화물을 많이 함유한 유체에서는 듀플렉스 강종의 채택이 확대되고 있습니다. 예비 부품의 호환성과 전 세계적인 재고 네트워크가 결합되어, 여러 공장을 운영하는 사업자들의 지지를 강화하고 있습니다.
특수 합금, 특히 티타늄과 하스텔로이 수요는 그린 수소용 전해조의 요구 사항과 황산 기반 특수 제품 생산을 반영하여 연평균 성장률(CAGR) 5.58%를 기록할 전망입니다. 티타늄의 생체 적합성은 원료의약품(API) 제조 라인에 적합하며, 한편 하스텔로이 C-276은 혼합산 반응기에서 긴 수명을 실현합니다. NACE MR0175 규격 준수는 사워가스 유래 제품의 채택을 더욱 촉진하고 있습니다. 이러한 변화로 인해 가격 프리미엄이 300%를 초과하는 상황에서도 수익원이 확대되어, 화학 산업용 밸브 시장 내 고합금 카테고리 시장 규모를 끌어올리고 있습니다.
지역별 분석
아시아태평양은 중국의 특수 화학제품 생산량이 8.2% 증가한 것과 인도의 제약 산업 확대에 힘입어 2025년 매출의 38.75%를 차지했습니다. Rongsheng Petrochemical의 절강성 복합 시설 등 국가가 지원하는 프로젝트에서는 MRI 규격에 부합하는 저누출 밸브가 지정되어 있는 반면, 일본과 한국의 제조 공장에서는 초고순도 진공용 밸브가 선호되고 있습니다. 지역 내 각 OEM 기업들은 수입 관세를 회피하기 위해 액추에이터 및 주조 공정의 현지화를 추진하고 있으며, 이를 통해 공급망 기반이 더욱 견고해지고 있습니다.
북미는 두 번째로 큰 규모를 자랑하는 지역으로, 미국 멕시코만 연안의 셰일가스 기반 석유화학 투자가 중심을 이루고 있습니다. 교체 주기에서는 환경보호청(EPA)의 LDAR 프로그램을 충족하기 위해 API 624 인증 제품이 중시되고 있으며, 2030년 예산에는 분석 기능을 통합한 예측 유지보수를 위한 개보수 비용이 포함되어 있습니다. 캐나다의 블루 수소 프로젝트로 인해 취화 저항 합금에 대한 수요가 증가하고 있습니다.
유럽에서는 ‘산업 배출 지침’에 기반한 규제 주도형 설비 갱신 투자가 특징이며, 이에 따라 누출이 적은 밸브에 대한 꾸준한 갱신 수요가 발생하고 있습니다. 독일 및 스칸디나비아의 화학 산업 클러스터에서는 적층 가공를 통한 예비 부품 도입이 선도적으로 이루어지고 있는 반면, 영국의 거점에서는 NIS 2 지침 시행 이후 사이버 보안이 강화된 액추에이터가 우선적으로 채택되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the chemical industry valves market size is expected to grow from USD 14.79 billion in 2025 to USD 15.4 billion in 2026 and is forecast to reach USD 18.87 billion by 2031 at 4.15% CAGR over 2026-2031.
This report is Segmented by Valve Type (Ball, Butterfly, Gate, Globe, Check, and More), Material (Stainless Steel, Cast Iron, Alloy-Based, Plastic/PVC, Cryogenic-Grade, and Exotic Alloys), Valve Size in Inches (Up To 1", 1"-6", 6"-25", 25"-50", and, Above 50"), Actuation Technology (Manual, Pneumatic, Electric, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Insights and Trends of Chemical Industry Valves Market
Accelerating Adoption of Industry 4.0 and Smart Control
Digitally enabled valves equipped with pressure, vibration, and position sensors now integrate seamlessly with distributed control systems, allowing predictive maintenance that cuts unplanned downtime by 25-30% while providing the audit trail demanded under API 624 low-emission rules. Operators are layering blockchain-based authentication on valve firmware to deter cyber-intrusions, yet annual cyber-insurance outlays ranging from USD 50,000 to 200,000 remain a barrier for smaller chemical plants. Vendors are responding with air-gapped architectures that isolate critical safety loops from enterprise networks, balancing performance with risk mitigation. Smart-valve retrofits also streamline workforce allocation as aging technicians retire, easing the chemical industry valves market's chronic skills shortage. As proof-of-concept pilots convert into multi-site rollouts, the addressable installed base grows rapidly across Asia-Pacific and North America.
Tightening Global HSE Regulations and Emission Norms
API 641, ISO 15848, and the European Union Industrial Emissions Directive have reframed procurement criteria, elevating triple-offset butterfly and metal-seated ball valves capable of leakage rates below 100 ppm. Fines of USD 100,000-500,000 per violation push operators toward fully certified portfolios, widening the competitive gap between multinationals with extensive qualification data and niche firms facing test costs surpassing USD 2 million per valve family. Compliance mandates are shortening replacement cycles in mature plants and stimulating greenfield demand for hydrogen-ready solutions in Europe and North America. Premium pricing of 20-30% on low-emission designs is offset by avoided penalties and reduced fugitive-emission taxes, reinforcing spec-in momentum.
Volatile Nickel/Molybdenum Prices Inflating Alloy Costs
Nickel prices swung 35-40% and molybdenum 25-30% during 2024, driving an 18% hike in nickel-alloy valve quotations according to Shanghai Metals Market. With raw materials representing up to 70% of exotic valve manufacturing cost, suppliers have adopted quarterly price escalators and minimum order sizes to preserve margins. End-users counter by lengthening bid cycles and forward-buying during price dips, injecting demand volatility that complicates production planning. The restraint constrains the uptake of corrosion-resistant materials in cost-sensitive projects, marginally diluting the chemical industry valves market growth trajectory in the short term.
Other drivers and restraints analyzed in the detailed report include:
- Specialty-Chemical Capacity Surge in APAC
- Lifecycle-Cost Optimization Favoring Corrosion-Resistant Valves
- Cyber-Insurance Premiums Curbing Full IoT Adoption
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The chemical industry valves market size for ball valves represented USD 2.73 billion in 2025 and held the highest 18.44% share, sustained by reliable shut-off across corrosive media and broad ANSI pressure classes. Multiport and cryogenic variants have further entrenched presence in continuous and batch processes. Vendors bundle ball valves with smart digital positioners that trim maintenance labor by 20%, cementing loyalty among large petrochemical accounts.
Vacuum valves however are projected to outpace all other categories at a 4.92% CAGR through 2031. Semiconductor chemical vapor deposition lines and pharmaceutical freeze-drying chambers demand ultra-low leak rates that gate valves or traditional shuts cannot deliver. Flowserve's spring-less designs featuring high-purity stainless internals illustrate the capability leap favored by fabs targeting parts-per-billion contamination thresholds. The surge is further supported by governments courting chip investments in China, Japan, and the United States, priming a multiyear vacuum-valve upgrade cycle.
Stainless steel retained a commanding 41.29% of chemical industry valves market share in 2025 on its balance of corrosion resistance and cost efficiency. 316L remains the default in neutral-pH organics, while duplex grades expand in chloride-laden streams. Combined spare-parts commonality and global stocking networks reinforce preference among multi-plant operators.
Exotic-alloy demand, particularly titanium and Hastelloy, is set to register a 5.58% CAGR, reflecting green-hydrogen electrolyzer requirements and sulfuric-acid based specialty production. Titanium's biocompatibility aligns with active pharmaceutical ingredient lines, whereas Hastelloy C-276 delivers longevity in mixed-acid reactors. NACE MR0175 compliance further drives uptake in sour-gas derivatives. The shift widens revenue pools even as price premiums exceed 300%, elevating the chemical industry valves market size for high-alloy categories.
Complete Report Scope:
- By Valve Type
- Ball
- Butterfly
- Gate
- Globe
- Check
- Plug
- Diaphragm
- Vacuum
- Hybrid
- Other Valve Types
- By Material
- Stainless Steel
- Cast Iron
- Alloy-Based
- Plastic / PVC
- Cryogenic-Grade
- Exotic Alloys (Ti, Hastelloy)
- By Valve Size (Inches)
- Up to 1"
- 1" - 6"
- 6" - 25"
- 25" - 50"
- Above 50"
- By Actuation Technology
- Manual
- Pneumatic
- Electric
- Hydraulic
- Smart (IoT-enabled)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific generated 38.75% of 2025 revenue, driven by China's 8.2% rise in specialty-chemical output and India's pharmaceutical build-out. State-backed projects such as Rongsheng Petrochemical's Zhejiang complex specify MRI-compliant low-leak valves, while Japanese and South Korean fabs favor ultra-high-purity vacuum variants. Regional OEMs are localizing actuator and casting operations to sidestep import duties, further cementing supply-chain heft.
North America represents the second-largest region, anchored by shale-gas derived petrochemical investments on the U.S. Gulf Coast. Replacement cycles focus on API 624 certified options to satisfy Environmental Protection Agency LDAR programs, with predictive-maintenance retrofits bundling analytics into 2030 budgets. Canada's blue-hydrogen projects add demand for embrittlement-resistant alloys.
Europe is characterized by regulatory-driven upgrade expenditure under the Industrial Emissions Directive, leading to steady replacement demand for low-fugitive valves. German and Scandinavian chemical clusters are early adopters of additive-manufactured spare parts, while United Kingdom sites prioritize cybersecurity- fortified actuators post-NIS 2 directive.
- Emerson Electric Co.
- Flowserve Corporation
- Schlumberger Limited (Cameron)
- Alfa Laval Corporate AB
- Crane Company
- Rotork plc
- KITZ Corporation
- IMI plc
- Samson Aktiengesellschaft
- Valmet Oyj
- Honeywell International Inc.
- Schneider Electric SE
- Siemens AG
- Parker Hannifin Corporation
- Curtiss-Wright Corporation
- AVK Holding A/S
- Spirax-Sarco Engineering plc
- Velan Inc.
- Neway Valve (Suzhou) Co., Ltd.
- CIRCOR International, Inc.
- Metso Corporation
- Christian Burkert GmbH and Co. KG
- Johnson Controls International plc
- AUMA Riester GmbH and Co. KG
- Pentair plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating adoption of Industry 4.0 and smart control
- 4.2.2 Tightening global HSE regulations and emission norms
- 4.2.3 Specialty-chemical capacity surge in Asia-Pacific
- 4.2.4 Lifecycle-cost optimisation favouring corrosion-resistant valves
- 4.2.5 Hydrogen-ready specifications for green-chem production lines
- 4.2.6 Additive-manufactured spare-parts and modular valve bodies
- 4.3 Market Restraints
- 4.3.1 Volatile nickel/molybdenum prices inflating alloy costs
- 4.3.2 Fragmented certification standards delaying projects
- 4.3.3 Cyber-insurance premiums curbing full IoT adoption
- 4.3.4 Asia-Pacific skill-gap driving preference for low-complexity valves
- 4.4 Industry Ecosystem Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Valve Type
- 5.1.1 Ball
- 5.1.2 Butterfly
- 5.1.3 Gate
- 5.1.4 Globe
- 5.1.5 Check
- 5.1.6 Plug
- 5.1.7 Diaphragm
- 5.1.8 Vacuum
- 5.1.9 Hybrid
- 5.1.10 Other Valve Types
- 5.2 By Material
- 5.2.1 Stainless Steel
- 5.2.2 Cast Iron
- 5.2.3 Alloy-Based
- 5.2.4 Plastic / PVC
- 5.2.5 Cryogenic-Grade
- 5.2.6 Exotic Alloys (Ti, Hastelloy)
- 5.3 By Valve Size (Inches)
- 5.3.1 Up to 1"
- 5.3.2 1" - 6"
- 5.3.3 6" - 25"
- 5.3.4 25" - 50"
- 5.3.5 Above 50"
- 5.4 By Actuation Technology
- 5.4.1 Manual
- 5.4.2 Pneumatic
- 5.4.3 Electric
- 5.4.4 Hydraulic
- 5.4.5 Smart (IoT-enabled)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Emerson Electric Co.
- 6.4.2 Flowserve Corporation
- 6.4.3 Schlumberger Limited (Cameron)
- 6.4.4 Alfa Laval Corporate AB
- 6.4.5 Crane Company
- 6.4.6 Rotork plc
- 6.4.7 KITZ Corporation
- 6.4.8 IMI plc
- 6.4.9 Samson Aktiengesellschaft
- 6.4.10 Valmet Oyj
- 6.4.11 Honeywell International Inc.
- 6.4.12 Schneider Electric SE
- 6.4.13 Siemens AG
- 6.4.14 Parker Hannifin Corporation
- 6.4.15 Curtiss-Wright Corporation
- 6.4.16 AVK Holding A/S
- 6.4.17 Spirax-Sarco Engineering plc
- 6.4.18 Velan Inc.
- 6.4.19 Neway Valve (Suzhou) Co., Ltd.
- 6.4.20 CIRCOR International, Inc.
- 6.4.21 Metso Corporation
- 6.4.22 Christian Burkert GmbH and Co. KG
- 6.4.23 Johnson Controls International plc
- 6.4.24 AUMA Riester GmbH and Co. KG
- 6.4.25 Pentair plc
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment