|
시장보고서
상품코드
2125412
싱가포르의 사이버 보안 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Singapore Cybersecurity - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
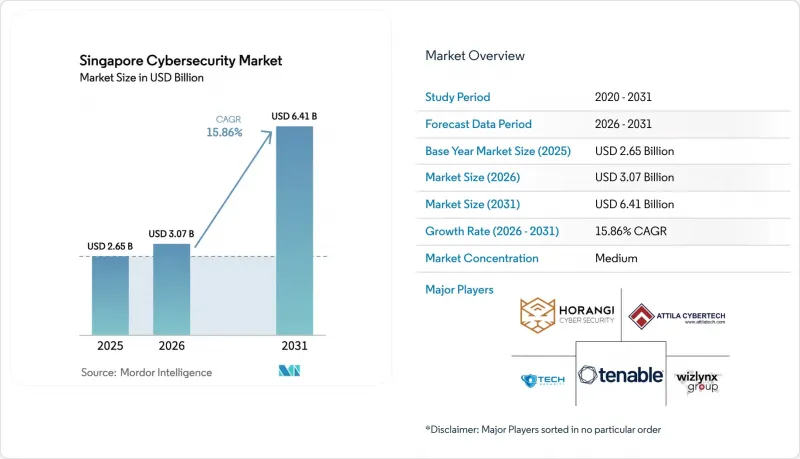
에 의하면, 2026년 싱가포르 사이버 보안 시장 규모는 30억 7,000만 달러로 추정되고, 2025년 26억 5,000만 달러에서 성장하여 2031년에는 64억 1,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 15.86%로 성장할 전망이며, 이 도시 국가가 동남아시아의 디지털 중심지로서의 입지를 공고히 할 전망입니다(1) 싱가포르 사이버보안청(CSA), 'Singapore Cyber Landscape 2024', csa.gov.sg.
본 보고서에서는 산업을 제공 제품별(솔루션 및 서비스), 배포 방식별(클라우드 및 온프레미스), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 헬스케어, IT 및 통신, 산업·방위, 제조업, 소매 및 전자상거래, 에너지·유틸리티, 기타), 최종 사용자 기업 규모별(중소기업(SME) 및 대기업)로 분류하고 있습니다.
싱가포르의 사이버 보안 시장 동향 및 인사이트
정부의 전국적인 제로 트러스트 아키텍처 의무화
규제 당국은 현재 모든 중요 정보 인프라 소유자에게 제로 트러스트 로드맵 제출을 의무화하고 있으며, 2024년 11월까지 96%가 계획을 제출했습니다. 금융 기관들은 이에 대응하여 트래픽 마이크로 세분화을 시행한 결과, 운영 개시 1년 이내에 무단 접근 사례를 42% 감소시켰습니다. 예산 주기에서 보안 지출의 최대 28%가 신원 확인 분석에 할당되고 있어, 컨텍스트 인식형 접근 제어에 대한 수요가 높다는 점이 부각되고 있습니다. 여러 기관에 의한 설계 검토의 효율화로 인해 정책 승인까지 소요되는 기간이 34일로 단축되었고, 기존 지연 시간이 절반으로 줄어들면서 벤더들은 수익 계상을 가속화할 수 있게 되었습니다. 이러한 움직임들이 맞물려 제로 트러스트 구현이 모든 주요 입찰의 핵심으로 자리 잡았으며, 적응형 신뢰 점수 산정을 지원하는 공급업체에게 결정적인 우위를 제공합니다.
디지털 은행 라이선스 발급 가속화가 차세대 BFSI 보안 지출을 견인
디지털 풀뱅크 라이선스 취득 업체들은 2024년 말까지 18억 싱가포르 달러의 예금을 유치했으며, 이는 싱가포르 개인 저축 총액의 4%에 해당합니다. 신규 진출기업들은 첫해에 영업 지출의 약 22%를 사이버 보안에 할당했습니다. 이러한 추세는 기존 사업자에서도 나타나며, 2024년에는 복원력(resilience)에 대한 투자가 36% 증가하여 4억 9,100만 싱가포르 달러에 달했습니다. 포스트 양자암호화 기술의 시범 도입을 통해 이미 국내 은행 간 거래의 12%가 보호되고 있습니다. 현재 경쟁 우위는 위협 인텔리전스의 신속한 확보와 규정 준수 증거의 자동화에 달려 있으며, 예산은 독립형 어플라이언스가 아닌 관리형 감지 및 대응(MDR) 플랫폼으로 이동하고 있습니다. 은행 부문의 조기 도입 물결은 결제, 자산 운용, 자본 시장 시스템으로 확산되고 있으며, 싱가포르 사이버 보안 시장의 총 잠재 수요를 확대시키고 있습니다.
CREST 인증 인력 부족으로 서비스 비용 상승
2024년 현재, 현지에서 활동하는 CREST 인증 전문가는 530명에 그쳐, 수요인 1,200명에 비해 56%의 격차가 발생하고 있습니다. 수석 분석가의 급여 중앙값은 14% 상승한 11만 7,000싱가포르 달러를 기록하며, 관리형 보안 서비스 제공업체(MSSP)의 이익률을 압박하고 있습니다. 각 MSSP 기업은 자동화를 활용하여 Tier-1 티켓 건수를 35% 줄였지만, 여전히 많은 기업이 시트 라이선스 가격 인상을 통해 임금 상승분을 전가하고 있습니다. 인력 부족이 지속되면서 대규모 도입이 지연되고, 가동 개시까지의 기간이 길어지며, 단기적인 수익 창출이 둔화되고 있습니다. 인재 양성 파이프라인이 대폭 확대되지 않는 한, 인재 공급 부족이 싱가포르 사이버 보안 시장이 예상된 속도로 성장하는 능력을 계속해서 제한할 것으로 보입니다.
부문 분석
2025년, 서비스 부문은 싱가포르 사이버 보안 시장 점유율의 59.60%를 차지한 것으로 평가되었으며, 이는 23억 싱가포르 달러에 달하는 관리형 보안 서비스 수익에 힘입은 것입니다. 평균 감지 시간(MTD)은 2022년 8시간에서 2024년 2시간으로 단축되어, 연중무휴 24시간 모니터링에 대한 투자가 성과를 거두고 있음을 입증했습니다. 국경을 넘는 위협 인텔리전스를 통합한 제공업체는 92%의 계약 갱신률을 달성하여, 산업 전체의 중앙값인 84%를 상회했습니다. 고객들은 보험 중개나 사고 대응에 대한 정액제 계약을 모니터링 서비스와 함께 체결하는 경향이 강해지고 있어, MSSP(관리형 보안 서비스 제공업체)에게 연금과 같은 안정적인 수익원이 되고 있습니다. 이러한 요인들로 인해 싱가포르의 사이버 보안 시장은 견실한 두 자릿수 성장을 유지하고 있습니다.
클라우드 보안은 기업의 클라우드 워크로드 도입률이 84%에 달하는 것을 배경으로, 2031년까지 연평균 성장률(CAGR) 15.52%를 기록할 전망입니다. MAS(싱가포르 금융관리청)의 규정 개정에 따라 필수 통제 목표가 8개 항목에서 11개 항목으로 확대되고 실사 주기가 엄격해졌지만, 대상 지출 규모는 확대되고 있습니다. 보안 태세 관리와 자동 복구 기능을 결합한 벤더는 현재 고객사 1곳당 매월 37건의 정책 업데이트를 수행하고 있으며, 이는 2022년 대비 3배 수준입니다. 사용량 기반 과금 방식의 가격 책정은 전자상거래 성수기의 급속한 스케일 아웃에 최적입니다. 그 결과, 싱가포르 사이버 보안 시장에서 클라우드 네이티브 솔루션은 어플라이언스의 업데이트 속도를 계속해서 앞지를 것으로 보입니다.
2025년에도 온프레미스 도입은 싱가포르 사이버 보안 시장 점유율의 54.30%를 차지했으며, 금융 부문 데이터베이스의 71%는 신뢰할 수 있는 시설에 코로케이션되어 있습니다. Tier-4의 바닥 면적은 66만 m²에 달하며, 주요 은행 및 결제 네트워크에 지연 시간이 제어된 환경을 제공합니다. 하이브리드형 포렌식 워크플로우를 통해 증거 처리 시간이 27% 단축되었으며, 규제 대상 워크로드에 대한 단계적 전환 경로의 유효성이 입증되었습니다. 이에 따라 많은 기존 기업들은 클라우드 우선형 용도를 시범 도입하는 한편, 경계 보안 하드웨어의 업데이트를 지속하고 있습니다.
클라우드 도입은 2025-2027년 계획된 300MW의 추가 하이퍼스케일 IT 부하에 힘입어 연평균 성장률(CAGR) 16.93%를 나타낼 것으로 예측됩니다. ‘그린 데이터센터’ 기준을 충족하는 사업자들은 PUE가 1.3 미만이라고 보고하고 있으며, 이를 통해 랙 내 보안 가속기에 할당할 에너지 예산을 확보하고 있습니다. CPU 초 단위로 과금되는 새로운 일괄 라이선스 요금 체계 덕분에 월별 청구액 변동이 18% 감소하여 CFO의 우려가 완화되었습니다. 프로비저닝 시간 단축으로 인해 스타트업 기업은 몇 주가 아닌 몇 시간 만에 SOC 인프라를 가동할 수 있게 됩니다. 이러한 이점들로 인해 클라우드 도입은 싱가포르 사이버 보안 시장에서 계속해서 최전선에 위치할 것으로 보입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 세분화
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, Singapore cybersecurity market size in 2026 is estimated at USD 3.07 billion, growing from 2025 value of USD 2.65 billion with 2031 projections showing USD 6.41 billion, growing at 15.86% CAGR over 2026-2031 and confirming the city-state's status as Southeast Asia's digital command center [1] Cyber Security Agency of Singapore, "Singapore Cyber Landscape 2024," csa.gov.sg .
This report Segments the Industry Into by Offering (Solutions, and Services), Deployment Mode (Cloud, and On-Premise), End-User Vertical (BFSI, Healthcare, IT and Telecom, Industrial and Defense, Manufacturing, Retail and E-Commerce, Energy and Utilities, Others), and End-User Enterprise Size (Small and Medium Enterprises (SMEs)), and Large Enterprises
Singapore Cybersecurity Market Trends and Insights
Nationwide Zero-Trust Architecture Mandates from Government
Regulators now compel every critical information-infrastructure owner to file a zero-trust roadmap, and 96% had submitted plans by November 2024. Financial institutions responded by micro-segmenting traffic, cutting unauthorized-privilege cases by 42% within one year of go-live. Budget cycles allocate up to 28% of security outlays to identity analytics, underscoring demand for context-aware access controls. Streamlined multi-agency design reviews compressed policy-approval windows to 34 days, halving historical delays and allowing vendors to accelerate revenue recognition. Together, these moves place zero-trust enforcement at the heart of every major tender, giving suppliers that support adaptive trust scoring a decisive edge.
Accelerated Digital-Bank Licences Driving Next-Gen BFSI Security Spend
Digital full-bank licensees accumulated SGD 1.8 billion in deposits by end-2024, equal to 4% of Singapore's retail savings pool. Each new entrant channelled roughly 22% of operating expenditure into cybersecurity during its first year, an intensity mirrored by incumbents whose resilience investments grew 36% to SGD 491 million in 2024. Pilot deployments of post-quantum cryptography already protect 12% of domestic interbank traffic. Competitive parity now hinges on rapid threat-intelligence ingestion and automated compliance evidence, redirecting budgets toward managed detection and response platforms rather than standalone appliances. The banking cluster's early adoption curves ripple through payments, wealth management and capital-markets systems, magnifying total addressable demand for the Singapore Cybersecurity market.
Scarce Pool of CREST-Certified Talent Inflates Service Costs
Only 530 CREST-certified professionals operated locally in 2024 against demand for 1,200, equating to a 56% gap. Median senior-analyst pay climbed 14% to SGD 117,000, compressing margins for managed security service providers. MSSPs used automation to trim Tier-1 ticket volumes by 35%, yet many still absorb wage inflation by passing through higher seat-licence prices. Persistent scarcity delays large rollouts, elongating go-live timelines and dampening short-term revenue conversion. Unless training pipelines expand materially, talent supply will continue to limit the Singapore Cybersecurity market's ability to scale at the forecast rate.
Other drivers and restraints analyzed in the detailed report include:
- SGX-Listed Firms' Mandatory Cyber-Incident Disclosure Rules
- Heightened OT-Security Demand from Tuas Mega-Port and Jurong Island Revamp
- Fragmented SME Market Still Anchored on Legacy Antivirus
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services contributed 59.60% to the Singapore Cybersecurity market share in 2025, helped by managed security service revenues of SGD 2.3 billion. Average mean-time-to-detect dropped from eight hours in 2022 to two hours in 2024, proving the return on 24/7 monitoring investments. Providers that integrate cross-border threat-intelligence achieved 92% renewal, outpacing the sector median of 84%. Clients increasingly bundle insurance broking and incident-response retainers with monitoring, creating annuity-like revenue for MSSPs. These factors sustain robust double-digit expansion for the Singapore Cybersecurity market.
Cloud security is on track for a 15.52% CAGR through 2031, riding on 84% enterprise cloud-workload penetration. Updated MAS rules expanded mandatory control objectives from eight to 11, intensifying due-diligence cycles yet enlarging addressable spend. Vendors that pair posture management with auto-remediation now execute 37 policy updates per client each month, triple 2022 volumes. Consumption-based pricing fits well with rapid scale-out during peak e-commerce seasons. As a result, cloud-native solutions will continue to outpace appliance refreshes inside the Singapore Cybersecurity market.
On-premise installations still held 54.30% of the Singapore Cybersecurity market share in 2025, with 71% of financial-sector databases co-located in trusted facilities. Tier-4 floor space reached 660,000 m2, providing large banks and payment networks with latency-controlled environments. Hybrid forensics workflows lowered evidence-processing time by 27%, validating a staged migration path for regulated workloads. Accordingly, most incumbents continue to refresh perimeter hardware even while piloting cloud-first applications.
Cloud deployments promise a 16.93% CAGR, buoyed by an extra 300 MW of hyperscale IT load planned for 2025-2027. Operators meeting the Green Data Centre standard report PUE below 1.3, releasing energy budgets for in-rack security accelerators. New bulk-licence tariffs priced per CPU-second reduced monthly invoice volatility by 18%, easing CFO concerns. Faster provisioning times allow startups to activate SOC infrastructure in hours rather than weeks. These advantages will keep cloud adoption at the forefront of the Singapore Cybersecurity market.
Complete Report Scope:
- By Offering
- Solutions
- Application Security
- Cloud Security
- Data Security
- Identity and Access Management
- Infrastructure Protection
- Integrated Risk Management
- Network Security Equipment
- Endpoint Security
- Other Services
- Services
- Professional Services
- Managed Services
- Solutions
- By Deployment Mode
- On-Premise
- Cloud
- By End-User Vertical
- BFSI
- Healthcare
- IT and Telecom
- Industrial and Defense
- Manufacturing
- Retail and E-commerce
- Energy and Utilities
- Others
- By End-User Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
List of Companies Covered in this Report:
- Ensign InfoSecurity
- ST Engineering (Digital Systems)
- Horangi Cyber Security
- Palo Alto Networks (Singapore)
- Cisco Systems (Singapore)
- IBM Security Singapore
- Check Point Software Technologies (SG)
- Fortinet Singapore
- FireEye Mandiant (Singapore)
- Trend Micro Singapore
- CrowdStrike Singapore
- Darktrace Singapore
- Splunk Singapore
- SecureAge Technology
- Quann (Subsidiary of Certis)
- Group-IB Singapore
- V-Key
- Wizlynx Pte Ltd
- InsiderSecurity
- WebOrion
- GROUP8
- Blackpanda
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Nationwide zero-trust architecture mandates from Singapore Government
- 4.2.2 Accelerated digital-bank licences driving next-gen BFSI security spend
- 4.2.3 SGX-listed firms' mandatory cyber-incident disclosure rules
- 4.2.4 Heightened OT-security demand from Tuas mega-port & Jurong Island revamp
- 4.2.5 Roll-out of 5G SA networks necessitating cloud-native security functions
- 4.2.6 R&D tax-incentives for local cybersecurity IP creation
- 4.3 Market Restraints
- 4.3.1 Scarce pool of CREST-certified talent inflates service costs
- 4.3.2 Fragmented SME market still price-anchored on legacy antivirus
- 4.3.3 Data-sovereignty clauses limiting foreign MSSP data-lake hosting
- 4.3.4 High compliance overlap (CSA CCOP vs. MAS TRM) elongates sales cycles
- 4.4 Evaluation of Critical Regulatory Framework
- 4.5 Value Chain Analysis
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Key Use Cases and Case Studies
- 4.9 Impact on Macroeconomic Factors of the Market
- 4.10 Investment Analysis
5 MARKET SEGMENTATION
- 5.1 By Offering
- 5.1.1 Solutions
- 5.1.1.1 Application Security
- 5.1.1.2 Cloud Security
- 5.1.1.3 Data Security
- 5.1.1.4 Identity and Access Management
- 5.1.1.5 Infrastructure Protection
- 5.1.1.6 Integrated Risk Management
- 5.1.1.7 Network Security Equipment
- 5.1.1.8 Endpoint Security
- 5.1.1.9 Other Services
- 5.1.2 Services
- 5.1.2.1 Professional Services
- 5.1.2.2 Managed Services
- 5.1.1 Solutions
- 5.2 By Deployment Mode
- 5.2.1 On-Premise
- 5.2.2 Cloud
- 5.3 By End-User Vertical
- 5.3.1 BFSI
- 5.3.2 Healthcare
- 5.3.3 IT and Telecom
- 5.3.4 Industrial and Defense
- 5.3.5 Manufacturing
- 5.3.6 Retail and E-commerce
- 5.3.7 Energy and Utilities
- 5.3.8 Others
- 5.4 By End-User Enterprise Size
- 5.4.1 Small and Medium Enterprises (SMEs)
- 5.4.2 Large Enterprises
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Ensign InfoSecurity
- 6.4.2 ST Engineering (Digital Systems)
- 6.4.3 Horangi Cyber Security
- 6.4.4 Palo Alto Networks (Singapore)
- 6.4.5 Cisco Systems (Singapore)
- 6.4.6 IBM Security Singapore
- 6.4.7 Check Point Software Technologies (SG)
- 6.4.8 Fortinet Singapore
- 6.4.9 FireEye Mandiant (Singapore)
- 6.4.10 Trend Micro Singapore
- 6.4.11 CrowdStrike Singapore
- 6.4.12 Darktrace Singapore
- 6.4.13 Splunk Singapore
- 6.4.14 SecureAge Technology
- 6.4.15 Quann (Subsidiary of Certis)
- 6.4.16 Group-IB Singapore
- 6.4.17 V-Key
- 6.4.18 Wizlynx Pte Ltd
- 6.4.19 InsiderSecurity
- 6.4.20 WebOrion
- 6.4.21 GROUP8
- 6.4.22 Blackpanda
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment