|
시장보고서
상품코드
2125566
말레이시아의 사이버 보안 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Malaysia Cybersecurity - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
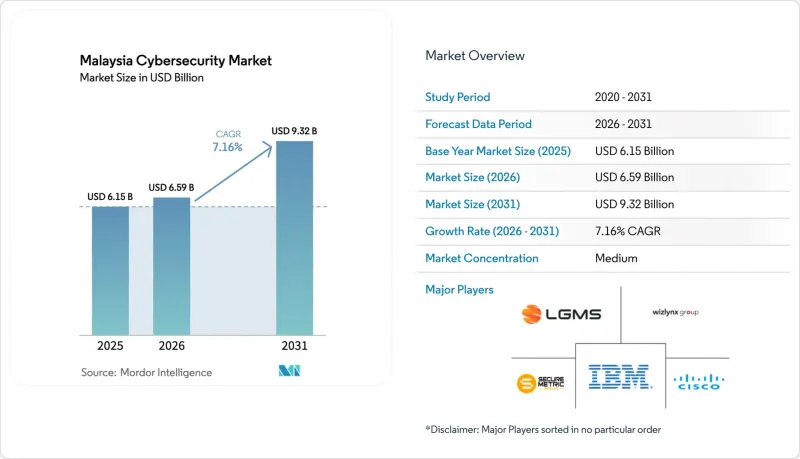
에 의하면, 말레이시아 사이버 보안 시장 규모는 2025년 61억 5,000만 달러에서 2026년에는 65억 9,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 7.16%로 성장을 지속하여, 2031년에는 93억 2,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제공 형태(솔루션(용도 보안, 클라우드 보안 등), 서비스(전문 서비스 등)), 도입 형태(클라우드, On-Premise), 최종 사용자 산업(은행, 금융서비스 및 보험(BFSI), 헬스케어,IT 및 통신, 산업·방위, 소매 및 전자상거래 등), 최종 사용자 기업 규모(대기업, 중소기업)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
말레이시아 사이버 보안 시장 동향 및 인사이트
말레이시아의 ‘클라우드 퍼스트’ 전략이 급속히 전개되면서 공공 부문의 클라우드 보안 지출이 증가하고 있습니다.
말레이시아의 ‘클라우드 퍼스트’ 전략 가속화에 따라, 정부 지출은 클라우드 액세스 보안 브로커(CASB) 및 워크로드 보호 플랫폼과 같은 클라우드 네이티브 방어 수단으로 전환되고 있습니다. 각 부처는 현재 모든 용도 마이그레이션 계획에 기밀 분류, 암호화, 지속적인 모니터링을 포함하고 있으며, 이로 인해 자문 서비스 및 관리형 서비스에 대한 기본적인 수요가 증가하고 있습니다. 공공 부문의 초기 성공 사례가 가시화됨에 따라 금융 기관 및 통신 사업자들이 유사한 아키텍처를 채택하도록 촉진되고 있으며, 이는 말레이시아 사이버 보안 시장 전체에 파급 효과를 낳고 있습니다. 시스템 통합사업자들은 책임 분담 모델을 중심으로 포트폴리오를 재설계하여 컨설팅, 도입, 관리형 감지 서비스를 단일 계약으로 통합하고 있습니다. 이러한 변화들은 종합적으로 볼 때 일시적인 급증에 그치지 않고, 관련 지출의 구조적인 증가로 이어지고 있습니다.
‘2024년 사이버 보안법’에 따른 라이선싱 제도와 NCII 필수 준수가 벤더 수요를 뒷받침
‘2024년 사이버 보안법’은 침투 테스트, 보안 운영 및 기타 주요 서비스에 대한 라이선싱을 의무화하고 있으며, 중요 인프라 운영자는 해당 부문별 실무 규범을 준수해야 합니다. 이에 따라 조직들은 규정 준수를 이사회 차원의 우선 과제로 삼고, 새로운 법적 기준에 관리 체계를 부합시키기 위해 외부 감사인을 선임하고 있습니다. 조기에 라이선스를 취득한 공급업체는 기업들이 규제상의 실수를 피하기 위해 사전 인증을 받은 파트너를 선호함에 따라 뚜렷한 판매 우위를 확보했습니다. 또한, 이 법은 사고 보고 기한을 공식적으로 규정함으로써 실시간 감지 도구 및 위협 인텔리전스 통합에 대한 수요를 촉발하고 있습니다. 이러한 변화들이 맞물리면서 지속적인 규정 준수 의무가 IT 예산에 반영됨에 따라 말레이시아 사이버 보안 시장 규모의 성장세가 유지되고 있습니다.
고급 보안 아키텍트의 심각한 부족으로 인해 프로젝트 공수와 비용이 증가하고 있습니다.
경험이 풍부한 아키텍트가 여전히 부족하여 복잡한 클라우드 전환이 정체되고 있으며, 프로젝트 기간이 37% 연장되고 인건비가 4분의 1 이상 증가하고 있습니다. 이러한 인력 부족으로 인해 대규모 변혁 계약의 입찰 가격이 상승하여 기업 예산을 압박하고 있으며, 중요한 마일스톤 달성이 지연되고 있습니다. 조직 측은 아키텍처를 MSSP에 외주하거나 지역 허브에서 전문 지식을 도입하는 방식으로 대응하고 있지만, 비자 취득까지 걸리는 긴 리드타임으로 인해 단기적인 완화에는 한계가 있습니다. 벤더의 로드맵에는 현재 설계 시간을 단축하는 로우코드 정책 엔진 및 참조 아키텍처가 포함되어 있지만, 규제 대상 워크로드의 경우 현장 감독이 여전히 필수적입니다. 따라서 인력 부족은 말레이시아 사이버 보안 시장의 연평균 성장률(CAGR)에 지속적인 걸림돌이 되고 있습니다.
부문 분석
2025년, 말레이시아 사이버 보안 시장에서 솔루션은 52.20%의 점유율을 유지했으며, 하이브리드 환경을 보호하는 네트워크 및 클라우드 보안 제품군이 성장을 주도했습니다. 그러나 기업들이 상시 이용 가능한 전문 지식을 추구하는 가운데, 서비스는 2031년까지 연평균 성장률(CAGR) 7.42%로 솔루션 부문보다 더 높은 성장세를 보일 것으로 전망됩니다. 감지 정확도 향상, 24시간 모니터링, 내장형 규정 준수 대시보드를 통해 MSSP는 전술적 공급업체가 아닌 전략적 파트너로서의 입지를 확고히 하고 있습니다. 월간 활성 자산 수를 기반으로 한 가격 모델은 중견 기업 시장 진입 장벽을 낮추고 있습니다. 현지 공급업체는 규제에 대한 전문 지식을 활용하여 ‘사이버 보안법’과 관련된 계약을 수주하는 한편, 세계 벤더는 개별 도구에서 발생하는 경보를 통합하는 오케스트레이션 플랫폼을 제공합니다. 자문, 도입, MDR 서비스의 융합을 통해 단순한 기술 재판매를 넘어선 부가가치가 창출되며, 말레이시아 사이버 보안 시장에서 서비스 주도형 성장이 확고해지고 있습니다.
하지만 엄격한 데이터 거주 요건이 부과된 조직의 경우, 솔루션 포트폴리오는 여전히 매우 중요합니다. BFSI(은행 및 금융 및 보험) 및 공공 서비스 분야의 어플라이언스 교체 주기는 방화벽, 침입 방지 시스템, 보안 이메일 게이트웨이의 수익을 뒷받침하고 있습니다. 차세대 SIEM 플랫폼은 인력 부족을 보완하기 위해 행동 분석과 자동화를 통합하여, 제품 혁신을 국가의 기술 개발 목표와 조화시키고 있습니다. 각 벤더사는 On-Premise 제어 기능과 SaaS의 가시성을 연결하기 위해 영구 라이선스와 클라우드를 통해 제공되는 분석 기능을 묶어 제공합니다. 현지 통합 업체와의 공동 제공을 통해 가치 실현까지의 시간이 단축되고 있으며, 이는 말레이시아 사이버 보안 시장의 협력적인 특성을 반영하고 있습니다.
2025년, 말레이시아 사이버 보안 시장 규모의 52.85%를 On-Premise 시스템이 차지했습니다. 이는 은행 및 공공 서비스 분야에서 레거시 워크로드와 데이터 주권에 관한 규제가 여전히 주류를 이루고 있기 때문입니다. 이러한 분야의 하드웨어 업데이트는 어플라이언스 벤더에게 안정적인 기반이 되고 있습니다. 그러나 클라우드 도입은 2031년까지 연평균 성장률(CAGR) 8.05%로 확대되며 On-Premise 업그레이드를 앞지르고 있습니다. 종량제 요금제, 지속적인 기능 출시, AI를 활용한 분석 기능 덕분에 클라우드 기반 보안 대책은 ‘디지털 퍼스트’ 전략을 추진하는 기관들에게 매력적인 선택지가 되고 있습니다. 책임 분담 체계를 통해 기업들은 유지보수 업무를 전문 공급업체에 위탁하도록 유도되고 있으며, 이는 말레이시아 사이버 보안 시장의 장기적인 도입을 뒷받침하고 있습니다.
벤더의 로드맵에는 규제 대상 고객의 우려를 해소하기 위한 말레이시아 내 데이터 로컬라이제이션 노드 설치가 포함되어 있습니다. 향후 주권형 클라우드 플랫폼의 개선을 통해 남아 있는 거부감이 줄어들 가능성은 있지만, 산업용 제어 네트워크와 관련된 하드웨어의 업데이트로 인해 On-Premise 장비 시장은 앞으로도 지속될 것으로 확실시됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 동향
JHS 26.09.11According to Mordor Intelligence, the Malaysia cybersecurity market size is expected to grow from USD 6.15 billion in 2025 to USD 6.59 billion in 2026 and is forecast to reach USD 9.32 billion by 2031 at 7.16% CAGR over 2026-2031.
This report is Segmented by Offering (Solutions [Application Security, Cloud Security, and More], Services [Professional Services, and More]), Deployment Mode (Cloud, On-Premise), End-User Industry (BFSI, Healthcare, IT and Telecom, Industrial and Defense, Retail and E-Commerce, and More), End-User Enterprise Size (Large Enterprises, Smes). The Market Forecasts are Provided in Terms of Value (USD).
Malaysia Cybersecurity Market Trends and Insights
Rapid Roll-out of Malaysia's Cloud-First Strategy Propelling Public-Sector Cloud Security Spending
Malaysia's accelerated cloud-first strategy is redirecting government spending toward cloud-native defenses such as cloud access security brokers and workload-protection platforms. Ministries now integrate classification, encryption, and continuous monitoring into every application-migration plan, lifting baseline demand for advisory and managed services. Public-sector visibility into early success stories is encouraging financial institutions and telecom carriers to adopt similar architectures, creating a multiplier effect across the Malaysia cybersecurity market. System integrators have redesigned portfolios around shared-responsibility models, bundling consulting, deployment, and managed detection under single contracts. Collectively, these changes translate to a structural uplift in addressable spending rather than a one-time spike.
Cyber Security Act 2024 Licensing and Mandatory NCII Compliance Fuelling Vendor Demand
The Cyber Security Act 2024 enforces mandatory licensing for penetration testing, security-operations, and other core services, while critical-infrastructure operators must observe sector-specific codes of practice. Organizations have responded by elevating compliance to board-level priority and retaining external auditors to align controls with the new legal baseline. Providers that secured early licences gained a measurable sales advantage because enterprises prefer pre-qualified partners to avoid regulatory missteps. The act also formalized incident-reporting timelines, spurring demand for real-time detection tools and threat-intelligence integrations. Together, these shifts embed recurring compliance obligations into IT budgets, sustaining momentum in the Malaysia cybersecurity market size.
Acute Shortage of Senior Security Architects Inflating Project Timelines and Costs
Complex cloud migrations stall because experienced architects remain scarce, extending project timelines by 37% and boosting labor costs by more than one-quarter . The scarcity inflates bids for large transformation contracts, squeezing corporate budgets and delaying key milestones. Organizations counter by outsourcing architecture to MSSPs or importing expertise from regional hubs, but long visa lead times cap near-term relief. Vendor roadmaps now include low-code policy engines and reference architectures that cut design hours, yet hands-on oversight remains indispensable for regulated workloads. Talent constraints therefore act as a persistent drag on the Malaysia cybersecurity market CAGR.
Other drivers and restraints analyzed in the detailed report include:
- Data-Centre Boom in Johor Bahru Elevating Perimeter and OT Security Investments
- 5G Coverage >= 97 % Driving Mobile Core and Edge Security Upgrades
- SME Budget Constraints Owing to Legacy CAPEX-heavy IT Footprints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions maintained 52.20% share of the Malaysia cybersecurity market in 2025, led by network and cloud-security suites that protect hybrid environments. However, services are forecast to outpace solutions at a 7.42% CAGR through 2031 as enterprises look for always-on expertise. Higher detection accuracy, round-the-clock monitoring, and built-in compliance dashboards position MSSPs as strategic partners rather than tactical suppliers. Pricing models based on monthly active assets lower entry barriers for mid-tier firms. Local providers leverage regulatory familiarity to capture contracts tied to the Cyber Security Act, while global vendors package orchestration platforms that unify alerts across point tools. Convergence of advisory, deployment, and MDR services brings value propositions beyond technology resale, solidifying service-led growth in the Malaysia cybersecurity market.
The solutions portfolio nevertheless remains critical for organizations with strict data-residency rules. Appliance refresh cycles in BFSI and utilities sustain revenue for firewall, intrusion-prevention, and secure-email gateways. New-generation SIEM platforms incorporate behavioral analytics and automation to offset talent scarcity, aligning product innovation with national skills-development goals. Vendors bundle perpetual licenses with cloud-delivered analytics to bridge on-premise controls and SaaS visibility. Co-delivery with local integrators accelerates time to value, reflecting the collaborative nature of the Malaysia cybersecurity market.
On-premise systems accounted for 52.85% of the Malaysia cybersecurity market size in 2025 because legacy workloads and data-sovereignty mandates still dominate in banking and public service. Hardware refreshes in these sectors provide a stable base for appliance vendors. Yet cloud deployments are expanding at an 8.05% CAGR through 2031, outstripping on-premise upgrades. Consumption-based pricing, continuous feature releases, and AI-driven analytics make cloud controls appealing for institutions pursuing digital-first strategies. Shared-responsibility frameworks encourage enterprises to off-load maintenance to specialized providers, supporting long-term adoption in the Malaysia cybersecurity market.
Vendor roadmaps include data-localization nodes within Malaysia to reassure regulated customers. Over time, improvements in sovereign-cloud platforms may erode the remaining resistance, but hardware refreshes tied to industrial-control networks ensure a continuing market for on-premise gear.
Complete Report Scope:
- By Offering
- Solutions
- Application Security
- Cloud Security
- Data Security
- Identity and Access Management
- Infrastructure Protection
- Integrated Risk Management
- Network Security
- End-point Security
- Services
- Professional Services
- Managed Services
- Solutions
- By Deployment Mode
- Cloud
- On-Premise
- By End-user Industry
- BFSI
- Healthcare
- IT and Telecom
- Industrial and Defense
- Retail and E-commerce
- Energy and Utilities
- Manufacturing
- Others
- By End-user Enterprise Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
List of Companies Covered in this Report:
- LGMS Berhad
- IBM Corporation
- Cisco Systems Inc.
- Securemetric Bhd
- Wizlynx Group
- Akati Sekurity
- Palo Alto Networks
- Fortinet Inc.
- Check Point Software Tech.
- Trend Micro Inc.
- Kaspersky Lab
- Nexagate Sdn Bhd
- Ishan Tech Sdn Bhd
- Capgemini SE
- Microsoft Corp.
- AVG Technologies (Gen Digital)
- ATandT Cybersecurity
- NTT Data Security
- BAE Systems AI Malaysia
- Darktrace plc
- CrowdStrike Holdings Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Market Definition and Study Assumptions
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Roll-out of Malaysia's Cloud-First Strategy Propelling Public-Sector Cloud Security Spending
- 4.2.2 Cyber Security Act 2024 Licensing and Mandatory NCII Compliance Fuelling Vendor Demand
- 4.2.3 Data-Centre Boom in Johor Bahru Elevating Perimeter and OT Security Investments
- 4.2.4 5G Coverage >= 97 % Driving Mobile Core and Edge Security Upgrades
- 4.2.5 USD 12.2 bn Economic Losses From Breaches Raising Boardroom Budgets
- 4.2.6 National Goal of 25 000 Cyber Defenders Boosting Consulting and Training Spend
- 4.3 Market Restraints
- 4.3.1 Acute Shortage of Senior Security Architects Inflating Project Timelines and Costs
- 4.3.2 SME Budget Constraints Owing to Legacy CAPEX-heavy IT Footprints
- 4.3.3 Fragmented Cross-border Data-Sovereignty Rules Slowing Cloud Migrations
- 4.3.4 Low Multi-factor-Auth Adoption Outside BFSI Heightening Residual Risk
- 4.4 Value Chain Analysis
- 4.5 Evaluation of Critical Regulatory Framework
- 4.6 Impact Assessment of Key Stakeholders
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Impact of Macro-economic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Offering
- 5.1.1 Solutions
- 5.1.1.1 Application Security
- 5.1.1.2 Cloud Security
- 5.1.1.3 Data Security
- 5.1.1.4 Identity and Access Management
- 5.1.1.5 Infrastructure Protection
- 5.1.1.6 Integrated Risk Management
- 5.1.1.7 Network Security
- 5.1.1.8 End-point Security
- 5.1.2 Services
- 5.1.2.1 Professional Services
- 5.1.2.2 Managed Services
- 5.1.1 Solutions
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-Premise
- 5.3 By End-user Industry
- 5.3.1 BFSI
- 5.3.2 Healthcare
- 5.3.3 IT and Telecom
- 5.3.4 Industrial and Defense
- 5.3.5 Retail and E-commerce
- 5.3.6 Energy and Utilities
- 5.3.7 Manufacturing
- 5.3.8 Others
- 5.4 By End-user Enterprise Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium Enterprises (SMEs)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 LGMS Berhad
- 6.4.2 IBM Corporation
- 6.4.3 Cisco Systems Inc.
- 6.4.4 Securemetric Bhd
- 6.4.5 Wizlynx Group
- 6.4.6 Akati Sekurity
- 6.4.7 Palo Alto Networks
- 6.4.8 Fortinet Inc.
- 6.4.9 Check Point Software Tech.
- 6.4.10 Trend Micro Inc.
- 6.4.11 Kaspersky Lab
- 6.4.12 Nexagate Sdn Bhd
- 6.4.13 Ishan Tech Sdn Bhd
- 6.4.14 Capgemini SE
- 6.4.15 Microsoft Corp.
- 6.4.16 AVG Technologies (Gen Digital)
- 6.4.17 ATandT Cybersecurity
- 6.4.18 NTT Data Security
- 6.4.19 BAE Systems AI Malaysia
- 6.4.20 Darktrace plc
- 6.4.21 CrowdStrike Holdings Inc.
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-space and Unmet-need Assessment