

|
시장보고서
상품코드
2125432
중동 및 아프리카의 프로그래매틱 광고 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Middle East And Africa Programmatic Advertising - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
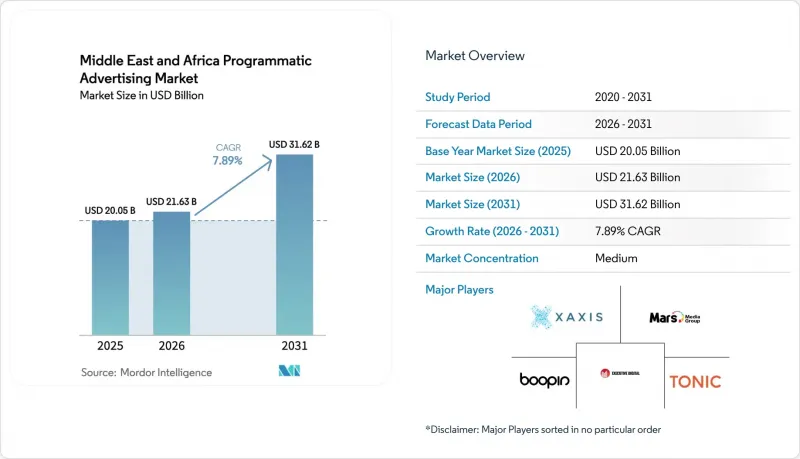
에 의하면, 중동 및 아프리카의 프로그래매틱 광고 시장 규모는 2025년 200억 5,000만 달러로 평가되었고, 2026년에는 216억 3,000만 달러로 추정되고, 2026-2031년 CAGR 7.89%로 성장을 지속할 전망이며, 2031년에는 316억 2,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 거래 플랫폼별(실시간 입찰(RTB), 프라이빗 마켓플레이스·게런티드 등), 광고 매체별(디지털 디스플레이, 모바일 디스플레이), 광고 형식별(디스플레이 배너, 온라인 동영상 등), 기업 규모별(중소기업, 대기업), 업종별(소매 및 전자상거래, BFSI 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
중동 및 아프리카의 프로그래매틱 광고 시장 동향 및 인사이트
GCC 국가에서 ‘모바일 퍼스트’ 소비자의 급증
현재 모바일 퍼스트 이용이 소비자 참여도를 좌우하고 있으며, UAE 쇼핑객의 70%가 AI 어시스턴트를 활용하고 있는데, 이는 2024년 대비 44% 증가한 수치입니다. 사용자는 하루 평균 3.5시간을 소셜 플랫폼에서 보내고 있으며, 틱톡 시청자의 67%가 인앱 구매를 할 의향이 있다고 응답했습니다. 광고주는 중동 및 아프리카의 프로그래매틱 광고 시장 전반에서 입찰 전략을 최적화하기 위한 상세한 오디언스 신호를 확보하고 있습니다. 소매업체들은 구매까지의 과정을 단축하고 장바구니 포기율을 낮추기 위해 AI 투자를 우선시하고 있습니다. UAE의 전자상거래 시장은 2028년까지 488억 AED(133억 달러)를 넘어설 것으로 예상되며, 첨단 프로그래매틱 스택에 필요한 규모는 더욱 확대되고 있습니다. InMobi와 같은 모바일 중심 DSP는 이러한 성장의 물결에 편승하기 위해 10억 달러 규모의 IPO를 목표로 하고 있습니다.
MENA 지역 방송 사업자들의 CTV/OTT 광고 인벤토리 도입 확대
UAE 거주자의 65%가 매일 컨텐츠를 스트리밍하고 있어, 브랜드 예산이 타겟팅 가능한 TV 형식으로 이동하는 추세가 가속화되고 있습니다. Noon의 IPL 스트리밍은 쇼핑 기능이 포함된 오버레이가 엔터테인먼트와 충동 구매를 어떻게 융합하고 있는지를 보여줍니다. ArabyAds와 LG Ad Solutions의 제휴를 통해 가시성 기준을 유지하면서 광고 인벤토리 공급이 확대되고 있습니다. 덴츠가 운영하는 엄선된 CTV 마켓플레이스는 오픈 익스체인지와 비교해 어텐션 점수가 18% 향상되었으며, 부정 행위를 60% 줄였습니다. 넷플릭스와 야후는 프로그래매틱 판매를 확대했고, 아마존 애즈는 로쿠(Roku)와 제휴하여 전 세계 CTV 가구의 80%에 도달함으로써 중동 및 아프리카의 프로그래매틱 광고 시장에 새로운 수요를 창출했습니다.
지역 퍼블리셔의 경우 써드파티 쿠키를 대체할 수단이 제한적입니다.
마케터의 30%는 써드파티 쿠키 폐지에 대한 준비가 여전히 미흡하여, 결과적으로 컨텍스트 타겟팅에 지나치게 의존하고 있습니다. 현지 퍼블리셔들은 퍼스트파티 데이터 도구를 구축할 자금이 부족한 경우가 많아, 그 결과 세계 플랫폼이 불균형적으로 많은 예산을 차지하는 ‘양극화된 생태계’가 형성되고 있습니다. ArabyAds와 Lotame 같은 제휴는 이러한 격차를 해소하는 것을 목표로 하고 있지만, 그 보급 상황은 제각각입니다. 분산된 데이터 개인정보 보호 체계는 규정 준수 부담을 가중시켜 소규모 퍼블리셔가 이를 관리하기 어렵게 만들고 있습니다. 이러한 불균형은 중동 및 아프리카 프로그래매틱 광고 시장공급 다양성을 제한하고 있으며, 해당 지역의 인벤토리 CPM 성장을 둔화시킬 우려가 있습니다.
부문 분석
2025년, 실시간 입찰(RTB)은 88억 8,000만 달러를 차지했으며, 중동 및 아프리카 프로그래매틱 광고 시장 규모의 44.30%에 해당했습니다. 광고주들은 경매의 효율성과 파편화된 퍼블리셔 풀 전체에 대한 도달 범위를 이유로 RTB를 선호합니다. 그러나 광고 사기에 대한 우려가 커지는 가운데, 예측 가능한 CPM으로 프리미엄 광고 공간을 확보할 수 있는 ‘자동 보장(Automated Guaranteed)’ 거래의 매력이 커지고 있습니다. ‘오토메이티드 게런티드(Automated Guaranteed)’는 연평균 성장률(CAGR) 10.34%가 예상되며, 이는 브랜드 안전성에 대한 기대감 고조와 공급 경로 최적화 프로토콜의 통합을 반영한 것입니다. The Trade Desk의 매출 25% 증가 및 Sincera 인수는 신뢰할 수 있는 경로를 명확히 하고 숨겨진 수수료를 줄이는 분석으로의 전환을 보여줍니다. PubMatic의 보고서에 따르면, 현재 노출의 55%가 최적화된 경로를 통해 이루어지고 있으며, 이는 시장 전반에 걸친 투명성 확보 노력을 강조하고 있습니다.
‘프라이빗 마켓플레이스 게런티드(Private Marketplace Guaranteed)’는 자동차, BFSI(은행 및 금융 및 보험), 럭셔리 브랜드를 대상으로 엄선된 높은 가시성의 컨텍스트를 제공합니다. 비용 관리를 추구하는 퍼포먼스 마케터에게는 예약 없이 고정 단가로 체결되는 계약이 여전히 유효합니다. 아웃브레인(Outbrain)의 10억 달러 규모 티아도스(Teaads) 인수가 네이티브 광고 및 동영상 광고 번들링을 확대하는 등, 업계 재편이 플랫폼 선택지를 재구성하고 있습니다. 따라서 광고주들은 중동 및 아프리카의 프로그래매틱 광고 시장에서 최적의 거래 구성을 결정함에 있어, 규모와 독점성의 균형을 신중하게 고려하고 있습니다.
디지털 디스플레이 광고는 여러 화면에 걸쳐 크리에이티브를 재사용하는 옴니채널 캠페인의 견인 덕분에 54.30%의 점유율을 유지했습니다. 모바일 디스플레이 광고는 스마트폰의 보급과, 노출량을 39% 줄이면서 클릭률을 10% 향상시키는 ‘그린 미디어’의 혁신에 힘입어 연평균 성장률(CAGR) 8.88%를 나타낼 것으로 예측됩니다. 통신 사업자의 데이터 통합으로 인해, 특히 쿠키 의존도가 낮은 환경에서 컨텍스트의 정확도가 향상되고 있습니다. 중동 및 아프리카의 프로그래매틱 광고 시장이 성숙해짐에 따라, 각 브랜드는 모바일 예산을 AI 주도형 커머스 여정에 맞추어 조정하고, 구매 의향이 최고조에 달하는 앱 내에서 소비자와 접점을 형성하고 있습니다. 데스크톱 디스플레이는 B2B 및 롱폼 컨텐츠에 여전히 필수적이지만, 하이브리드 근무 방식의 확산으로 사용자의 시간이 모바일 생태계로 이동함에 따라 그 점유율은 점차 감소하고 있습니다.
미디어 바이어들 사이에서는 크로스 디바이스 프리퀀시 캡핑과 통합적인 측정에 대한 수요가 높아지고 있습니다. Magnite의 CTV 수익이 23% 증가한 것은 CTV와 모바일 동영상을 융합한 단일 플랫폼에서의 실행에 대한 수요가 증가하고 있음을 보여줍니다. 또한, 미디어 비용의 급등으로 인해 마케터들은 공급 경로를 재검토하고 있으며, 지속 가능한 CPM으로 가시성 있는 인벤토리를 보장하는 SSP의 중요성이 커지고 있습니다. 그 결과, 중동 및 아프리카의 프로그래매틱 광고 시장에서 디스플레이 광고 예산 배분이 더욱 체계적으로 이루어지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Middle East and Africa programmatic advertising market size is expected to grow from USD 20.05 billion in 2025 to USD 21.63 billion in 2026 and is forecast to reach USD 31.62 billion by 2031 at 7.89% CAGR over 2026-2031.
This report is Segmented by Trading Platform (Real-Time Bidding (RTB), Private Marketplace Guaranteed, and More), Advertising Media (Digital Display, Mobile Display), Ad Format (Display Banner, Online Video, and More), Enterprise Size (SMBs, Large Enterprises), Industry Vertical (Retail and E-Commerce, BFSI, and More). The Market Forecasts are Provided in Terms of Value (USD).
Middle East And Africa Programmatic Advertising Market Trends and Insights
Explosion of Mobile-First Consumers in GCC States
Mobile-first usage now defines consumer engagement, with 70% of UAE shoppers leveraging AI assistants, a 44% jump since 2024. Users spend 3.5 hours daily on social platforms, and 67% of TikTok viewers feel motivated to make in-app purchases. Advertisers gain granular audience signals that refine bid strategies across the Middle East and Africa programmatic advertising market. Retailers are prioritizing AI budgets to shorten the path to purchase and reduce cart abandonment. The UAE e-commerce market is projected to surpass AED 48.8 billion (USD 13.3 billion) by 2028, reinforcing the scale needed for advanced programmatic stacks. Mobile-centric DSPs such as InMobi are positioning for a USD 1 billion IPO to capitalize on this uptick.
Growing Adoption of CTV/OTT Advertising Inventory by MENA Broadcasters
Sixty-five percent of UAE residents stream content daily, accelerating migration of brand budgets toward addressable TV formats. Noon's IPL streams show how shoppable overlays fuse entertainment with impulse purchases. ArabyAds' alliance with LG Ad Solutions broadens supply while maintaining viewability standards. Dentsu's curated CTV marketplace posted an 18% lift in attention scores and reduced fraud by 60% compared with open exchanges. Netflix and Yahoo expanded programmatic sales, and Amazon Ads struck a Roku pact reaching 80% of global CTV homes, pulling incremental demand into the Middle East and Africa programmatic advertising market.
Limited Third-Party Cookie Alternatives on Local Publishers
Thirty percent of marketers remain ill-prepared for cookie deprecation, leading to over-reliance on contextual targeting. Local publishers often lack the capital to build first-party data tools, creating a two-speed ecosystem where global platforms win disproportionate budgets. Partnerships such as ArabyAds-Lotame aim to close the gap, yet uptake is uneven. Fragmented data-privacy frameworks add compliance overhead that smaller publishers struggle to manage. The imbalance restricts supply diversity within the Middle East and Africa programmatic advertising market and could dampen CPM growth for regional inventory.
Other drivers and restraints analyzed in the detailed report include:
- Cross-Border E-commerce Surge Boosting First-Party Data Use in UAE and KSA
- Telco-Led Identity Graph Initiatives in Africa
- Patchy 4G/5G Coverage Outside Tier-1 African Cities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Real-Time Bidding contributed USD 8.88 billion, equating to 44.30% of the Middle East and Africa programmatic advertising market size in 2025. Advertisers favor RTB for auction efficiency and reach across fragmented publisher pools. Yet fraud concerns have heightened the appeal of Automated Guaranteed deals that lock premium slots at predictable CPMs. Automated Guaranteed is set for 10.34% CAGR, reflecting rising brand-safety expectations and the integration of supply-path optimization protocols. The Trade Desk's 25% revenue rise and Sincera acquisition demonstrate the pivot toward analytics that surface trustworthy paths and reduce hidden fees. PubMatic reports 55% of impressions now travel through optimized routes, underscoring a marketwide push for transparency.
Private Marketplace Guaranteed offers curated high-viewability contexts for auto, BFSI, and luxury brands. Unreserved Fixed-Rate deals remain relevant for performance marketers chasing cost control. Consolidation reshapes platform choices, as Outbrain's USD 1 billion Teads takeover broadens native and video bundles. Advertisers therefore weigh scale versus exclusivity in determining optimal trading mixes across the Middle East and Africa programmatic advertising market.
Digital Display retained 54.30% share led by omnichannel campaigns that repurpose creative across screens. Mobile Display is forecast to post 8.88% CAGR, propelled by smartphone adoption and green media innovations that cut emissions by 39% while boosting click-throughs by 10%. Telco data integrations deepen contextual accuracy, particularly in cookie-light environments. As the Middle East and Africa programmatic advertising market matures, brands align mobile budgets with AI-driven commerce journeys, meeting consumers in-app where purchase intent peaks. Desktop display remains vital for B2B and long-form content, yet its share continues to edge down as hybrid work pushes more user time into mobile ecosystems.
Media buyers increasingly demand cross-device frequency capping and unified measurement. Magnite's 23% CTV revenue rise signals demand for single-platform execution that blends CTV and mobile video. Media cost inflation has also nudged marketers toward supply-path pruning, elevating SSPs that guarantee viewable inventory at sustainable CPMs. The result is a more disciplined allocation of display budgets across the Middle East and Africa programmatic advertising market.
Complete Report Scope:
- By Trading Platform
- Real-Time Bidding (RTB)
- Private Marketplace Guaranteed
- Automated Guaranteed
- Unreserved Fixed-rate
- By Advertising Media
- Digital Display
- Mobile Display
- By Ad Format
- Display Banner
- Online Video
- Social Media
- CTV / OTT
- Audio (Streaming and Podcast)
- Digital-Out-of-Home (DOOH)
- Others
- By Enterprise Size
- Small and Medium Businesses (SMBs)
- Large Enterprises
- By Industry Vertical
- Retail and E-commerce
- BFSI
- Automotive
- Media and Entertainment
- Healthcare and Pharma
- Travel and Hospitality
- Telecom and IT
- Others
List of Companies Covered in this Report:
- Google LLC
- Amazon Ads (Amazon Inc.)
- Xaxis (GroupM)
- InMobi Pte Ltd
- The Trade Desk, Inc.
- Magnite, Inc.
- PubMatic, Inc.
- Adform A/S
- Criteo SA
- Mars Media Group
- Tonic International
- Hsoub
- AdFalcon
- Gamned!
- Adsterra
- MMP World Wide
- Dentsu Aegis Network MEA
- Omnicom Media Group MEA
- AdFalcon (Noor Telecom)
- Digital Turbine Inc.
- Executive Digital
- Boopin
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Explosion of Mobile-First Consumers in GCC States
- 4.2.2 Growing Adoption of CTV/OTT Advertising Inventory by MENA Broadcasters
- 4.2.3 Cross-border E-commerce Surge Boosting First-Party Data Use in UAE and KSA
- 4.2.4 Telco-led Identity Graph Initiatives in Africa (e.g., MTN, Vodacom)
- 4.2.5 Programmatic DOOH Roll-outs Around FIFA and Expo Events in MEA
- 4.2.6 AI Integration and Automation in Advertising Operations
- 4.3 Market Restraints
- 4.3.1 Limited Third-Party Cookie Alternatives on Local Publishers
- 4.3.2 Patchy 4G/5G Coverage Outside Tier-1 African Cities
- 4.3.3 Low Brand-safety Tool Penetration Elevating Fraud Risk
- 4.3.4 Fragmented Data-privacy Regulations Across MEA States
- 4.4 Regulatory Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Trading Platform
- 5.1.1 Real-Time Bidding (RTB)
- 5.1.2 Private Marketplace Guaranteed
- 5.1.3 Automated Guaranteed
- 5.1.4 Unreserved Fixed-rate
- 5.2 By Advertising Media
- 5.2.1 Digital Display
- 5.2.2 Mobile Display
- 5.3 By Ad Format
- 5.3.1 Display Banner
- 5.3.2 Online Video
- 5.3.3 Social Media
- 5.3.4 CTV / OTT
- 5.3.5 Audio (Streaming and Podcast)
- 5.3.6 Digital-Out-of-Home (DOOH)
- 5.3.7 Others
- 5.4 By Enterprise Size
- 5.4.1 Small and Medium Businesses (SMBs)
- 5.4.2 Large Enterprises
- 5.5 By Industry Vertical
- 5.5.1 Retail and E-commerce
- 5.5.2 BFSI
- 5.5.3 Automotive
- 5.5.4 Media and Entertainment
- 5.5.5 Healthcare and Pharma
- 5.5.6 Travel and Hospitality
- 5.5.7 Telecom and IT
- 5.5.8 Others
6 COMPETITIVE LANDSCAPE
- 6.1 Strategic Developments
- 6.2 Vendor Positioning Analysis
- 6.3 Company Profiles (includes Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.3.1 Google LLC
- 6.3.2 Amazon Ads (Amazon Inc.)
- 6.3.3 Xaxis (GroupM)
- 6.3.4 InMobi Pte Ltd
- 6.3.5 The Trade Desk, Inc.
- 6.3.6 Magnite, Inc.
- 6.3.7 PubMatic, Inc.
- 6.3.8 Adform A/S
- 6.3.9 Criteo SA
- 6.3.10 Mars Media Group
- 6.3.11 Tonic International
- 6.3.12 Hsoub
- 6.3.13 AdFalcon
- 6.3.14 Gamned!
- 6.3.15 Adsterra
- 6.3.16 MMP World Wide
- 6.3.17 Dentsu Aegis Network MEA
- 6.3.18 Omnicom Media Group MEA
- 6.3.19 AdFalcon (Noor Telecom)
- 6.3.20 Digital Turbine Inc.
- 6.3.21 Executive Digital
- 6.3.22 Boopin
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


