|
시장보고서
상품코드
2125642
유럽의 반도체 디바이스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Semiconductor Device - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
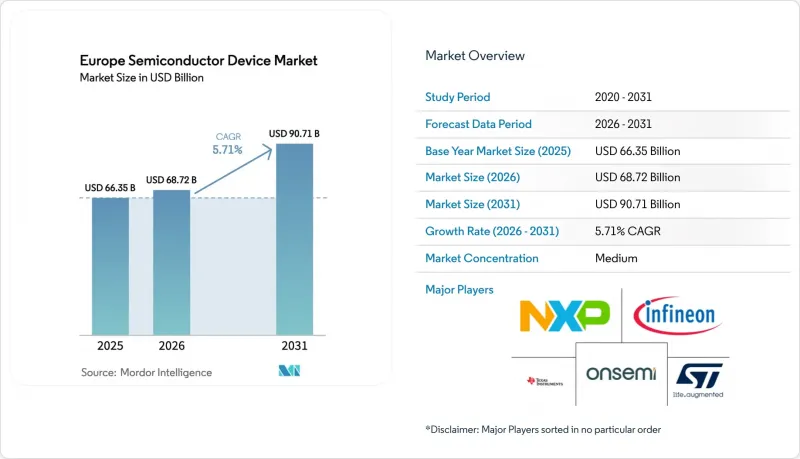
유럽의 반도체 디바이스 시장 규모는 2025년에 663억 5,000만 달러로 평가되었고, 2026년에 687억 2,000만 달러로 추정되고, 2031년까지 907억 1,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 5.71%로 성장할 전망입니다.
본 보고서는 디바이스 유형별(디스크리트 반도체, 옵토일렉트로닉스, 센서 및 MEMS, 집적회로), 비즈니스 모델별(IDM, 설계/팹리스 벤더), 최종 사용자 산업별(자동차, 통신, 소비자용, 산업용, 컴퓨팅, 데이터센터, 정부), 기술 노드별(5nm, 7nm, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
유럽의 반도체 디바이스 시장 동향 및 인사이트
유럽의 하이퍼스케일 데이터센터 내 AI 최적화 로직 IC 수요
하이퍼스케일 사업자들은 유럽 전역에서 인공지능(AI) 서버 용량을 3배로 확대하고 있으며, 재생에너지 크레딧과 고밀도 광섬유 상호 연결을 통해 총 소유 비용(TCO)을 절감할 수 있는 독일과 네덜란드에 클러스터를 집중시키고 있습니다. Nvidia가 2025년 6월에 제시한 ‘소버린 AI’ 제안에 따라 정책 입안자들은 온프레미스형 추론 가속기를 우선적으로 채택하도록 설득받았으며, 이에 따라 역외 클라우드에 대한 의존도가 낮아졌습니다. 인피니온은 실리콘 카바이드(SiC) 기반 무정전 전원 모듈이 하이퍼스케일 구축으로 확대됨에 따라, 2026 회계연도에는 AI 관련 전원 관리 사업의 매출이 15억 유로(17억 달러)에 달할 것으로 전망하고 있습니다. 유럽의 팹은 최첨단 로직이 아닌 전원 및 혼합 신호 주변 회로를 목표로 함으로써, 웨이퍼 생산량이 해외로 이전되더라도 더 높은 부가가치를 확보하고 있습니다. 이러한 동향은 데이터센터 아키텍트와 협력하여 열 관리 및 전압 조정 스택을 공동 설계하는 지역 아날로그 전문 기업들에게 설계 수주 기회를 확대하는 결과로 이어집니다.
독일과 프랑스의 SiC 디바이스 수요를 견인하는 전기차용 파워 일렉트로닉스
독일과 프랑스의 주요 자동차 제조업체들이 급속 충전과 케이블 중량 감소를 위해 실리콘 카바이드(SiC) 구동용 인버터를 필수로 하는 800볼트 배터리 전기자동차(BEV) 아키텍처를 채택함에 따라, 자동차용 반도체의 탑재량은 급증했습니다. 인피니온과 스텔란티스는 2025년에 SiC 파워 모듈 공동 개발에 관한 양해각서(MOU)를 체결하여, EU의 ‘칩 법’에 따른 인센티브에 힘입어 인피니온의 드레스덴 확장 기지에서 CoolSiC의 양산 확대를 가속화하고 있습니다. 프랑스에 본사를 둔 소이텍(Soitec)은 2025 회계연도의 재고 조정에도 불구하고, 저손실 전력 관리의 기반으로 남아 있는 ‘Power-SOI’ 기판을 공급하고 있습니다. 현재, 다년간의 웨이퍼 공급 계약에서는 희소한 SiC 생산 능력을 확보하기 위해 미가공 웨이퍼, 에피택시, 디바이스의 조달이 일괄적으로 이루어지고 있으며, 이로 인해 공급업체에 대한 의존도가 높아지고, 유럽의 반도체 디바이스 시장 전체에서 전환 비용이 상승하고 있습니다.
EU 27개국의 아날로그 및 혼합 신호 설계 엔지니어 인력 공급이 부족해지고 있습니다.
SEMI Europe이 2024년 10월에 발표한 ‘Skills for Chips’ 보고서는 2030년까지 100만 개의 반도체 관련 일자리를 채워야 한다고 경고하며, 그중에서도 아날로그 및 혼합 신호 전문가가 가장 부족하다고 지적하고 있습니다. 유럽 칩 스킬 아카데미는 10만 명의 연수생을 목표로 하고 있지만, 커리큘럼 업데이트는 극저온 CMOS 및 와이드 밴드갭 전력 모델링으로의 급속한 전환을 따라가지 못하고 있습니다. 독일의 자동차 부품 공급업체들은 시니어 아날로그 엔지니어 채용 리드타임이 18개월에 달한다고 지적하며, 지역 외의 계약 설계 회사에 의존할 수밖에 없는 실정입니다. 이러한 인력 부족으로 인해 인수 프리미엄이 부풀어 오르고 있으며, 그 일례로 ST 마이크로일렉트로닉스가 NXP의 MEMS 부문을 9억 5,000만 달러에 인수한 배경에는 200명의 센서 설계 엔지니어를 확보하려는 목적도 일부 있었습니다. 인재 양성이 가속화되지 않을 경우, 팹의 생산 확대는 설비 도입이 아닌 IP 검증 주기에 의해 병목 현상이 발생할 가능성이 있습니다.
부문 분석
2025년, 집적회로(IC)는 자동차 차체 제어, 산업용 PLC, 데이터센터의 전압 조정 분야에서 확고한 설계 채택에 힘입어 유럽 반도체 디바이스 시장 점유율의 61.72%를 차지했습니다. ST마이크로일렉트로닉스가 2025년 11월 18nm 공정으로 출시한 STM32V8 마이크로컨트롤러 제품군은 첨단 운전자 보조 시스템(ADAS) 및 전기차(EV)의 존 컨트롤러를 대상으로 합니다. 광전자 분야는 ams-OSRAM이 2025년에 발표한 2D 직접 타임 오브 플라이트(ToF) 센싱 관련 50억 유로(56억 5,000만 달러) 규모의 설계 채택 발표에 힘입어 10%대 중반의 점유율을 유지했습니다. 디스크리트 파워 디바이스 분야에서는 800볼트급 배터리식 전기차 플랫폼이 확대됨에 따라 실리콘 IGBT에서 실리콘 카바이드(SiC) MOSFET로의 전환이 지속되었습니다.
센서 및 마이크로 전자 기계 시스템(MEMS)은 연평균 성장률(CAGR) 6.11%를 나타낼 것으로 예측되며, 이는 장치 분류 중 가장 높은 성장률입니다. Melexis는 자기 위치 센서 및 전류 센서 수요 증가에 힘입어 2025년 3분기에 2억 2,220만 유로(2억 5,110만 달러)의 매출을 기록했습니다. 프라운호퍼 IMS는 2025년 12월 디지털 실리콘 광전자 증배관의 출하 대수가 100만 대를 돌파하며, 연구 기관에서 제조 공장으로의 기술 이전의 유효성을 입증했습니다. 집중형 차량 아키텍처가 보급됨에 따라 분산형 센싱이 주요 데이터 소스가 되고 있으며, 이것이 센서 관련 유럽 반도체 디바이스 시장 규모가 로직 및 메모리 하위 부문보다 빠르게 확대되고 있는 이유를 설명해 줍니다.
2025년 매출의 67.33%를 IDM(통합 디바이스 제조업체)이 차지했습니다. EU의 ‘칩 법’에 따른 보조금을 배경으로 한 인피니언의 드레스덴 거점 확장은 IDM 모델에 내재된 자체 생산의 우위를 부각시키고 있습니다. ON 세미컨덕터의 체코 거점은 유럽 자동차 제조업체를 위한 이미지 센서 및 SiC 다이오드 수요에 대응하고 있으며, 2025년 3분기 기업 매출 17억 6,000만 달러에 기여하고 있습니다.
하지만 X-FAB과 세계 파운드리(GlobalFoundries)가 파운드리 포털을 개설하고, 특정 용도용 집적회로(ASIC)의 테이프아웃이 대중화됨에 따라, 설계 및 팹리스 벤더는 연평균 성장률(CAGR) 5.89%로 성장할 전망입니다. X-FAB의 2025년 3분기 매출은 소비자용 최종 시장이 부진함에도 불구하고 1억 6,640만 달러에 달했으며, 이는 자동차 및 산업용 프로토타입 수요가 지속되고 있음을 보여줍니다. 유럽의 반도체 디바이스 업계에서는 하이브리드 전략이 전개되고 있습니다. 르네사스가 2024년에 설계 자동화 기업 알티움(Altium)을 인수한 것은 마이크로컨트롤러 공급업체들의 수직 통합 움직임을 보여주는 한편, 팹리스 스타트업들은 공급이逼迫하는 주기에서 이익률을 지키기 위해 향후 생산 능력에 관한 계약을 협상하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Europe semiconductor device market size is projected to be USD 66.35 billion in 2025, USD 68.72 billion in 2026, and USD 90.71 billion by 2031, growing at a CAGR of 5.71% from 2026 to 2031.
This report is Segmented by Device Type (Discrete Semiconductors, Optoelectronics, Sensors and MEMS, and Integrated Circuits), Business Model (IDM, and Design/Fabless Vendor), End-User Industry (Automotive, Communication, Consumer, Industrial, Computing, Data Center, and Government), Technology Node (5 Nm, 7 Nm, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Europe Semiconductor Device Market Trends and Insights
AI-Optimized Logic IC Demand From European Hyperscale Datacenters
Hyperscale operators are tripling artificial-intelligence server capacity across Europe, consolidating clusters in Germany and the Netherlands where renewable-energy credits and dense fiber interconnects reduce total cost of ownership. Nvidia's June 2025 "sovereign AI" pitch persuaded policymakers to prioritize on-premise inference accelerators, reducing dependence on extra-regional clouds. Infineon expects AI-related power-management revenue to reach EUR 1.5 billion (USD 1.7 billion) in fiscal 2026 as silicon-carbide uninterrupted-power-supply modules scale to hyperscale deployments. By targeting the power and mixed-signal periphery rather than leading-edge logic, European fabs secure higher value capture even when wafer volumes migrate offshore. This dynamic also enlarges design-win opportunities for regional analog specialists that co-engineer thermal and voltage-regulation stacks with datacenter architects.
Electric-Vehicle Power Electronics Pulling SiC Devices in Germany and France
Automotive semiconductor content rose sharply after major German and French brands adopted 800-volt battery-electric architectures that mandate silicon-carbide traction inverters for fast-charging and reduced cable mass. Infineon and Stellantis signed a memorandum of understanding in 2025 to co-develop SiC power modules, accelerating CoolSiC ramp-up at Infineon's Dresden expansion backed by EU Chips Act incentives. France-based Soitec supplies Power-SOI substrates that remain foundational for low-loss power management despite fiscal-2025 inventory corrections. Multi-year wafer-supply agreements now bundle raw-wafer, epitaxy, and device procurement in a bid to secure scarce SiC capacity, tightening supplier lock-in and raising switching costs across the Europe semiconductor device market.
Tight EU27 Talent Pipeline for Analog and Mixed-Signal Design Engineers
SEMI Europe's October 2024 "Skills for Chips" report warned that 1 million semiconductor jobs must be filled by 2030, with analog and mixed-signal specialists in shortest supply. Although the European Chips Skills Academy targets 100,000 trainees, the curriculum refresh lags rapid shifts toward cryogenic CMOS and wide-bandgap power modeling. German automotive suppliers cite 18-month hiring lead times for senior analog engineers, compelling reliance on contract design houses outside the region. The scarcity inflates acquisition premiums, exemplified by STMicroelectronics paying USD 950 million for NXP's MEMS unit partly to secure 200 sensor-design engineers. Absent accelerated workforce development, fab ramps may be bottlenecked by IP validation cycles rather than equipment installations.
Other drivers and restraints analyzed in the detailed report include:
- Rapid 5G SA Roll-outs Elevating RF Front-End Module Content per Smartphone
- EU Chips Act-Funded 300 mm Fab Expansions, Lowering Local Sourcing Risk
- Capital-Intensity Barrier For New SiC And GaN Substrate Lines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Integrated circuits held 61.72% of Europe semiconductor device market share in 2025, supported by entrenched design wins in automotive body control, industrial PLCs, and datacenter voltage regulation. STMicroelectronics' STM32V8 microcontroller family, launched in November 2025 on an 18 nm process, targets advanced driver-assistance and electric-vehicle zone controllers. Optoelectronics maintained a mid-teens slice, buoyed by ams-OSRAM's EUR 5 billion (USD 5.65 billion) in 2025 design-win announcements for 2D direct time-of-flight sensing. Discrete power devices continued migrating from silicon IGBTs to silicon-carbide MOSFETs as 800-volt battery-electric platforms scale.
Sensors and microelectromechanical systems are projected to grow at a 6.11% CAGR, the fastest among device classes. Melexis posted EUR 222.2 million (USD 251.1 million) in Q3-2025 revenue, driven by rising demand for magnetic-position and current sensors. Fraunhofer IMS crossed the 1-million-unit mark for its digital silicon-photomultiplier in December 2025, validating research-institute-to-fab transfer pathways. As centralized vehicle architectures proliferate, distributed sensing becomes the primary data source, explaining why the Europe semiconductor device market size attached to sensor content is expanding faster than logic or memory subsectors.
Integrated device manufacturers controlled 67.33% of 2025 revenues. Infineon's Dresden expansion, backed by EU Chips Act grants, underscores the sovereign-manufacturing advantage inherent in the IDM model. ON Semiconductor's Czech site serves image-sensor and SiC-diode demand for European automakers, contributing to USD 1.76 billion Q3-2025 corporate revenue.
Design and fabless vendors will nonetheless expand at a 5.89% CAGR as X-FAB and GlobalFoundries open foundry portals democratize application-specific integrated circuit tape-outs. X-FAB's Q3-2025 revenue reached USD 166.4 million despite soft consumer end markets, a testament to sustained automotive and industrial prototype demand. The European semiconductor device industry is witnessing hybrid strategies: Renesas' 2024 acquisition of design-automation firm Altium illustrates vertical integration moves by microcontroller suppliers, while fabless start-ups negotiate forward-capacity contracts to protect margins in tight allocation cycles.
Complete Report Scope:
- By Device Type
- Discrete Semiconductors
- Diodes
- Transistors
- Power Transistors
- Rectifier and Thyristor
- Other Discrete Semiconductors
- Optoelectronics
- Light-Emitting Diodes (LEDs)
- Laser Diodes
- Image Sensors
- Optocouplers
- Other Optoelectronics
- Sensors and MEMS
- Pressure
- Magnetic Field
- Actuators
- Acceleration and Yaw Rate
- Other Sensors and MEMS
- Integrated Circuits
- By IC Type
- Analog
- Micro
- Microprocessors (MPU)
- Microcontrollers (MCU)
- Digital Signal Processors
- Logic
- Memory
- By IC Type
- Discrete Semiconductors
- By Business Model
- Integrated Device Manufacturer (IDM)
- Design / Fabless Vendor
- By End-user Industry
- Automotive
- Communication (Wired and Wireless)
- Consumer
- Industrial
- Computing / Data Storage
- Data Center
- Artificial Intelligence
- Government
- By Technology Node
- Less than or Equal to 3nm
- 5 nm
- 7 nm
- 16 nm
- Less than or Equal to 28nm
- By Country
- Germany
- United Kingdom
- France
- Italy
- Netherlands
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- STMicroelectronics N.V.
- Infineon Technologies AG
- NXP Semiconductors N.V.
- ON Semiconductor Corporation
- Texas Instruments Incorporated
- Analog Devices, Inc.
- Intel Corporation
- Advanced Micro Devices, Inc.
- Microchip Technology Incorporated
- Renesas Electronics Corporation
- Micron Technology, Inc.
- SK hynix Inc.
- Samsung Electronics Co., Ltd.
- Wolfspeed, Inc.
- Melexis N.V.
- Elmos Semiconductor SE
- ams-OSRAM AG
- GlobalFoundries Inc.
- Taiwan Semiconductor Manufacturing Company Limited
- X-FAB Silicon Foundries SE
- ROHM Co., Ltd.
- Soitec S.A.
- Semikron Danfoss GmbH & Co. KG
- ASM International N.V.
- IQE plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-Optimised Logic IC Demand from European Hyperscale Data Centres
- 4.2.2 Electric-Vehicle Power Electronics Pulling SiC Devices in Germany and France
- 4.2.3 Rapid 5G SA Roll-outs Elevating RF Front-End Module Content per Smartphone
- 4.2.4 EU Chips Act- Funded 300 mm Fab Expansions Lowering Local Sourcing Risk
- 4.2.5 Quantum-Computing Pilot Lines Spurring Cryogenic CMOS Controller Demand in Finland and Netherlands
- 4.2.6 Silicon Photomultiplier Adoption in Medical Imaging Start-ups Accelerating Niche Sensor Volumes
- 4.3 Market Restraints
- 4.3.1 Tight EU27 Talent Pipeline for Analog and Mixed-Signal Design Engineers
- 4.3.2 Capital-Intensity Barrier for New SiC and GaN Substrate Lines
- 4.3.3 PFAS Phase-Out under REACH Raising Dielectric Material Re-qualification Costs
- 4.3.4 Fragmented Sub-200 mm Foundry Ecosystem Limiting IoT Prototyping Scalability
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Device Type
- 5.1.1 Discrete Semiconductors
- 5.1.1.1 Diodes
- 5.1.1.2 Transistors
- 5.1.1.3 Power Transistors
- 5.1.1.4 Rectifier and Thyristor
- 5.1.1.5 Other Discrete Semiconductors
- 5.1.2 Optoelectronics
- 5.1.2.1 Light-Emitting Diodes (LEDs)
- 5.1.2.2 Laser Diodes
- 5.1.2.3 Image Sensors
- 5.1.2.4 Optocouplers
- 5.1.2.5 Other Optoelectronics
- 5.1.3 Sensors and MEMS
- 5.1.3.1 Pressure
- 5.1.3.2 Magnetic Field
- 5.1.3.3 Actuators
- 5.1.3.4 Acceleration and Yaw Rate
- 5.1.3.5 Other Sensors and MEMS
- 5.1.4 Integrated Circuits
- 5.1.4.1 By IC Type
- 5.1.4.1.1 Analog
- 5.1.4.1.2 Micro
- 5.1.4.1.2.1 Microprocessors (MPU)
- 5.1.4.1.2.2 Microcontrollers (MCU)
- 5.1.4.1.2.3 Digital Signal Processors
- 5.1.4.1.3 Logic
- 5.1.4.1.4 Memory
- 5.1.4.1 By IC Type
- 5.1.1 Discrete Semiconductors
- 5.2 By Business Model
- 5.2.1 Integrated Device Manufacturer (IDM)
- 5.2.2 Design / Fabless Vendor
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Communication (Wired and Wireless)
- 5.3.3 Consumer
- 5.3.4 Industrial
- 5.3.5 Computing / Data Storage
- 5.3.6 Data Center
- 5.3.7 Artificial Intelligence
- 5.3.8 Government
- 5.4 By Technology Node
- 5.4.1 Less than or Equal to 3nm
- 5.4.2 5 nm
- 5.4.3 7 nm
- 5.4.4 16 nm
- 5.4.5 Less than or Equal to 28nm
- 5.5 By Country
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Netherlands
- 5.5.6 Spain
- 5.5.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 STMicroelectronics N.V.
- 6.4.2 Infineon Technologies AG
- 6.4.3 NXP Semiconductors N.V.
- 6.4.4 ON Semiconductor Corporation
- 6.4.5 Texas Instruments Incorporated
- 6.4.6 Analog Devices, Inc.
- 6.4.7 Intel Corporation
- 6.4.8 Advanced Micro Devices, Inc.
- 6.4.9 Microchip Technology Incorporated
- 6.4.10 Renesas Electronics Corporation
- 6.4.11 Micron Technology, Inc.
- 6.4.12 SK hynix Inc.
- 6.4.13 Samsung Electronics Co., Ltd.
- 6.4.14 Wolfspeed, Inc.
- 6.4.15 Melexis N.V.
- 6.4.16 Elmos Semiconductor SE
- 6.4.17 ams-OSRAM AG
- 6.4.18 GlobalFoundries Inc.
- 6.4.19 Taiwan Semiconductor Manufacturing Company Limited
- 6.4.20 X-FAB Silicon Foundries SE
- 6.4.21 ROHM Co., Ltd.
- 6.4.22 Soitec S.A.
- 6.4.23 Semikron Danfoss GmbH & Co. KG
- 6.4.24 ASM International N.V.
- 6.4.25 IQE plc
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment