|
시장보고서
상품코드
2125726
천장 조명 및 샹들리에 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Ceiling Lights & Chandeliers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 천장 조명 및 샹들리에 시장 규모는 2025년에 400억 5,000만 달러로 평가되었고, 2026년 421억 8,000만 달러에서 2031년까지 546억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.33%를 나타낼 전망입니다.
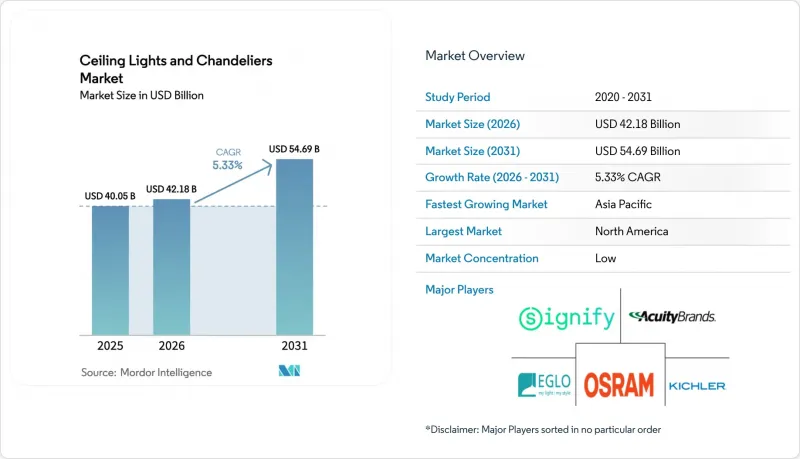
본 보고서는 제품 유형별(천장 조명, 샹들리에), 조명 기술별(LED, 형광등, 기타), 소재별(금속, 크리스탈, 기타), 최종 사용자별(주거용, 상업용), 유통 채널별(오프라인 쇼룸·전문점, DIY·홈센터 체인, 기타), 지역별(북미, 유럽, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 천장 조명 및 샹들리에 시장 동향과 인사이트
주거 공간의 미관 및 인테리어 디자인에 대한 수요 증가
조명은 순수하게 기능적인 제품에서 공간을 특징짓는 디자인 요소로 변화하고 있으며, 주택 소유자들은 연출 효과와 효율성을 모두 갖춘 인상적인 조명 기구로 기본적인 조명 기구를 교체하고 있습니다. 주거용 조명은 여전히 가정의 전력 소비량의 약 10%를 차지하고 있으며, ENERGY STAR에는 현재 디자인성과 저전력 소비를 겸비한 6만 개 이상의 인증 모델이 등록되어 있습니다. 미국인들은 시간의 90% 가까이를 실내에서 보내기 때문에 시각 환경 개선은 주택 리모델링 프로젝트 상위 5위 안에 항상 포함됩니다. 2024년에는 미국에서 약 370만 가구가 조명을 업그레이드할 것으로 예상되며, 이는 꾸준한 교체 수요를 뒷받침하고 있습니다.
도시화와 주택 건설 증가
아시아태평양, 중동, 라틴아메리카의 급속한 도시 성장이 천장 장착형 조명의 신축 수요를 견인하고 있습니다. 유엔 데이터에 따르면, 2024년에는 세계 인구의 56.2%가 도시 지역에 거주하고 있으며, 이 비율은 2050년까지 68.4%에 달할 전망입니다. 각국에서는 약 25억 호의 신규 주택이 필요하며, 각 세대마다 여러 개의 조명 기구가 필요하게 됩니다. 미국에서는 2024년 민간 주택 착공 건수가 연율 환산으로 156만 호에 달하고, 7.2% 증가할 것으로 예상되며, 이는 조명 기구 판매를 직접적으로 견인하고 있습니다.
고급·디자이너 조명 기구의 높은 가격
고급스러운 샹들리에는 표준 이식형 조명의 몇 배에 달하는 가격인 경우도 있어, 가격에 민감한 부문에서의 보급을 제한하고 있습니다. 내구재에 대한 가계 지출은 일정 임계치를 넘으면 탄력성이 매우 높아지지만, 2024년 이후 관세로 인해 수입 부품의 입고 비용이 최대 25% 상승했습니다. 미국의 고소득 가구는 중소득 가구에 비해 주택 가구에 대한 지출이 4.7배 더 많으며, 이는 해당 판매량의 상한선이 되는 소득 격차를 여실히 보여줍니다.
부문 분석
2025년 매출액 중 천장 조명이 62.20%를 차지했으며, 거실, 주방, 복도, 상업시설에서 여전히 표준 선택지로 자리 잡고 있습니다. 미국 평균 가정에는 12.3개의 조명 기구가 설치되어 있으며, 그중 3분의 2는 천장 장착형입니다. 임베디드형과 표면 설치형의 출하량이 가장 많은 반면, 펜던트 조명은 더 빠른 성장세를 보이고 있으며, 이는 소비자들이 독자적인 미학을 추구하는 경향을 반영합니다. 샹들리에 시장 점유율은 작지만, 식당이나 호텔 로비에서의 설치가 증가하고 있는 것을 배경으로 연평균 성장률(CAGR) 6.12%를 나타낼 것으로 예측됩니다. 2024년에는 장식용 조명 기구의 수입이 18.3% 증가할 것으로 예상되며, 이는 기존 카테고리가 성숙기에 접어들었음에도 불구하고 독창적인 디자인에 대한 수요가 여전히 견고함을 입증합니다.
디자인에 대한 기대와 스마트 홈 기능이 융합됨에 따라 천장 조명 및 샹들리에 시장에는 2차적인 파급 효과가 확산되고 있습니다. 주요 샹들리에 제조업체들은 현재, 그동안 실용적인 조명 기구에 국한되었던 기능인 블루투스 메쉬 드라이버와 조광 가능한 백색 LED의 탑재를 실험하고 있습니다. 2024년에는 적어도 1개의 샹들리에를 갖춘 미국 신축 단독주택의 비율이 68%에 달하여, 2020년 대비 12포인트 상승했습니다. 이러한 변화는 장식적인 형태와 네트워크화된 지능이 공존하는 미래를 예고하는 것으로, 소비자의 선택 폭을 넓히고 평균 판매 가격 상승을 뒷받침하고 있습니다.
LED는 2025년에 매출의 53.51%를 차지한 것으로 평가되었으며, 2030년까지 시장 침투율이 80%를 넘어설 전망으로, 형광등이나 할로겐등과 같은 기존 조명을 대체하게 될 것입니다. 백열등에 비해 90%에 가까운 효율 향상은 주택 소유자와 시설 관리자 모두에게 매력적인 투자 회수를 가져다줍니다. 특히 중요한 점은 스마트 LED와 커넥티드 LED가 중기적으로 연평균 성장률(CAGR) 10.95%로 성장을 지속하고, 있어, 천장 조명 및 샹들리에 시장이 IoT로의 진입점으로서의 입지를 강화하고 있다는 것입니다. 네트워크 지원 드라이버, 내장 센서, 펌웨어 업그레이드를 통해 조명 기구는 재실 상황 분석 및 자산 관리를 위한 데이터 포인트로 변모하고 있습니다.
형광등은 특정 상업시설이나 공공시설에서의 용도에서 여전히 존재감을 유지하고 있지만, LED로 교체할 경우 일반적으로 2년 이하의 회수 기간 내에 매력적인 투자 수익률(ROI)을 가져다주기 때문에 그 시장 점유율은 계속 하락하고 있습니다.
지역별 분석
북미는 2025년에 시장 점유율의 34.50%를 차지했으며, 천장 조명 및 샹들리에 시장의 매출에서 가장 큰 점유율을 유지하고 있습니다. 2024년, 미국 가구는 주택 개보수에 4,570억 달러를 지출했으며, 그 큰 수혜를 입은 분야가 바로 조명 업그레이드였습니다. 전미에는 약 21억 개의 천장 조명 기구가 설치되어 있으며, 연간 교체율은 8.3% 전후입니다. 캐나다의 정책은 에너지 성능을 중시하고 있어, LED의 점유율을 미국 수준을 웃도는 수준으로 끌어올리고 있습니다. 멕시코의 국내 공장에서는 수출업체들이 아시아 이외의 지역으로의 다각화를 추진하는 가운데, 2024년에 조명 제품 생산량이 12.7% 증가했습니다.
아시아태평양은 가장 성장세가 두드러지는 지역으로, 2031년까지 연평균 성장률(CAGR) 8.78%가 예상됩니다. 중국에서는 2020-2024년 도시 거주 인구가 1억 600만 명 증가하면서 주거용 조명 기구 수요가 확대되었습니다. 인도에서는 2030년까지 2,500만 가구의 신규 주택이 필요할 것으로 예상되며, 조명 비용은 일반적으로 건설 예산의 2.7%를 차지합니다. 일본에서는 리모델링 주기가 가속화됨에 따라 2024년 국내 LED 생산량이 15.3% 증가했습니다. 한국에서는 엄격한 에너지 규제를 배경으로 2024년 LED 보급률이 78%에 달했습니다. 싱가포르의 ‘그린마크’ 프로그램은 동남아시아 개발업자들에게 고효율 조명 기구의 도입을 촉진하고 있습니다.
유럽은 디자인적 전통과 엄격한 규제로 인해 여전히 큰 영향력을 유지하고 있습니다. ‘에코디자인 지침’에 따라 2024년까지 대부분의 할로겐 램프가 완전히 폐지되었으며, 판매는 고효율 LED에 집중되고 있습니다. 유로스타트(Eurostat) 데이터에 따르면, 각 가구는 조명 제품과 전력에 연간 213유로(187.21달러)를 지출하고 있으며, 일조 시간의 지역적 차이가 지역별 차이를 초래하고 있습니다. 영국에서는 상업용 전력 부하의 18%를 조명이 차지하는 것으로 알려져 있으며, 이것이 개보수 프로젝트를 촉진하고 있습니다. 독일에서는 공급업체들이 프리미엄 제품 라인으로의 전환을 추진한 결과, 2024년 조명 기구 생산량이 3.7% 증가했습니다. 프랑스에서는 엄격한 광공해 규제로 인해 광속 제어 광학 시스템에 대한 수요가 증가하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJYAccording to Mordor Intelligence, the ceiling lights & chandeliers market size was valued at USD 40.05 billion in 2025 and estimated to grow from USD 42.18 billion in 2026 to reach USD 54.69 billion by 2031, at a CAGR of 5.33% during the forecast period (2026-2031).
This report Segments Into Product Type (Ceiling Lights, Chandeliers), Lighting Technology (LED, Fluorescent, and More), Material (Metal, Crystal and More), End-User (Residential, Commercial), Distribution Channel (Offline/Showrooms and Specialty Stores, DIY and Home-Improvement Chains and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Ceiling Lights & Chandeliers Market Trends and Insights
Rising home aesthetics and interior design
Lighting has shifted from a purely functional commodity to a defining design element, encouraging homeowners to replace basic fixtures with statement pieces that deliver both ambience and efficiency. Residential lighting still consumes roughly 10% of household electricity, and ENERGY STAR now lists more than 60,000 certified models that blend design and low wattage . Americans spend close to 90% of their time indoors, so improved visual environments consistently rank among the top five home improvement projects. Around 3.7 million United States households upgraded lighting in 2024, underlining steady replacement demand.
Urbanization and Rising Residential Construction
Rapid city growth across Asia-Pacific, the Middle East, and Latin America fuels new-build demand for ceiling-mounted illumination. United Nations data shows 56.2% of the global population lived in urban areas in 2024, with the share tracking toward 68.4% by 2050. Countries will need roughly 2.5 billion new housing units, each requiring multiple fixtures. In the United States, privately owned housing starts hit an annualized 1.56 million in 2024, a 7.2% rise that directly lifts fixture sales.
High Cost of Premium and Fixtures Designer
Statement chandeliers can cost several multiples of standard flush mounts, limiting penetration in price-sensitive segments. Household spending on durable goods is highly elastic above certain thresholds, and tariffs have lifted landed costs for imported components by up to 25% since 2024. Top-income United States households spend 4.7 times more on home furnishings than middle-income peers, illustrating the income asymmetry that caps addressable volume.
Other drivers and restraints analyzed in the detailed report include:
- Technological Advances in Smart and Energy-Efficient Lighting
- Growth in Hospitality and Commercial Real Estate Sectors
- Energy Regulations and Compliance Standards
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ceiling lights represented 62.20% of 2025 revenue and remain the default choice across living rooms, kitchens, corridors, and commercial settings. Average United States homes host 12.3 fixtures, two-thirds of which are ceiling mounted . Flush and surface mounts ship in the highest volumes, but pendants show faster growth, reflecting consumer interest in bespoke aesthetics. Chandeliers occupy a smaller slice yet are projected to post a 6.12% CAGR, bolstered by rising installations in dining rooms and hotel lobbies. Imports of decorative fixtures climbed 18.3% in 2024, confirming a resilient appetite for standout designs even when traditional categories mature.
Second-order effects ripple through the ceiling lights & chandeliers market as design expectations converge with smart-home functionality. Leading chandelier makers now experiment with embedded Bluetooth-mesh drivers and tunable-white LEDs, features previously reserved for utilitarian luminaires. New United States single-family builds featuring at least one chandelier rose to 68% in 2024, up 12 points from 2020. These shifts foreshadow a future where decorative form and networked intelligence coexist, widening consumer choice and nudging average selling prices higher.
LED captured 53.51% of sales in 2025 and is on track to exceed 80% penetration by 2030, displacing fluorescent and halogen incumbents. Efficacy gains of nearly 90% over incandescent lamps deliver compelling paybacks for both homeowners and facility managers. Crucially, smart or connected LEDs register an 10.95% medium-term CAGR, reinforcing the ceiling lights & chandeliers market as an IoT on-ramp. Network-ready drivers, integrated sensors, and firmware upgrades transform fixtures into data points for occupancy analytics and asset management.
Fluorescent lighting maintains a presence in certain commercial and institutional applications, though its market share continues to decline as LED retrofits offer compelling returns on investment with payback periods typically under two years.
Complete Report Scope:
- By Product Type
- Ceiling Lights
- Flush/Surface Mount
- Semi-Flush
- Recessed Downlights
- Pendant & Drop Lights
- Chandeliers
- Traditional
- Transitional
- Modern / Contemporary
- Ceiling Lights
- By Lighting Technology
- LED
- Fluorescent
- Incandescent & Halogen
- HID & Others
- By Material
- Metal
- Crystal
- Glass
- Wood & Natural Materials
- Plastics & Composites
- By End-user
- Residential
- Commercial
- Offices and Co-Working Spaces
- Hospitality (Hotels, Resorts, Restaurants)
- Retail & Shopping Malls
- Healthcare Facilities
- Educational Institutions
- Industrial
- By Distribution Channel
- Offline/Showrooms & Specialty Stores
- DIY and Home-Improvement Chains
- Online/E-commerce Platforms
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Middle East And Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East And Africa
- North America
Geography Analysis
North America retains the greatest chunk of the ceiling lights & chandeliers market revenue with 34.50% of market share in 2025. United States households spent USD 457 billion on improvements in 2024, with lighting upgrades a large beneficiary . Around 2.1 billion ceiling fixtures are installed nationally, and replacement rates sit near 8.3% each year. Canadian policy leans heavily on energy performance, advancing LED share beyond United States levels. Mexico's domestic factories saw lighting output rise 12.7% in 2024 as exporters diversified away from Asia.
Asia-Pacific is the fastest-growing territory, set for 8.78% CAGR to 2031. China added 106 million new urban residents between 2020-2024, swelling demand for residential fixtures. India needs 25 million additional homes by 2030, and lighting typically equals 2.7% of construction budgets. Japan's domestic LED output climbed 15.3% in 2024 as renovation cycles accelerated. Korea reached 78% LED penetration in 2024 on the back of stringent energy codes. Singapore's Green Mark program pushes Southeast Asian developers toward efficient luminaires.
Europe remains influential owing to its design heritage and tight regulation. The Ecodesign Directive fully phased out most halogen lamps by 2024, focusing sales on high-efficacy LEDs. Eurostat shows households spend EUR 213 (USD 187.21) yearly on lighting products and power, with daylight variability shaping regional differences. The UK cites lighting as 18% of commercial electricity load, spurring retrofit projects. Germany's fixture manufacturing rose 3.7% in 2024 as suppliers pivoted to premium lines. France's strict light-pollution rules strengthen demand for controlled-beam optics.
- Signify (Philips Lighting)
- OSRAM GmbH
- Eglo Leuchten GmbH
- Kichler Lighting LLC
- Hubbell Lighting Inc.
- Generation Brands (Visual Comfort & Co.)
- Zumtobel Group
- FLOS S.p.A.
- Hudson Valley Lighting Group
- Artemide S.p.A.
- Feilo Sylvania
- Panasonic Life Solutions
- Cree Lighting
- Lutron Electronics
- Hinkley Lighting
- Savoy House
- Schonbek Worldwide Lighting
- Currey & Company
- Foscarini*
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand for Home Aesthetics & Interior Design
- 4.2.2 Urbanization and Rising Residential Construction
- 4.2.3 Technological Advancements (Smart & Energy-Efficient Lighting)
- 4.2.4 Growth in Hospitality and Commercial Real Estate Sectors
- 4.2.5 Expanding E-Commerce and Online Retail Channels
- 4.3 Market Restraints
- 4.3.1 High Cost of Premium and Designer Fixtures
- 4.3.2 Energy Regulations and Compliance Standards
- 4.3.3 Installation Complexity and Maintenance Issues
- 4.3.4 Volatility in Raw Material Prices (Glass, Crystal, Metal)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power Suppliers
- 4.7.2 Bargaining Power Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Ceiling Lights
- 5.1.1.1 Flush/Surface Mount
- 5.1.1.2 Semi-Flush
- 5.1.1.3 Recessed Downlights
- 5.1.1.4 Pendant & Drop Lights
- 5.1.2 Chandeliers
- 5.1.2.1 Traditional
- 5.1.2.2 Transitional
- 5.1.2.3 Modern / Contemporary
- 5.1.1 Ceiling Lights
- 5.2 By Lighting Technology
- 5.2.1 LED
- 5.2.2 Fluorescent
- 5.2.3 Incandescent & Halogen
- 5.2.4 HID & Others
- 5.3 By Material
- 5.3.1 Metal
- 5.3.2 Crystal
- 5.3.3 Glass
- 5.3.4 Wood & Natural Materials
- 5.3.5 Plastics & Composites
- 5.4 By End-user
- 5.4.1 Residential
- 5.4.2 Commercial
- 5.4.2.1 Offices and Co-Working Spaces
- 5.4.2.2 Hospitality (Hotels, Resorts, Restaurants)
- 5.4.2.3 Retail & Shopping Malls
- 5.4.2.4 Healthcare Facilities
- 5.4.2.5 Educational Institutions
- 5.4.3 Industrial
- 5.5 By Distribution Channel
- 5.5.1 Offline/Showrooms & Specialty Stores
- 5.5.2 DIY and Home-Improvement Chains
- 5.5.3 Online/E-commerce Platforms
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 Canada
- 5.6.1.2 United States
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Peru
- 5.6.2.3 Chile
- 5.6.2.4 Argentina
- 5.6.2.5 Rest of South America
- 5.6.3 Asia-Pacific
- 5.6.3.1 India
- 5.6.3.2 China
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- 5.6.3.7 Rest of Asia Pacific
- 5.6.4 Europe
- 5.6.4.1 United Kingdom
- 5.6.4.2 Germany
- 5.6.4.3 France
- 5.6.4.4 Spain
- 5.6.4.5 Italy
- 5.6.4.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.6.4.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.6.4.8 Rest of Europe
- 5.6.5 Middle East And Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 South Africa
- 5.6.5.4 Nigeria
- 5.6.5.5 Rest of Middle East And Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments}
- 6.4.1 Signify (Philips Lighting)
- 6.4.2 OSRAM GmbH
- 6.4.3 Eglo Leuchten GmbH
- 6.4.4 Kichler Lighting LLC
- 6.4.5 Hubbell Lighting Inc.
- 6.4.6 Generation Brands (Visual Comfort & Co.)
- 6.4.7 Zumtobel Group
- 6.4.8 FLOS S.p.A.
- 6.4.9 Hudson Valley Lighting Group
- 6.4.10 Artemide S.p.A.
- 6.4.11 Feilo Sylvania
- 6.4.12 Panasonic Life Solutions
- 6.4.13 Cree Lighting
- 6.4.14 Lutron Electronics
- 6.4.15 Hinkley Lighting
- 6.4.16 Savoy House
- 6.4.17 Schonbek Worldwide Lighting
- 6.4.18 Currey & Company
- 6.4.19 Foscarini*
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment