

|
시장보고서
상품코드
2154973
유럽의 넷 제로 에너지 빌딩 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Net-Zero Energy Buildings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
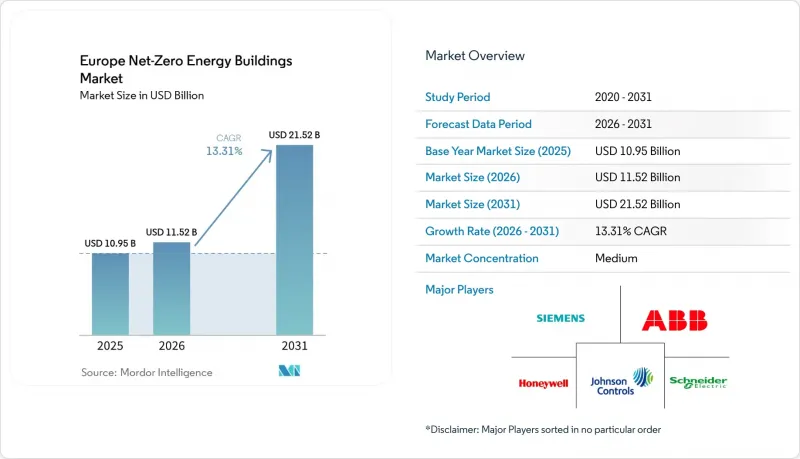
에 따르면 유럽의 넷 제로 에너지 건물 시장 규모는 2025년에 109억 5,000만 달러, 2026년에 115억 2,000만 달러에 달하며, 2031년까지 215억 2,000만 달러에 달할 것으로 예측되고 있으며, 2026-2031년에 CAGR 13.31%로 성장할 것으로 전망되고 있습니다.
유럽 넷제로 에너지 건축물 시장의 동향 및 인사이트
개정된 EPBD 및 제로 배출 건축물 의무화 시한이 도입을 가속화
개정된 EPBD는 2024년 5월 28일에 발효되었으며, 2026년 5월 29일까지 각국에서 국내법에 반영해야 할 의무가 부과되었습니다. 이 기한으로 인해 설계, 에너지 관리, 시운전, 인증 서비스를 제공하는 업체들에게 프로젝트 파이프라인이 더욱 명확해졌습니다. 2028년 1월 1일 이후, 모든 신규 공공 건축물은 제로 배출 건축물이어야 합니다. 2030년 1월 1일부터는 모든 신축 건물이 동일한 기준을 충족해야 합니다. 이 기준에서는 매우 높은 에너지 성능과 부지내 화석 연료 유래 탄소 배출 제로가 요구됩니다. 독일에서 제안된 ‘건축물 현대화법’은 EPBD의 정의를 거의 그대로 따르고 있으며, 2026년 6월 조사에서는 이러한 전환을 위한 법적 체계가 설명되어 있습니다.
‘리노베이션 웨이브’ 자금이 근본적인 에너지 개보수 활동을 지원
유럽의 순제로 에너지 건축물 시장은 공공 개보수 자금에 의해 지원되고 있지만, 자금만으로는 공급 격차를 메울 수 없습니다. ‘회복·탄력성 기금(RRF)’에서는 800억 유로(880억 달러) 이상이, ‘연대 정책 기금’에서는 170억 유로(187억 달러)가 2021-2027년까지의 에너지 성능 향상을 위해 제공되었습니다. 또한 유럽집행위원회는 2030년까지 건물에 대한 연간 투자 수요가 2,420억 유로(2,662억 달러) 이상에 달할 것으로 추산하고 있습니다. 2025년, 프랑스의 건물 에너지 개보수에 대한 국가 지출은 79억 유로(87억 달러)에 달했습니다. 2025년 독일의 주택 개보수율은 0.7%였으나, 기후 목표 달성을 위해서는 2%의 개보수율이 필요합니다. 프랑스와 북유럽 국가들은 단기적인 대규모 개보수 공사 증가에 대응할 수 있는 체계를 갖추고 있습니다.
높은 초기 투자 비용과 긴 회수 기간이 보급을 저해
건물 전체를 개보수하는 데는 1제곱미터당 300-500유로(1제곱미터당 330-550달러)의 비용이 들 수 있으며, 그 투자 회수 기간은 많은 소유주의 계획 기간을 초과하게 됩니다. 이러한 압박은 소유주가 직접 거주하는 주택이나 소유주가 분산되어 있는 주택 재고에서 가장 심각합니다. 프랑스에서는 ‘MaPrimeRenov’ 보조금 제도 변경 이후, 2022-2024년에 주택 에너지 개보수 투자가 실질적으로 22% 감소했습니다. ‘Renovate Europe’은 저금리 개보수 대출에 대한 보증을 지원하기 위해 전용 ‘EU 개보수 대출 시설’의 창설을 요구하고 있습니다. 이 캠페인에서는 자가 주택이 EU 주택의 70%를 차지하고 있음에도 불구하고 기존 금융 상품을 통한 지원이 여전히 불충분하다는 점이 지적되었습니다. 표준적인 대출 상품이 없기 때문에 업체 입장에서는 설치 역량에 대한 투자를 할 때의 확실성이 떨어지고 있습니다.
부문 분석
2025년, 유럽의 순제로 에너지 건축물 시장에서 상업용 건물이 44.6%의 점유율을 차지했습니다. 기업의 지속가능성 의무와 투자자에 대한 보고 요건으로 인해 비주거용 부동산의 리모델링 시급성이 높아지고 있습니다. 독일, 프랑스, 영국의 사무실 및 소매 시설 포트폴리오는 연면적이 넓기 때문에 규정 준수 위험에 크게 노출되어 있습니다. EPBD(유럽 건축물 에너지 성능 지침)는 회원국들에게 2030년까지 에너지 성능이 가장 낮은 비주거용 건축물의 16%를 개선할 것을 요구하고 있습니다. 주거용 부동산에는 큰 기회가 있지만, 소유권의 분산과 자금 조달 제약으로 인해 의사결정이 지연되고 있습니다. 조립식 파사드 패널을 활용한 연속 개보수는 현장 작업 시간을 단축하고 시공 비용을 절감하는 방법으로 주목받고 있습니다.
공공 시설 시장은 2026-2031년까지 연평균 성장률(CAGR) 14.2%로 성장할 것으로 예측됩니다. 병원, 대학 및 공공 시설 포트폴리오는 정해진 기한 내에 규모가 크고 운영상 복잡한 자산을 관리해야 합니다. 2028년 1월 1일이라는 공공 시설의 마감 기한으로 인해 이들 소유주는 민간 부문 소유주보다 의사결정에 주어진 유예 기간이 짧습니다. 존슨 컨트롤즈(Johnson Controls)는 덴마크 올보 대학병원에서 통합적인 개보수 접근 방식을 통해 최대 80%의 에너지 절감 효과를 달성했다고 보고했습니다. 이러한 프로젝트에서는 설계, 프로젝트 관리, 시운전 및 건물 에너지 관리 시스템을 통합할 수 있는 공급업체가 우대받습니다. 산업용 건물은 4가지 건물 유형 중 여전히 규모가 가장 작은 편이지만, 탈탄소화 계획에 따라 중부 유럽의 제조 시설에서의 활동이 촉진되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 가치 및 공급망 분석
- 규제 상황
- 기술 전망
- 시장의 변천과 보급의 동향
- 주요 넷-제로 에너지 건축 프로젝트
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 건축 유형별
- 제공 서비스별
- 건설 유형별
- 지역별
- 영국
- 독일
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Siemens AG
- Schneider Electric SE
- Johnson Controls International plc
- ABB Ltd.
- Honeywell International Inc.
- Daikin Industries, Ltd.
- Carrier Global Corporation
- Trane Technologies plc
- Saint-Gobain S.A.
- Kingspan Group plc
- ROCKWOOL A/S
- Bosch Building Technologies
- Legrand SA
- Mitsubishi Electric Corporation
- Eaton Corporation plc
- Skanska AB
- VINCI Construction
- Bouygues Construction
- WSP Global Inc.
- Belimo Holding AG
제7장 시장 기회와 향후 전망
KSAAccording to Mordor Intelligence, the Europe Net-Zero energy buildings market size is projected to be USD 10.95 billion in 2025, USD 11.52 billion in 2026, and reach USD 21.52 billion by 2031, growing at a CAGR of 13.31% from 2026 to 2031.
Europe Net-Zero Energy Buildings Market Trends and Insights
Revised EPBD and Zero-Emission Building Deadlines Accelerate Adoption
The recast EPBD entered into force on May 28, 2024, and required national transposition by May 29, 2026. This deadline is creating a clearer project pipeline for providers of design, energy management, commissioning, and certification services. All new public buildings must be zero-emission buildings from January 1, 2028. All new buildings must meet the same standard as of January 1, 2030. The standard requires very high energy performance and no on-site fossil-fuel carbon emissions. Germany's proposed Building Modernization Act closely adopts the EPBD definition, and a June 2026 study described the transition's legal structure.
Renovation Wave Funding Drives Deep Energy Retrofit Activity
The Europe net-zero energy buildings market is supported by public renovation funding, although funding alone does not close the delivery gap. The Recovery and Resilience Facility provided more than EUR 80 billion (USD 88 billion), and Cohesion Policy Funds provided EUR 17 billion (USD 18.7 billion) to improve energy performance between 2021 and 2027. The European Commission also identified annual investment needs of more than EUR 242 billion (USD 266.2 billion) for buildings through 2030. France's state spending on building energy renovation reached EUR 7.9 billion (USD 8.7 billion) in 2025. Germany's residential renovation rate was 0.7% in 2025, compared with the 2% rate needed for climate goals. France and the Nordic countries have delivery systems better positioned to absorb a near-term increase in deep retrofit work.
High Upfront Capital Costs and Long Payback Periods Limit Adoption
Whole-building renovation can require EUR 300 to EUR 500 per square meter (USD 330 to USD 550 per square meter), extending payback periods beyond many owners' planning horizons. The pressure is most acute for owner-occupied and fragmented residential stock. Residential energy renovation investment in France fell 22% in real terms between 2022 and 2024 after changes to the MaPrimeRenov subsidy structure. Renovate Europe has called for a dedicated EU Renovation Loan Facility to support guarantees for low-interest renovation loans. The campaign noted that owner-occupied homes account for 70% of EU residences and remain poorly served by existing financial products. Without standard financing products, suppliers have less certainty to invest in installation capacity.
Other drivers and restraints analyzed in the detailed report include:
- Energy Cost Volatility Increases Demand For Building Energy Resilience
- Green Finance and ESG Reporting Support Net-Zero Building Investments
- Shortage of Building Physics and Retrofit Professionals Delays Projects
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Commercial buildings held 44.6% of the Europe net-zero energy buildings market share in 2025. Corporate sustainability obligations and investor reporting requirements have increased the urgency of upgrades in non-residential property. Office and retail portfolios in Germany, France, and the United Kingdom face significant compliance exposure because of their large floor areas. The EPBD requires member states to address the worst-performing 16% of non-residential buildings by 2030. Residential properties offer a large opportunity, but fragmented ownership and financing constraints slow decision-making. Serial renovation using prefabricated facade panels is emerging as a way to reduce time on site and lower delivery costs.
Institutional buildings are forecast to grow at a 14.2% CAGR from 2026 to 2031. Hospitals, universities, and public portfolios must manage large, operationally complex assets within defined deadlines. The January 1, 2028, public-building deadline gives these owners a shorter decision window than private-sector owners. Johnson Controls reported energy savings of up to 80% at Aalborg University Hospital in Denmark through an integrated retrofit approach. These projects favor suppliers that can combine design, project management, commissioning, and building energy management systems. Industrial buildings remain the smallest of the 4 building types, although decarbonization plans are supporting activity in Central European manufacturing facilities.
Complete Report Scope:
- By Building Type
- Residential
- Commercial
- Institutional
- Industrial
- By Offerings
- Solutions (New Net-Zero Energy Building Development, Net-Zero Building Retrofit, Integrated Design & Delivery and Smart Net-Zero Building Solutions)
- Services (Architectural & Engineering Design, Construction Services, Commissioning & Certification Services and Consulting Services)
- By Construction Type
- New Construction
- Renovation
- By Geography
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Siemens AG
- Schneider Electric SE
- Johnson Controls International plc
- ABB Ltd.
- Honeywell International Inc.
- Daikin Industries, Ltd.
- Carrier Global Corporation
- Trane Technologies plc
- Saint-Gobain S.A.
- Kingspan Group plc
- ROCKWOOL A/S
- Bosch Building Technologies
- Legrand SA
- Mitsubishi Electric Corporation
- Eaton Corporation plc
- Skanska AB
- VINCI Construction
- Bouygues Construction
- WSP Global Inc.
- Belimo Holding AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Revised EPBD and Zero-Emission Building Deadlines Accelerate Adoption
- 4.2.2 Renovation Wave Funding Drives Deep Energy Retrofit Activity
- 4.2.3 Energy Cost Volatility Increases Demand For Building Energy Resilience
- 4.2.4 Green Finance and ESG Reporting Support Net-Zero Building Investments
- 4.2.5 Grid-Interactive Buildings Generate Demand Response Revenue Opportunities
- 4.2.6 Verified Energy Performance Increases Green Building Rental Premiums
- 4.3 Market Restraints
- 4.3.1 High Upfront Capital Costs and Long Payback Periods Limit Adoption
- 4.3.2 Shortage Of Building Physics and Retrofit Professionals Delays Projects
- 4.3.3 Legacy System Integration Challenges Increase Performance Gap Risks
- 4.3.4 Cybersecurity, Data Governance, and Interoperability Risks Hinder Smart Building Deployment
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Market Evolution and Adoption Trends
- 4.8 Key Net-Zero Energy Building Projects
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Consumers
- 4.9.3 Threat of New Entrants
- 4.9.4 Threat of Substitutes
- 4.9.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Building Type
- 5.1.1 Residential
- 5.1.2 Commercial
- 5.1.3 Institutional
- 5.1.4 Industrial
- 5.2 By Offerings
- 5.2.1 Solutions (New Net-Zero Energy Building Development, Net-Zero Building Retrofit, Integrated Design & Delivery and Smart Net-Zero Building Solutions)
- 5.2.2 Services (Architectural & Engineering Design, Construction Services, Commissioning & Certification Services and Consulting Services)
- 5.3 By Construction Type
- 5.3.1 New Construction
- 5.3.2 Renovation
- 5.4 By Geography
- 5.4.1 United Kingdom
- 5.4.2 Germany
- 5.4.3 France
- 5.4.4 Italy
- 5.4.5 Spain
- 5.4.6 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Siemens AG
- 6.4.2 Schneider Electric SE
- 6.4.3 Johnson Controls International plc
- 6.4.4 ABB Ltd.
- 6.4.5 Honeywell International Inc.
- 6.4.6 Daikin Industries, Ltd.
- 6.4.7 Carrier Global Corporation
- 6.4.8 Trane Technologies plc
- 6.4.9 Saint-Gobain S.A.
- 6.4.10 Kingspan Group plc
- 6.4.11 ROCKWOOL A/S
- 6.4.12 Bosch Building Technologies
- 6.4.13 Legrand SA
- 6.4.14 Mitsubishi Electric Corporation
- 6.4.15 Eaton Corporation plc
- 6.4.16 Skanska AB
- 6.4.17 VINCI Construction
- 6.4.18 Bouygues Construction
- 6.4.19 WSP Global Inc.
- 6.4.20 Belimo Holding AG
7 Market Opportunities & Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


