

|
시장보고서
상품코드
2155298
폐루프 네트워크 자동화 소프트웨어 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Closed-Loop Network Automation Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
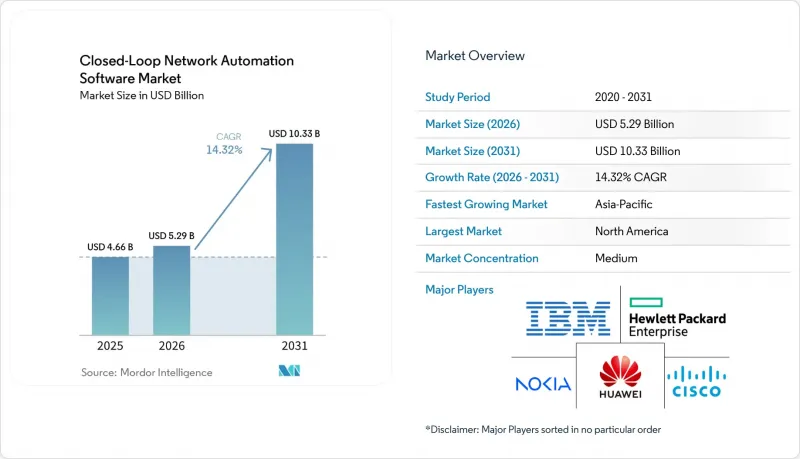
에 따르면 폐루프·네트워크 자동화 소프트웨어 시장 규모는 2025년에 46억 6,000만 달러, 2026년에 52억 9,000만 달러에 달하며, 2031년까지 103억 3,000만 달러에 달할 것으로 예측되고 있으며, 2026-2031년에 CAGR 14.32%로 성장할 것으로 전망되고 있습니다.
전 세계 폐쇄 루프 네트워크 자동화 소프트웨어 시장의 동향 및 인사이트
하이브리드 및 멀티클라우드 네트워크의 복잡화
조직에서는 레거시 사이트, 엣지 노드, 분산형 애플리케이션과 병행하여 여러 클라우드 환경을 운영하는 사례가 늘어나면서, 일상적인 변경 사항을 조정하기가 어려워지고 있습니다. 클로즈드 루프 네트워크 자동화 소프트웨어 시장은 서로 다른 환경에 걸친 네트워크 상태, 정책 및 자동화된 조치를 연계함으로써 이러한 운영상의 부담을 해소합니다. 자동화가 통합되지 않은 경우, 네트워크 팀은 여러 모니터링 및 관리 콘솔을 넘나들며 작업하는 경우가 많아, 조사 지연이나 운영 관행의 불일치를 초래합니다. 마이크로소프트는 AI 오케스트레이션 에이전트를 활용하여 하이브리드 클라우드 통합을 수개월이 소요되는 수동 프로세스에서 하루 만에 완료되는 자동화된 워크플로로 전환한 2025년 사내 프로그램에 대해 설명했습니다. 시스코는 2026년에 ‘Multicloud Fabric’을 도입하여, Cisco Cloud Control을 통해 사이트 간 및 클라우드 간 자동화된 패브릭을 제공했습니다. 새로운 클라우드나 네트워크 도메인이 추가될 때마다 공유 제어 프레임워크의 운영적 가치는 더욱 높아집니다. 특히 팀이 해당 도메인 전반에 걸쳐 보안 및 서비스 정책을 유지해야 하는 경우, 그 가치는 더욱 두드러집니다.
AI 기반 예측 운영 및 네트워크 분석
AI 기반 운영은 기본적인 이상 탐지에서 정의된 정책 제어 하에 일상적인 시정 조치를 권장하거나 실행할 수 있는 시스템으로 전환되고 있습니다. 네트워크 운영 센터에서 운영자가 장애 대응 속도 향상과 수작업 감소를 요구하게 되면, 폐쇄 루프형 네트워크 자동화 소프트웨어 시장이 그 혜택을 누리게 됩니다. 노키아와 인더사트 오오리두 허치슨은 2026년, 네트워크 운영을 위해 검증된 자동화 기능을 활용한 자율형 네트워크 구상에 대해 설명했습니다. 이러한 변화는 인력 수요에도 변화를 가져옵니다. 정책 설계, 데이터 품질, 모델 거버넌스, 멀티벤더 통합에는 기존 네트워크 관리와는 다른 기술이 요구되기 때문입니다. 따라서 각 벤더들은 분석 속도뿐만 아니라 설명 가능성, 데이터 관리, 자율적 조치에 관한 보안 대책에서도 경쟁을 펼치고 있습니다. 핵심 AI 기능이 더욱 보편화됨에 따라 AI 기반 권장 사항을 감사 가능한 운영 워크플로우와 연계하는 플랫폼은 규제 대상 통신사업자 및 기업에서 더욱 뚜렷한 우위를 확보할 수 있을 것입니다.
레거시 환경 및 멀티 벤더 환경에서의 높은 통합 비용
레거시 운영 지원 시스템, 네트워크 관리 플랫폼 및 멀티 벤더 장비에는 프로그래밍을 통한 제어를 위한 일관된 인터페이스가 부족한 경우가 많습니다. 이로 인해 소프트웨어 라이선스 자체의 가격이 저렴하더라도, 통합에 드는 노력이 폐쇄형 네트워크 자동화 소프트웨어 시장에서의 도입을 가로막는 주요 장벽이 되고 있습니다. 라우팅, 스위칭, SD-WAN, 보안 및 무선 네트워크에서는 각각 서로 다른 API, 구성 모델, 데이터 구조가 사용될 수 있습니다. 이러한 차이점으로 인해 자동화된 워크플로가 전체 환경에서 안전하게 작동하려면 커넥터의 도입 및 테스트가 필요합니다. 노키아와 에릭슨은 2026년, 노키아의 ‘SMO 마켓플레이스’와 에릭슨의 ‘rApp Ecosystem’ 간의 연동을 포함한 상호 운용성 구상을 발표했습니다. 표준을 준수하는 관리 인터페이스의 보급을 통해 이러한 장벽을 완화하는 것은 가능하지만, 도입된 장비가 혼재된 상황에서는 완전 자동화된 도입의 진전이 계속해서 지연될 것입니다.
부문 분석
2025년, 폐쇄형 네트워크 자동화 소프트웨어 시장에서 소프트웨어가 58.21%의 점유율을 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 15.54%로 성장할 것으로 전망됩니다. 이러한 상황은 통신사업자들이 자본 집약적인 하드웨어 업데이트에서 지능 및 오케스트레이션 계층에 대한 지속적인 투자로 전환하고 있음을 반영합니다. 소프트웨어에는 인텐트 기반 네트워킹 엔진, 정책 주도형 자동화, 분석, 그리고 여러 인프라 도메인에 걸쳐 작동하는 제어 기능이 포함됩니다. 이러한 기능을 통해 팀은 고립된 설정 작업에서 보다 협업적인 운영 모델로 전환할 수 있게 됩니다.
하드웨어에 내장된 자동화는 신규 도입이나 네트워크 운영 체제 및 컨트롤러와 직접 관련된 기능에서는 여전히 중요하지만, 오케스트레이션 로직이 벤더 중립적인 소프트웨어 계층으로 이동함에 따라 그 확대 속도는 둔화되고 있습니다. 또한 도입, 통합 및 관리형 운영을 통해 사내에 자동화 팀을 보유하지 않은 고객의 도입 장벽을 낮출 수 있으므로, 서비스도 계속해서 중요한 역할을 수행하고 있습니다. 구성 요소의 구성을 살펴보면, 상업적 가치는 단일 물리적 장치 범주가 아닌 소프트웨어 계층에 점점 더 집중되고 있음을 알 수 있습니다. 이러한 추세는 고객의 요구 사항 변화에 맞춰 기능을 지속적으로 업데이트할 수 있는 공급업체에게 유리합니다. 또한 고객에게 이미 도입된 하드웨어를 교체하도록 강요하지 않고, 기존 장비 전체에서 작동하는 플랫폼의 가치를 높여줍니다.
2025년에는 클라우드 배포이 매출의 45.44%를 차지하는 반면, 하이브리드 도입은 2031년까지 연평균 성장률(CAGR) 16.54%로 성장할 것으로 예측됩니다. 클라우드를 통해 제공되는 OSS, BSS 및 오케스트레이션 플랫폼은 자동화를 처음 도입하는 조직의 경우 도입 장벽을 낮출 수 있습니다. 또한 분산된 거점 전반에 걸쳐 분석 및 통합된 정책 관리를 보다 쉽게 활용할 수 있게 해줍니다. 하이브리드 도입은 기밀성이 높은 트래픽, 감사 데이터 또는 변경 실행을 관리된 환경 내에 유지하면서 클라우드 기반 분석 기능을 활용할 수 있게 함으로써 다양한 요구 사항을 충족합니다. 이 모델은 의료, BFSI(은행·금융·보험), 에너지·공공사업, 정부 기관 및 기타 규제 대상 최종사용자에게 특히 중요합니다.
온프레미스 배포는 데이터 상주 요건으로 인해 호스팅형 오케스트레이션 플랫폼의 사용이 제한되는 국방, 공공 부문 및 주권 사업자에게 여전히 중요합니다. 따라서 배포 방식의 선택은 단순한 기술적 선호가 아니라 운영 및 규정 준수 요건을 반영한 결과입니다. 하이브리드 모델을 통해 고객은 모든 운영 통제권을 즉시 퍼블릭 클라우드로 이전하지 않고도 클라우드의 민첩성을 활용할 수 있습니다. 그 결과, 하이브리드 배포는 더 높은 수준의 자율성을 향해 신중하게 나아가는 조직에 중요한 전환 경로를 제공합니다.
지역별 분석
2025년에는 북미가 클로즈드 루프 네트워크 자동화 소프트웨어 시장에서 33.32%의 점유율을 차지할 것으로 예상됩니다. 이 지역은 견고한 기업용 기술 투자, 활발한 5G 구상, 그리고 주요 클라우드 네트워크 플랫폼 제공업체의 존재라는 이점을 누리고 있습니다. AI 인프라 구축으로 인해 동적인 네트워크 관리의 필요성을 높이는 트래픽 패턴과 운영 요구 사항이 발생하고 있습니다. 금융 서비스 및 의료 기관은 신뢰성 높고 안전하며 감사 가능한 네트워크 서비스를 필요로 하므로 주요 기업 도입처로 자리 잡고 있습니다. 캐나다에서는 금융 서비스 및 천연 자원 부문의 사용자들로부터 수요가 발생하고 있습니다. 한편, 멕시코에서는 통신사업자들이 네트워크 합리화를 추진함에 따라 CSP(통신 서비스 제공업체)에게 새로운 비즈니스 기회가 창출되고 있습니다. 시스코는 라스베이거스에서 개최되는 ‘Cisco Live 2026’에서 ‘Multicloud Fabric’ 및 ‘AgenticOps’ 모델을 발표할 예정입니다. 이러한 움직임은 해당 지역이 통합된 운영 환경 내에서 클라우드 연결, 보안, 자동화를 통합하는 데 주력하고 있음을 반영합니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 16.54%로 확대될 것으로 예측되며, 가장 빠르게 성장하는 지역이 될 전망입니다. 중국에서는 2026년 초까지 400만 기 이상의 5G 기지국이 도입될 것으로 예상되며, 무선, 코어, 전송 네트워크 전반에 걸쳐 막대한 자동화 수요가 발생하고 있습니다. 인도에서는 디지털 및 5G 인프라 구축이 진행 중이며, 가입자 수요가 증가함에 따라 통신사업자들이 AI 기반 최적화를 도입하도록 촉진되고 있습니다. 일본과 한국도 네트워크 슬라이싱 및 프라이빗 5G 구상을 통해 수요를 견인하고 있습니다. NTT 도코모와 NEC는 2026년에 AWS 상에서 일본 최초의 상용 5G 코어를 가동할 전망입니다. 인도네시아, 말레이시아, 베트남에서는 5G 네트워크 확장에 따라 자동 프로비저닝이 도입되고 있습니다. 말레이시아는 신흥 통신사업자 시장에서 검증된 첨단 자율화의 초기 사례로 주목받고 있습니다. 폐쇄형 네트워크 자동화 소프트웨어 시장은 대규모 네트워크 전반에 걸쳐 재현 가능한 표준 기반의 운영을 필요로 하는 이러한 도입의 혜택을 받고 있습니다.
유럽은 여전히 중요한 시장이며, 도이체 통신, 오렌지, 보다폰, 텔레포니카 등 각사는 오픈 RAN에 부합하는 자동화 및 슬라이싱 오케스트레이션에 대한 투자를 지속하고 있습니다. 오렌지와 에릭슨은 유럽 전역의 사업에서 기업 및 가입자용 사용 사례를 위한 자동화된 5G 서비스 구축에 협력하고 있습니다. 남미에서는 브라질과 아르헨티나의 CSP 자동화 구상을 통해 발전이 진행되고 있으며, 초기 도입은 프로비저닝과 장애 관리에 중점을 두고 있습니다. 중동에서는 사우디아라비아의 인프라 구축 프로그램과 UAE의 5G-Advanced 도입을 통해 추진력이 강화되고 있습니다. 노키아는 MWC 2026에서 에이전트형 AI를 활용한 네트워크 슬라이싱의 조기 도입 사업자로 du를 선정했습니다. 아프리카는 여전히 도입 초기 단계에 있지만, 남아프리카공화국과 나이지리아의 통신사업자들은 자율형 네트워크 접근 방식을 모색하고 있습니다. 화웨이는 2025년에 남아프리카공화국의 MTN 및 스페인의 MasOrange와 함께 레벨 4 자율형 네트워크 도입 실적을 보고했습니다. 이러한 지역별 차이는 기본적인 프로비저닝 툴부터 보다 광범위한 인텐트 기반 오케스트레이션 플랫폼에 이르기까지 공급업체에게 다양한 비즈니스 기회를 창출하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 거시경제 요인이 시장에 미치는 영향
- 업계 밸류체인 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 컴포넌트별
- 배포별
- 네트워크 인프라별
- 최종사용자별
- 조직 규모별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 유럽
- 영국
- 독일
- 프랑스
- 이탈리아
- 기타 유럽 국가
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- 기타 아시아태평양 국가
- 중동
- 사우디아라비아
- 아랍에미리트
- 기타 중동 국가
- 아프리카
- 남아프리카공화국
- 나이지리아
- 기타 아프리카 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Cisco Systems, Inc.
- Hewlett Packard Enterprise Company
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- Ciena Corporation
- IBM Corporation
- Arista Networks, Inc.
- Extreme Networks, Inc.
- VMware by Broadcom
- Amdocs Limited
- Netcracker Technology Corporation
- Oracle Corporation
- NEC Corporation
- Red Hat, Inc.
- Forward Networks, Inc.
- NetBrain Technologies, Inc.
- Itential, Inc.
- Gluware, Inc.
- BackBox Software Inc.
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the closed-loop network automation software market size is projected to be USD 4.66 billion in 2025, USD 5.29 billion in 2026, and reach USD 10.33 billion by 2031, growing at a CAGR of 14.32% from 2026 to 2031.
Global Closed-Loop Network Automation Software Market Trends and Insights
Rising Hybrid and Multicloud Network Complexity
Organizations increasingly operate several cloud environments alongside legacy sites, edge nodes, and distributed applications, making routine changes harder to coordinate. The closed-loop network automation software market addresses this operational burden by linking network state, policies, and automated actions across separate environments. Network teams often work across multiple monitoring and management consoles when automation is not consolidated, slowing investigations and creating inconsistent operating practices. Microsoft described a 2025 internal program that changed hybrid-cloud integration from a months-long manual process into a one-day automated workflow using an AI orchestration agent. Cisco introduced Multicloud Fabric in 2026 to provide an automated site-to-cloud and cloud-to-cloud fabric through Cisco Cloud Control. Each new cloud or network domain increases the operational value of a shared control framework, particularly when teams must preserve security and service policies across those domains.
AI-Driven Predictive Operations and Network Analytics
AI-driven operations are moving from basic anomaly identification to systems that can recommend or perform routine corrective actions under defined policy controls. The closed-loop network automation software market benefits when operators seek faster fault handling and lower manual work in network operations centers. Nokia and Indosat Ooredoo Hutchison described autonomous-network work in 2026 that used validated automation capabilities for network operations. The shift also changes workforce needs, as policy design, data quality, model governance, and multivendor integration require skills that differ from those of traditional network administration. Vendors therefore compete on explainability, data management, and safeguards around autonomous actions, not only on the speed of analytics. As core AI capabilities become more common, platforms that connect AI recommendations to auditable operational workflows can hold a clearer position with regulated operators and enterprises.
High Integration Costs Across Legacy and Multivendor Environments
Legacy operational support systems, network-management platforms, and multivendor equipment often lack consistent interfaces for programmatic control. This makes integration effort a central barrier to adoption in the closed-loop network automation software market, even when the software license itself is affordable. Routing, switching, SD-WAN, security, and radio networks can use different APIs, configuration models, and data structures. These differences require connectors and testing before an automated workflow can operate safely across the full environment. Nokia and Ericsson announced interoperability work in 2026, including cooperation between Nokia's SMO Marketplace and Ericsson's rApp Ecosystem. Wider use of standards-compliant management interfaces can reduce this friction, but mixed installed equipment will continue to slow fully automated deployments.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of 5G, Network Slicing, and Programmable Connectivity
- Demand for Zero-Touch Provisioning and Lower Operational Costs
- Shortage of Network Automation and AI Operations Skills
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software accounted for 58.21% of the closed-loop network automation software market share in 2025 and is projected to grow at a CAGR of 15.54% through 2031. This position reflects operators' shift from capital-intensive hardware renewals toward continuous investment in intelligence and orchestration layers. Software includes intent-based networking engines, policy-driven automation, analytics, and control functions that operate across multiple infrastructure domains. These capabilities enable teams to move from isolated configuration tasks to a more coordinated operating model.
Hardware-embedded automation remains relevant for greenfield deployments and functions directly linked to network operating systems or controllers. However, it is expanding more slowly as orchestration logic shifts to vendor-neutral software layers. Services also remain important, as implementation, integration, and managed operations can reduce adoption barriers for customers without in-house automation teams. The component mix indicates that commercial value is increasingly concentrated in the software layer rather than in a single physical device category. This trend benefits suppliers that can continuously update capabilities as customer requirements evolve. It also increases the value of platforms that operate across existing equipment rather than requiring customers to replace installed hardware.
Cloud deployment accounted for 45.44% of revenue in 2025, while hybrid deployment is projected to grow at a 16.54% CAGR through 2031. Cloud-delivered OSS, BSS, and orchestration platforms can reduce implementation barriers for organizations adopting automation for the first time. They also make analytics and centralized policy management more accessible across distributed sites. Hybrid deployment addresses a different requirement by allowing customers to use cloud-based analytics while retaining sensitive traffic, audit data, or change execution in controlled environments. This model is particularly relevant for healthcare, BFSI, energy and utilities, government, and other regulated end users.
On-premises deployment remains important for defense, public-sector, and sovereign operators, where data-residency requirements limit the use of hosted orchestration platforms. Therefore, deployment choices reflect operational and compliance requirements rather than technology preferences alone. Hybrid models enable customers to benefit from cloud agility without immediately moving all operational control to a public cloud. As a result, hybrid deployment provides an important transition path for organizations progressing cautiously toward higher levels of autonomy.
Complete Report Scope:
- By Component
- Software
- Hardware-Embedded Automation
- Services
- By Deployment
- Cloud
- On-Premises
- Hybrid
- By Network Infrastructure
- Physical Network Infrastructure
- Virtual Network Infrastructure
- Cloud-Native Network Infrastructure
- Hybrid Network Infrastructure
- By End User
- Communications Service Providers
- Mobile Network Operators
- Fixed-Line Operators
- Cable and Broadband Providers
- Internet Service Providers
- Enterprises
- Banking, Financial Services, and Insurance
- Manufacturing
- Healthcare
- Energy and Utilities
- Government and Public Sector
- Retail and E-Commerce
- Media and Entertainment
- Transportation and Logistics
- Managed Service Providers and Cloud Service Providers
- Communications Service Providers
- By Organization Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America is expected to hold a 33.32% share of the closed-loop network automation software market in 2025. The region benefits from strong enterprise technology spending, active 5G initiatives, and the presence of major cloud and network platform providers. AI infrastructure buildouts are creating traffic patterns and operational requirements that increase the need for dynamic network management. Financial services and healthcare organizations represent significant enterprise adopters because they require reliable, secure, and auditable network services. Canada is generating demand from users in the financial services and natural resources sectors, while Mexico presents an emerging CSP opportunity as operators rationalize their networks. Cisco is set to unveil Multicloud Fabric and its AgenticOps model at Cisco Live 2026 in Las Vegas. These developments reflect the region's focus on integrating cloud connectivity, security, and automation within a unified operating environment.
Asia-Pacific is projected to expand at a CAGR of 16.54% through 2031, making it the fastest-growing region. China is expected to deploy more than 4 million 5G base stations by early 2026, creating substantial automation requirements across radio, core, and transport networks. India is advancing its digital and 5G infrastructure, encouraging operators to adopt AI-based optimization as subscriber demand rises. Japan and South Korea are also driving demand through network slicing and private 5G initiatives. NTT DOCOMO and NEC are expected to launch Japan's first commercial 5G core on AWS in 2026. Indonesia, Malaysia, and Vietnam are adopting automated provisioning as their 5G networks expand. Malaysia has emerged as an early example of validated advanced autonomy in an emerging operator market. The closed-loop network automation software market benefits from these deployments, which require repeatable, standards-based operations across large-scale networks.
Europe remains an important market, as Deutsche Telekom, Orange, Vodafone, and Telefonica continue to invest in open RAN-aligned automation and slicing orchestration. Orange and Ericsson are collaborating on automated 5G service creation for enterprise and subscriber use cases across European operations. South America is developing through CSP automation initiatives in Brazil and Argentina, with early adoption focused on provisioning and fault management. The Middle East is gaining momentum through infrastructure programs in Saudi Arabia and 5G-Advanced deployments in the UAE. Nokia selected du as an early adopter of agentic AI-powered network slicing at MWC 2026. Africa remains at an earlier stage of adoption, although operators in South Africa and Nigeria are exploring autonomous network approaches. Huawei documented Level 4 autonomous network deployments with MTN in South Africa and MasOrange in Spain during 2025. These regional differences create varied opportunities for suppliers, ranging from foundational provisioning tools to broader intent-based orchestration platforms.
- Cisco Systems, Inc.
- Hewlett Packard Enterprise Company
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- Ciena Corporation
- IBM Corporation
- Arista Networks, Inc.
- Extreme Networks, Inc.
- VMware by Broadcom
- Amdocs Limited
- Netcracker Technology Corporation
- Oracle Corporation
- NEC Corporation
- Red Hat, Inc.
- Forward Networks, Inc.
- NetBrain Technologies, Inc.
- Itential, Inc.
- Gluware, Inc.
- BackBox Software Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Hybrid and Multicloud Network Complexity
- 4.2.2 AI-Driven Predictive Operations and Network Analytics
- 4.2.3 Expansion of 5G, Network Slicing, and Programmable Connectivity
- 4.2.4 Demand for Zero-Touch Provisioning and Lower Operational Costs
- 4.2.5 Network-as-Code Monetization by Communications Service Providers
- 4.2.6 Trustworthy Agentic Automation With Digital Twin Validation
- 4.3 Market Restraints
- 4.3.1 High Integration Costs Across Legacy and Multivendor Environments
- 4.3.2 Shortage of Network Automation and AI Operations Skills
- 4.3.3 Limited Explainability and Governance of Autonomous Changes
- 4.3.4 Data Quality and State-Synchronization Gaps Across Operational Systems
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Hardware-Embedded Automation
- 5.1.3 Services
- 5.2 By Deployment
- 5.2.1 Cloud
- 5.2.2 On-Premises
- 5.2.3 Hybrid
- 5.3 By Network Infrastructure
- 5.3.1 Physical Network Infrastructure
- 5.3.2 Virtual Network Infrastructure
- 5.3.3 Cloud-Native Network Infrastructure
- 5.3.4 Hybrid Network Infrastructure
- 5.4 By End User
- 5.4.1 Communications Service Providers
- 5.4.1.1 Mobile Network Operators
- 5.4.1.2 Fixed-Line Operators
- 5.4.1.3 Cable and Broadband Providers
- 5.4.1.4 Internet Service Providers
- 5.4.2 Enterprises
- 5.4.2.1 Banking, Financial Services, and Insurance
- 5.4.2.2 Manufacturing
- 5.4.2.3 Healthcare
- 5.4.2.4 Energy and Utilities
- 5.4.2.5 Government and Public Sector
- 5.4.2.6 Retail and E-Commerce
- 5.4.2.7 Media and Entertainment
- 5.4.2.8 Transportation and Logistics
- 5.4.3 Managed Service Providers and Cloud Service Providers
- 5.4.1 Communications Service Providers
- 5.5 By Organization Size
- 5.5.1 Large Enterprises
- 5.5.2 Small and Medium-Sized Enterprises
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Cisco Systems, Inc.
- 6.4.2 Hewlett Packard Enterprise Company
- 6.4.3 Huawei Technologies Co., Ltd.
- 6.4.4 Telefonaktiebolaget LM Ericsson
- 6.4.5 Nokia Corporation
- 6.4.6 Ciena Corporation
- 6.4.7 IBM Corporation
- 6.4.8 Arista Networks, Inc.
- 6.4.9 Extreme Networks, Inc.
- 6.4.10 VMware by Broadcom
- 6.4.11 Amdocs Limited
- 6.4.12 Netcracker Technology Corporation
- 6.4.13 Oracle Corporation
- 6.4.14 NEC Corporation
- 6.4.15 Red Hat, Inc.
- 6.4.16 Forward Networks, Inc.
- 6.4.17 NetBrain Technologies, Inc.
- 6.4.18 Itential, Inc.
- 6.4.19 Gluware, Inc.
- 6.4.20 BackBox Software Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


