

|
시장보고서
상품코드
2155310
E-Commerce 라스트마일 배송 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)E-commerce Last-mile Delivery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
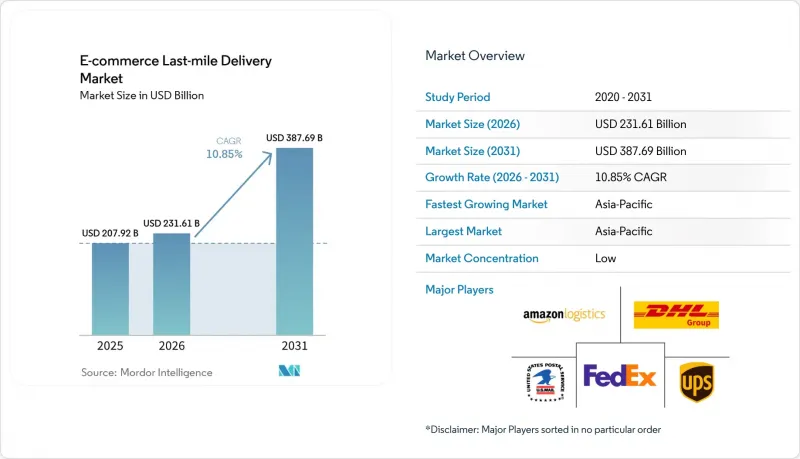
에 따르면 세계의 E-Commerce 라스트마일 배송 시장은 2025년에 2,079억 2,000만 달러 규모에 달하며, 2026년에는 2,316억 1,000만 달러로 확대하며, 2031년까지 3,876억 9,000만 달러에 달할 것으로 예측됩니다.
2026-2031년까지의 연평균 성장률(CAGR)은 10.85%에 달할 전망입니다.
전 세계 E-Commerce 라스트 마일 배송 시장은 도시 지역의 소포 밀도 증가, 당일 배송 인프라의 신속한 구축, 그리고 배송 사업자 네트워크 전반에 걸친 경로 최적화 툴의 보급 확대에 힘입어 성장세를 보이고 있습니다. 이 보고서는 배송 유형(표준, 당일, 익일), 배송 모델(B2C, B2B, C2C), 도시 등급(Tier 1, Tier 2, 기타), 제품 유형(식품 및 음료, 퍼스널 케어, 패션·라이프스타일, 가구, 기타) 및 지역(북미, 남미, 아시아태평양, 유럽, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
글로벌 E-Commerce 라스트 마일 배송 시장의 동향 및 인사이트
도시 회랑에서의 E-Commerce 주문 밀도 증가
도시 지역에서 주문이 집중되는 추세가 가속화됨에 따라 전 세계 E-Commerce 라스트마일 배송 시장에서는 1회당 배송 비용이 감소하고 있습니다. 배송 경로가 밀집되어 있으며, 차량 가동률이 향상되고, 배송 범위가 좁은 지역에서의 경로 계획 예측 정확도가 높아집니다. 인도의 퀵 커머스 플랫폼은 2026년 초까지 약 1,900개의 다크 스토어를 운영 중이며, 그 수는 연말까지 5,000개를 넘어설 것으로 예측되었습니다. 이러한 네트워크에서는 10-15분 이내에 주문을 처리하므로 소매업체에게는 기존의 허브 앤 스포크(hub-and-spoke) 모델이 아닌, 초지역 밀착형 주문 처리 능력이 요구되고 있습니다. 2026년 5월 아마존이 ‘Amazon Supply Chain Services’를 출범시킨 것은 대형 운송업체들이 현재 물류 네트워크를 외부 브랜드와 자사 소매 사업 모두에 대응할 수 있는 상용 제품으로 인식하고 있음을 보여줍니다. 전 세계 E-Commerce 라스트 마일 배송 시장에서 이러한 변화는 여전히 기존 비용 구조에 의존하고 있으며 네트워크 재설계가 지연되고 있는 운송 회사들에 대한 압박을 가중시키고 있습니다.
당일·익일 배송 서비스 보급률
전 세계 E-Commerce 라스트 마일 배송 시장에서 많은 도시 지역에서는 당일·익일 배송이 프리미엄 옵션에서 표준적인 기대치로 변화하고 있습니다. 이러한 변화로 인해 운송업체들은 재고를 최종사용자와 더 가까운 곳에 배치하고, 배송 시간대 관리를 더욱 엄격히 할 수밖에 없게 되었습니다. 아라멕스는 2025년 4월, Shipsy사와 마스터 서비스 계약을 체결하고, AI를 활용한 경로 최적화, 관할 구역 관리 및 시간대 관리 툴을 도입하여 당일 배송 서비스 확대를 추진하고 있습니다. 가장 큰 수요는 배송비보다 긴급성이 더 중요시되는 사용 사례, 특히 식품, 반품 및 정기 구독형 카테고리에서 발생하고 있습니다. Geopost사의 보고서에 따르면 2025년 유럽 8개국에서 온도 관리 운송 처리량은 11% 증가했으며, 이는 신선 식품 및 민감한 화물의 신속한 배송이 얼마나 중요한지를 지원합니다. 전 세계 E-Commerce 라스트 마일 배송 시장에서 배송 속도 향상은 더 이상 단순한 서비스 업그레이드가 아니라, 네트워크 설계의 기본 원칙으로 자리 잡고 있습니다.
도시 지역의 도로변 접근 제한 및 배송 시간대 부족
도시 지역의 접근 규제로 인해 인구 밀도가 높은 도심부에서 E-Commerce 라스트 마일 배송을 수익성 있게 확대하기가 어려워지고 있습니다. 저배출 구역, 배송 시간대 제한, 차량 대수 제한은 배송 경로의 복잡성을 가중시키고 배송의 유연성을 저하시킵니다. 2026년 Springer Nature가 도시 지역의 라스트 마일 배송 경로에 대해 실시한 연구에 따르면 제로 배출 구역의 시행으로 인해 사업자들은 전기화를 통한 비용 절감 효과를 충분히 실현하기도 전에 제한된 경로에 전기자동차 차량군을 배정해야 할 수도 있는 것으로 나타났습니다. 이로 인해 여러 관할 구역에서 여전히 혼합 차량을 운용하고 있는 사업자에게는 초기 단계부터 자본 부담이 발생하게 됩니다. 이 문제는 충전 시설 접근성, 갓길 공간, 지역별 운영 규정이 도시마다 다를 경우 더욱 심각해집니다. 전 세계 E-Commerce 라스트 마일 배송 시장에서 소포 수요가 견고함에도 불구하고 이러한 마찰이 서비스의 유연성을 제한하고 있습니다.
부문 분석
2025년, 표준 배송은 전 세계 E-Commerce 라스트 마일 배송 시장 점유율의 58.20%를 차지하고 있으며, 이는 가격에 민감한 소비자와 대량 발송을 하는 화주들이 여전히 예측 가능하고 저렴한 배송 시간대를 중시하고 있음을 보여줍니다. 표준 배송의 처리량은 네트워크 전체의 가동률을 지원하는 밀도를 가져다주기 때문에 전 세계 E-Commerce 라스트 마일 배송 시장은 여전히 이 기반에 의존하고 있습니다. 표준 서비스는 배송의 긴급성이 낮고, 화물량이 많거나 시간적 제약이 완만한 경우에 특히 중요한 역할을 합니다. 익일 배송은 서비스 범위에서 중간 위치를 계속 차지하고 있으며, 배송에 대한 기대치가 정착된 점과 교외로의 배송망 확대와 같은 혜택을 누리고 있습니다.
당일 배송은 2031년까지 연평균 성장률(CAGR) 14.30%로 확대될 것으로 예측되며, 이러한 성장을 위해서는 최종 고객으로부터 단거리 범위 내에 재고를 배치해야 합니다. 따라서 운송 사업자는 단순히 장거리 운송 능력을 늘리는 것뿐만 아니라, 다크 스토어와 마이크로 풀필먼트 거점, 그리고 더욱 스마트한 배차 시스템의 도입이 요구됩니다. 아라멕스는 2025년 4월, 당일 배송 서비스 확장을 지원하기 위해 Shipsy사의 AI를 활용한 관할 구역 및 경로 최적화 툴을 도입하여 이 과제에 대응했습니다. 지오포스트의 유럽내 ‘자택 이외’ 처리량은 2025년에 31% 증가했습니다. 이는 소포 수령점이나 사물함이, 그렇지 않았다면 비용이 많이 드는 문 앞 배송이 필요했을 수요의 일부를 흡수하고 있음을 보여줍니다. 이러한 수요 완화 효과는 중요합니다. 당일 배송 네트워크는 수익성을 유지하기 위해 높은 가동률을 필요로 하며, 자택 이외의 수령 옵션은 서비스 속도와 배송 비용 절감 간의 균형을 맞추는 데 도움이 되기 때문입니다.
2025년, 전 세계 E-Commerce 라스트마일 배송 시장 규모의 66.56%를 B2C가 차지했으며, 이는 소매업체, 패션 플랫폼, 가전제품 판매업체가 시장 전체의 배송 경로 밀도를 높이는 데 중심적인 역할을 하고 있음을 반영합니다. 전 세계 E-Commerce 라스트 마일 배송 시장의 소비자 부문은 여전히 대부분의 운송업체 운영률 모델의 기반이 되는 소포 흐름입니다. 또한 각 브랜드가 옴니채널 및 신속 배송 모델을 지원하는 소규모의 분산된 주문 처리 거점을 확충함에 따라 B2B 처리량도 증가하고 있습니다. Vinted, Poshmark, Shopee와 같은 플랫폼은 소량이지만 반복적으로 이루어지는 개인 대상 발송을 대량으로 발생시키기 때문에 이러한 추세에 해당합니다.
C2C는 2031년까지 연평균 성장률(CAGR) 16.97%로 성장할 것으로 예측되며, 전 세계 E-Commerce 라스트 마일 배송 시장에서 가장 뚜렷한 성장 궤도 중 하나입니다. 이러한 소포는 일반적으로 가볍고 크기가 표준화되어 있으며, 수작업이 많이 필요한 배송 모델보다 주택이나 외출지에서의 수거 네트워크에 더 적합합니다. 따라서 C2C는 배송 실패율을 낮추고 배송 효율을 높이는 사물함 및 택배함 시스템과 구조적으로 잘 어울린다고 할 수 있습니다. B2B의 경우 눈에 잘 띄지 않는 물품이나 분산된 보관 장소로의 보충에는 기존의 일괄 보충보다 빈도가 높고 시간적 제약이 있는 운송이 필요하므로 그 중요성이 높아지고 있습니다.
지역별 분석
2025년, 아시아태평양은 전 세계 E-Commerce 라스트 마일 배송 시장 점유율의 38.41%를 차지하며, 2031년까지 연평균 성장률(CAGR)이 11.93%로 가장 빠르게 성장하고 있는 지역이기도 합니다. 전 세계 E-Commerce 라스트 마일 배송 시장은 아시아태평양에서 특히 활기를 띠고 있으며, 규모와 성장이 상반된 방향으로 나아가는 것이 아니라 서로를 보완하고 있습니다. 중국의 주요 물류 사업자들은 국내 사업 모델을 동남아시아, 유럽, 북미 및 남미로 확대하고 있으며, 이를 통해 기존에 느리고 파편화되어 있던 배송 시스템이 가졌던 역사적 우위를 축소시키고 있습니다. Cainiao는 2026년 초 미국-멕시코 간 무역 노선을 개설하고, 일본에 물류 기술 전문 사무소를 설립하는 한편, 광둥성의 사업 거점에 창고용 로봇 ‘ZeeBot’을 도입했습니다. 호주 우정공사(Australia Post)는 2026년 7월부터 ‘주문형 당일 배송 서비스’를 68개 우편번호 구역에 걸쳐 있는 372개의 새로운 교외 지역으로 확대했습니다. 이는 아시아태평양의 지역 전략이 단순히 인구 밀도가 높은 대도시권을 대상으로 하는 데 그치지 않고, 유연한 서비스 모델이 필요한 광활한 지역까지 포괄하고 있음을 보여줍니다.
북미는 여전히 매우 중요한 사업 거점이며, 이 지역의 글로벌 E-Commerce 라스트마일 배송 시장은 협업과 직접적인 경쟁을 통해 재편되고 있습니다. 미국 우정공사(USPS)는 저밀도 배송 경로를 모두 중복하지 않으면서 전국적인 광범위한 커버리지를 추구하는 민간 운송업체들에게 공유형 라스트 마일 인프라로서 점점 더 중요한 역할을 수행하고 있습니다. DHL eCommerce는 2026년 5월, USPS와 100억 달러가 넘는 가치의 다년 독점 계약을 체결하여 41,550개 이상의 우편번호(ZIP 코드) 및 1억 7,000만 개의 배송 거점에 대한 라스트 마일 배송을 담당하게 되었습니다. 캐나다 우정공사(Canada Post)는 2026년 4월, 다년간 걸친 변혁을 위한 준비 작업을 시작했습니다. 여기에는 2026년 말 또는 2027년 초에 약 13만 6,000건의 주소에 대해 개별 배송에서 공동 우편함으로의 전환을 계획하는 것이 포함됩니다. 이러한 움직임은 북미의 사업자들이 모든 노선에서 단일 소유 구조에 의존하기보다는 하이브리드 모델을 통해 서비스 범위, 비용, 배송 밀도의 균형을 맞추고 있음을 보여줍니다.
유럽은 전 세계 E-Commerce 라스트 마일 배송 시장에서 가장 다층적인 경쟁 구도를 보이고 있으며, 범유럽 통합 사업자, 각국의 우편 사업자, 그리고 중국에서 진출한 신규 기업이 동일한 소포 수요를 놓고 경쟁하고 있습니다. 페덱스가 2026년 2월 컨소시엄과 제휴하여 InPost를 인수한 움직임은, 유럽 전역의 가정용 소포 사업의 수익성을 로커 인프라와 더욱 밀접하게 연계하기 위한 것이었습니다. 지오포스트의 네트워크는 2025년에 15만 곳의 소포 숍 및 사물함을 돌파했는데, 이는 ‘자택 외 배송’이 해당 지역의 비즈니스 모델에 얼마나 강력하게 통합되어 있는지를 보여줍니다. 중동 및 남미는 절대 수치상으로는 여전히 규모가 작습니다. 하지만 서비스 모델이 현지 인프라 상황에 적응된다면, 도시 지역에서의 급속한 보급과 국경을 초월한 수요가 네트워크 확장을 지원할 수 있으므로, 두 지역은 향후 성장에 있으며, 중요합니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요와 E-Commerce 물류에서 라스트마일 배송의 역할
- E-Commerce 지출 동향
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 규제 프레임워크
- 밸류체인 및 유통 채널 구조 분석
- 기술 혁신 전망
- Porter's Five Forces 분석
- E-Commerce에서 라스트마일 배송 요건 변천
- 가격결정과 비용 구조의 분석
- 소비자의 행동과 배송 선호에 관한 분석
- 지속가능 배송 솔루션과 그린 물류 구상
- 지정학적 이벤트가 공급망의 변화에 미치는 영향
제5장 시장 규모와 성장 예측(금액, 2026-2031년)
- 딜리버리 유형별
- 제공 모델별
- 도시 Tier별
- 제품 유형별
- 지역·국가별
- 북미
- 미국
- 캐나다
- 멕시코
- 남미
- 브라질
- 페루
- 칠레
- 아르헨티나
- 기타 남미 국가
- 아시아태평양
- 중국
- 일본
- 인도
- 한국
- 호주
- 동남아시아
- 기타 아시아태평양 국가
- 유럽
- 영국
- 독일
- 프랑스
- 스페인
- 이탈리아
- 베네룩스(벨기에, 네덜란드, 룩셈부르크)
- 북유럽 국가(덴마크, 핀란드, 아이슬랜드, 노르웨이, 스웨덴)
- 기타 유럽 국가
- 중동 및 아프리카
- 아랍에미리트
- 사우디아라비아
- 남아프리카공화국
- 나이지리아
- 기타 중동 및 아프리카 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 주요 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Amazon Logistics
- United Parcel Service(UPS)
- FedEx Corporation
- DHL Group
- United States Postal Service(USPS)
- Geopost(DPDgroup)
- GLS Group
- JD Logistics
- SF Express
- Cainiao Network
- Yamato Holdings
- J&T Express
- Delhivery
- Aramex
- Ninja Van
- Australia Post
- Canada Post
- Poste Italiane
- Sagawa Express
- Blue Dart Express
- InPost SA
- XpressBees
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the global e-commerce last-mile delivery market was valued at USD 207.92 billion in 2025 and is expected to grow to USD 231.61 billion in 2026, reaching USD 387.69 billion by 2031, at a CAGR of 10.85% over 2026-2031.
The global e-commerce last-mile delivery market is gaining momentum from higher parcel density in urban corridors, faster same-day infrastructure rollout, and wider adoption of route optimization tools across carrier networks. This report is Segmented by Delivery Type (Standard, Same-Day, and Next-Day), by Delivery Model (B2C, B2B, and C2C), by City Tier (Tier 1, Tier 2, and More), by Product Type (Foods and Beverages, Personal Care, Fashion and Lifestyle, Furniture, and More), and by Geography (North America, South America, Asia-Pacific, Europe, and MEA). The Market Forecasts are Provided in Terms of Value (USD).
Global E-commerce Last-mile Delivery Market Trends and Insights
E-Commerce Order Density Growth in Urban Corridors
Rising order concentration in cities is lowering per-stop delivery cost in the global e-commerce last-mile delivery market. Dense routes improve vehicle utilization and make route planning more predictable across short delivery radii. India's quick-commerce platforms operated nearly 1,900 dark stores by early 2026, and the count was projected to exceed 5,000 by the end of the year. Those networks process orders within 10-15 minutes, which means retailers need hyper-local fulfillment capacity rather than a conventional hub-and-spoke model. Amazon's May 2026 launch of Amazon Supply Chain Services shows that large carriers now view logistics networks as commercial products that can serve both outside brands and captive retail volume. In the global e-commerce last-mile delivery market, this change is raising the pressure on carriers that still rely on legacy cost structures and slower network redesign.
Same-Day and Next-Day Service Penetration
Same-day and next-day delivery have moved from premium options to standard expectations in many urban markets within the global e-commerce last-mile delivery market. That shift is forcing carriers to move inventory closer to end users and tighten control over delivery time windows. Aramex signed a master services agreement with Shipsy in April 2025 to deploy AI-powered route optimization, territory management, and time-slot tools for its same-day service rollout. The strongest pull is coming from use cases where urgency matters more than shipping price, especially food, returns, and refill-driven categories. Geopost reported 11% growth in temperature-controlled activity across 8 European countries in 2025, which supports the role of fast delivery in perishable and sensitive shipments. In the global e-commerce last-mile delivery market, faster delivery is no longer only a service upgrade; it is becoming a network design rule.
Urban Curb Access Constraints and Delivery Slot Scarcity
Urban access rules are making it harder to scale e-commerce last-mile delivery profitably in dense city centers. Low-emission zones, restricted time windows, and vehicle limits raise route complexity and reduce delivery flexibility. A 2026 Springer Nature study on urban last-mile routing showed that Zero Emission Zone enforcement can force operators to dedicate electric vehicle fleets to restricted routes before the cost savings of electrification are fully realized. That creates a front-loaded capital burden for fleets that still operate mixed vehicle bases across several jurisdictions. The issue is more severe where charging access, curb space, and local operating rules change from one city to another. In the global e-commerce last-mile delivery market, these frictions are limiting service flexibility even when parcel demand remains strong.
Other drivers and restraints analyzed in the detailed report include:
- Cross-Border Parcel Network Expansion
- Micro-Fulfillment and Dark Store Proximity Economics
- Driver Shortage and High Last-Mile Labor Intensity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Standard delivery accounted for 58.20% of the global e-commerce last-mile delivery market share in 2025, indicating that price-sensitive consumers and bulk-oriented shippers still value predictable, lower-cost service windows. The global e-commerce last-mile delivery market still depends on this base because standard volumes provide the density that supports broader network utilization. Standard service remains especially relevant when delivery urgency is low, and parcel baskets are larger or less time-sensitive. Next-day delivery continues to sit at the midpoint of the service spectrum, benefiting from normalized delivery expectations and expanding suburban fulfillment coverage.
Same-day delivery is projected to expand at a 14.30% CAGR through 2031, and that growth requires inventory to be placed within a short operating radius of the end customer. Carriers, therefore, need dark stores, micro-fulfillment nodes, and smarter dispatching rather than only more long-haul capacity. Aramex addressed this in April 2025 by deploying Shipsy's AI-powered territory and route optimization tools to support its same-day product rollout. Geopost's out-of-home volumes in Europe grew 31% in 2025, indicating that parcel shops and lockers are taking a share of the demand that would otherwise require costly doorstep service. That moderation effect matters because same-day networks need high utilization to remain profitable, and out-of-home options help balance service speed with delivery cost discipline.
B2C accounted for 66.56% of the global e-commerce last-mile delivery market size in 2025, reflecting the central role of retailers, fashion platforms, and electronics sellers in building route density across the market. The consumer side of the global e-commerce last-mile delivery market remains the foundational parcel flow on which most carrier utilization models are built. B2B volumes are also rising as brands replenish smaller and more distributed fulfillment nodes that support omnichannel and fast-delivery models. Platforms such as Vinted, Poshmark, and Shopee fit this pattern because they generate large volumes of small, repeat individual shipments.
C2C is projected to grow at a 16.97% CAGR through 2031, giving it one of the clearest expansion paths in the global e-commerce last-mile delivery market. These parcels are usually light, dimensionally standardized, and suited to residential or out-of-home collection networks rather than heavy-touch delivery models. That makes C2C structurally compatible with locker and parcel shop systems that lower failed delivery rates and increase stop efficiency. B2B, while less visible, is also becoming more important because replenishment to distributed storage locations requires more frequent, time-sensitive movement than traditional bulk restocking.
Complete Report Scope:
- By Delivery Type
- Standard Delivery
- Same-Day Delivery
- Next-Day Delivery
- By Delivery Model
- Business-to-Consumer (B2C)
- Business-to-Business (B2B)
- Consumer-to-Consumer (C2C)
- By City Tier
- Tier 1
- Tier 2
- Tier 3 and Below
- By Product Type
- Foods and Beverages
- Personal and Household Care
- Fashion and Lifestyle (Accessories, Apparel, Footwear)
- Furniture
- Consumer Electronics and Household Appliances
- Other Products
- By Region/Country
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- South East Asia
- Rest of Asia-Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of the Middle East And Africa
- North America
Geography Analysis
Asia-Pacific accounted for 38.41% of the global e-commerce last-mile delivery market share in 2025 and is also the fastest-growing region, with a 11.93% CAGR through 2031. The global e-commerce last-mile delivery market is particularly dynamic in Asia-Pacific, where scale and growth reinforce each other rather than moving in opposite directions. China's leading logistics operators are extending their domestic operating models into Southeast Asia, Europe, and the Americas, thereby shrinking the historical advantage of slower, more fragmented delivery systems. Cainiao opened a United States-Mexico trade lane in early 2026 and set up a dedicated logistics technology office in Japan while deploying its ZeeBot warehouse robot in Guangdong operations. Australia Post expanded its On demand same-day service to 372 new suburbs across 68 postcodes from July 2026, demonstrating that regional strategy in Asia-Pacific also includes large geographies that need flexible service models rather than just dense metro playbooks.
North America remains a critical operating theater because the global e-commerce last-mile delivery market there is being reshaped through both collaboration and direct competition. The United States Postal Service is becoming increasingly central as shared final-mile infrastructure for private carriers seeking broad national coverage without duplicating every low-density route. DHL eCommerce signed an exclusive multi-year agreement worth more than USD 10 billion with USPS in May 2026, covering final-mile delivery to more than 41,550 ZIP Codes and 170 million delivery points. Canada Post began preliminary work on a multi-year transformation in April 2026, including plans to move approximately 136,000 addresses from door-to-door service to community mailboxes in late 2026 or early 2027. These moves show that North American players are balancing reach, cost, and delivery density through hybrid models rather than relying on a single ownership structure for every route.
Europe presents the most layered competitive landscape in the global e-commerce last-mile delivery market, as pan-European integrators, national postal systems, and Chinese entrants compete for the same parcel pools. FedEx's February 2026 move, in partnership with its consortium, to acquire InPost was designed to tie residential parcel economics more closely to locker infrastructure across Europe. Geopost's network passed 150,000 parcel shops and lockers in 2025, which shows how strongly out-of-home delivery is being built into the regional operating model. The Middle East and South America remain smaller in absolute terms. Still, both regions are important for future growth because fast urban adoption and cross-border demand can support network expansion when service models are adapted to local infrastructure realities.
- Amazon Logistics
- United Parcel Service (UPS)
- FedEx Corporation
- DHL Group
- United States Postal Service (USPS)
- Geopost (DPDgroup)
- GLS Group
- JD Logistics
- SF Express
- Cainiao Network
- Yamato Holdings
- J&T Express
- Delhivery
- Aramex
- Ninja Van
- Australia Post
- Canada Post
- Poste Italiane
- Sagawa Express
- Blue Dart Express
- InPost SA
- XpressBees
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview and Role of Last-Mile Delivery in E-Commerce Logistics
- 4.2 E-Commerce Spending Trends
- 4.3 Market Drivers
- 4.3.1 E-Commerce Order Density Growth in Urban Corridors
- 4.3.2 Same-Day and Next-Day Service Penetration
- 4.3.3 Cross-Border Parcel Network Expansion
- 4.3.4 Retailer-Owned Delivery Networks and Private Fleets
- 4.3.5 Delivery-Orchestration Software and Route Optimization Adoption
- 4.3.6 Micro-Fulfillment and Dark Store Proximity Economics
- 4.4 Market Restraints
- 4.4.1 Urban Curb Access Constraints and Delivery Slot Scarcity
- 4.4.2 Driver Shortage and High Last-Mile Labor Intensity
- 4.4.3 Failed Delivery, Return, and Reverse Logistics Costs
- 4.4.4 Residential Electrification and Depot Charging Readiness Gaps
- 4.5 Regulatory Framework
- 4.6 Value Chain and Distribution Channel Architecture Analysis
- 4.7 Technology Innovations Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Rivalry Among Competitors
- 4.9 Evolution of E-Commerce Last-Mile Delivery Requirements
- 4.10 Pricing and Cost Structure Analysis
- 4.11 Consumer Behavior and Delivery Preferences Analysis
- 4.12 Sustainable Delivery Solutions and Green Logistics Initiatives
- 4.13 Impact of Geo-Political Events on Supply Chain Shifts
5 Market Size and Growth Forecasts (Value, 2026-2031)
- 5.1 By Delivery Type
- 5.1.1 Standard Delivery
- 5.1.2 Same-Day Delivery
- 5.1.3 Next-Day Delivery
- 5.2 By Delivery Model
- 5.2.1 Business-to-Consumer (B2C)
- 5.2.2 Business-to-Business (B2B)
- 5.2.3 Consumer-to-Consumer (C2C)
- 5.3 By City Tier
- 5.3.1 Tier 1
- 5.3.2 Tier 2
- 5.3.3 Tier 3 and Below
- 5.4 By Product Type
- 5.4.1 Foods and Beverages
- 5.4.2 Personal and Household Care
- 5.4.3 Fashion and Lifestyle (Accessories, Apparel, Footwear)
- 5.4.4 Furniture
- 5.4.5 Consumer Electronics and Household Appliances
- 5.4.6 Other Products
- 5.5 By Region/Country
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Peru
- 5.5.2.3 Chile
- 5.5.2.4 Argentina
- 5.5.2.5 Rest of South America
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 South East Asia
- 5.5.3.7 Rest of Asia-Pacific
- 5.5.4 Europe
- 5.5.4.1 United Kingdom
- 5.5.4.2 Germany
- 5.5.4.3 France
- 5.5.4.4 Spain
- 5.5.4.5 Italy
- 5.5.4.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.5.4.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.5.4.8 Rest of Europe
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Nigeria
- 5.5.5.5 Rest of the Middle East And Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Geographic Presence, Products and Services, and Recent Developments)
- 6.4.1 Amazon Logistics
- 6.4.2 United Parcel Service (UPS)
- 6.4.3 FedEx Corporation
- 6.4.4 DHL Group
- 6.4.5 United States Postal Service (USPS)
- 6.4.6 Geopost (DPDgroup)
- 6.4.7 GLS Group
- 6.4.8 JD Logistics
- 6.4.9 SF Express
- 6.4.10 Cainiao Network
- 6.4.11 Yamato Holdings
- 6.4.12 J&T Express
- 6.4.13 Delhivery
- 6.4.14 Aramex
- 6.4.15 Ninja Van
- 6.4.16 Australia Post
- 6.4.17 Canada Post
- 6.4.18 Poste Italiane
- 6.4.19 Sagawa Express
- 6.4.20 Blue Dart Express
- 6.4.21 InPost SA
- 6.4.22 XpressBees
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


