

|
시장보고서
상품코드
2155611
아프리카의 5G 기술 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Africa 5G Technology - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
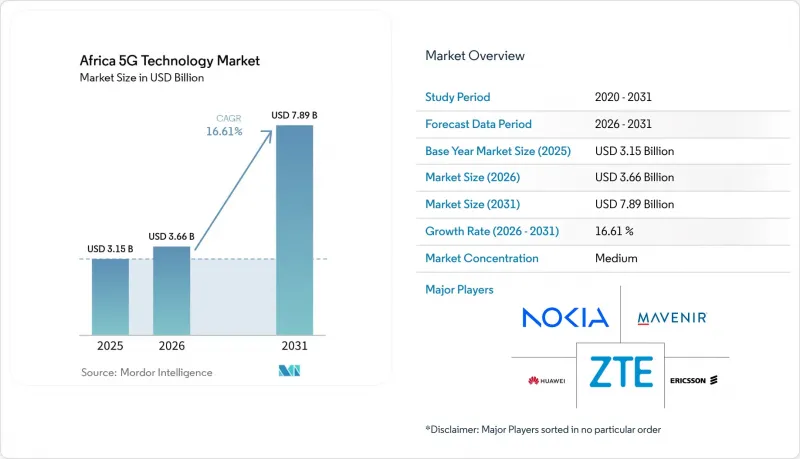
에 따르면 아프리카의 5G 기술 시장 규모는 2025년에 31억 5,000만 달러, 2026년에 36억 6,000만 달러에 달하고, 2031년까지 78억 9,000만 달러에 달할 것으로 예측되며, 2026년부터 2031년까지 CAGR 16.61%로 성장할 것으로 전망됩니다.
아프리카 5G 기술 시장의 동향 및 인사이트
고정형 광대역 보급률이 낮은 시장에서 4G에서 5G로의 비약적인 전환
아프리카의 일부 국가에서는 고정 광대역 보급률이 여전히 한 자릿수 초반에 머물러 있습니다. 그로 인해 가정과 기업에게 모바일 네트워크는 여전히 가장 현실적인 광대역 수단으로 남아 있습니다. 이러한 상황으로 인해 5G는 단순한 기존 모바일 요금제의 업그레이드가 아닌, 광대역의 대체 수단으로서 자리매김하고 있습니다. 사하라 이남 아프리카의 월간 모바일 데이터 트래픽은 2025년 2.8 엑사바이트에서 2031년까지 9.7 엑사바이트로 증가할 것으로 예측됩니다. 통신 사업자가 이 트래픽을 지속가능한 네트워크 비용으로 처리할 수 있을지는 주파수 대역 확보 여부에 달려 있습니다. 2025년, 모바일 기술은 아프리카 전역에서 2,400억 달러의 경제적 가치를 창출할 것으로 예상되며, 이는 해당 지역 GDP의 7.8%에 해당합니다.
고정 무선 접속(FWA)은 광섬유보다 더 신속하게 광대역 격차를 해소합니다.
FWA(고정 무선 접속)는 라스트 마일 토목 공사를 피함으로써 가정 연결에 필요한 비용과 시간을 절감할 수 있습니다. 이를 통해 아프리카의 5G 기술 시장은 광섬유 구축이 경제적으로 타당하지 않은 지역까지 현실적인 진출 경로를 개척할 수 있게 됩니다. 2025년 말까지 앙골라, 남아프리카공화국, 나이지리아, 케냐, 잠비아 등의 시장에서 25개 통신 사업자가 FWA 서비스 제공을 시작했습니다. MTN 그룹은 나이지리아 및 가나에서의 가정용 광대역 전략의 주요 축으로 FWA와 광섬유를 자리매김했습니다. Airtel Africa는 2026년 6월 결산 기준, 7개 시장에서 3,609곳의 5G 기지국을 가동하고 있었습니다. 이 회사가 수립한 2026년도 11억 달러 규모의 설비 투자 계획에서는 가정용 광대역이 주요 투자 분야로 지정되어 있습니다.
시장 간 주파수 대역의 세분화가 규모의 경제를 저해
주파수 대역에 관한 규정이 시장마다 다르기 때문에 장비 공급업체나 통신 사업자에게는 지역별 구축 비용이 높아지고 있습니다. 2025년 중반 시점에서 5G 주파수 대역 할당을 완료한 아프리카 국가는 16개국 미만이었습니다. 반면, 유럽 국가의 90% 이상이 5G 주파수 할당을 완료했습니다. 이집트는 2026년 초, 국내 4개 통신 사업자와 35억 달러 규모의 주파수 패키지 계약을 체결했습니다. 남아프리카공화국, 나이지리아, 이집트에서는 각국의 라이선스 제도, 가격 책정, 그리고 서비스 제공 범위에 관한 의무가 다릅니다. 이러한 차이로 인해 장비 표준화가 제한되고 있으며, 아프리카 5G 기술 시장 전체에서 지역 차원의 이점을 실현하는 데 지연이 발생하고 있습니다.
부문 분석
2025년, 아프리카 5G 기술 시장 점유율 중 하드웨어가 54.51%를 차지했습니다. 이는 매크로셀 기지국, 무선 액세스 네트워크 장비 및 안테나 시스템 구축을 반영한 것입니다. 에릭슨, 화웨이, 노키아, ZTE는 남아프리카공화국, 이집트, 나이지리아, 케냐에서 주요 장비 계약을 수주했습니다. 또한, 라이선싱 요건으로 인해 통신 사업자들은 정해진 커버리지 의무를 달성해야만 했습니다. MTN 남아프리카는 2025년 상반기에 듀얼 모드 5G 코어 업그레이드를 완료했습니다. 이 클라우드 네이티브 패킷 코어는 252만 개의 활성 세션과 40 Gbps의 실시간 트래픽을 처리했습니다. 따라서 하드웨어 수요는 소프트웨어 및 클라우드 코어에 대한 투자와 점점 더 밀접하게 연관되고 있습니다. 코어 기능이 클라우드 환경으로 이전되더라도 기지국 건설은 여전히 필요합니다. 커버리지 의무로 인해 장비 선정 자체뿐만 아니라 도입 시기도 중요해집니다. 이 때문에 현재의 구축 단계에서는 물리적 네트워크 자산이 여전히 중심적인 역할을 하고 있습니다.
서비스는 2026년부터 2031년까지 연평균 성장률(CAGR) 18.98%로 확대될 것으로 예측됩니다. 초기 커버리지가 확립된 후에는 매니지드 서비스, NaaS(Network as a Service) 계약, 그리고 시스템 통합의 중요성이 높아지고 있습니다. 통신 사업자는 이러한 체계를 활용하여 네트워크의 복잡성을 관리하고 운영 비용을 절감할 수 있습니다. 소프트웨어에는 코어 네트워크 기능, OSS/BSS 플랫폼, 네트워크 슬라이싱 도구 등이 포함됩니다. 그 도입은 SA 코어의 전개 속도에 좌우됩니다. 가나의 도매 네트워크에서는 소프트웨어 주도형 노키아 클라우드 코어가 채택된 반면, MTN 그룹은 남아프리카공화국, 짐바브웨, 앙골라, 우간다에서 클라우드 네이티브 현대화를 추진하고 있습니다. 이러한 전개는 아프리카 5G 기술 시장의 장기적인 서비스 및 소프트웨어 수요를 뒷받침하고 있습니다.
2025년 아프리카 5G 기술 시장 규모 중 75.89%를 Sub-6 GHz가 차지했습니다. 6 GHz 미만의 주파수 대역은 통신 사업자에게 커버리지와 용량의 현실적인 균형을 제공합니다. 이는 기지국을 매우 고밀도로 배치하지 않고도 광범위한 지역을 커버해야 하는 네트워크에서 중요합니다. 모로코는 2025년 7월, Maroc Telecom, Inwi, Orange Maroc에 3.5 GHz 대역의 주파수 면허를 부여했습니다. 이 면허 조건에 따라 2026년 말까지 인구의 45%를 커버해야 했습니다. ICASA의 ‘2026년 국가 무선 주파수 계획’에서는 6 GHz 이상 및 밀리미터파 대역의 용량을 모바일 용도로 지정하고 있습니다. 따라서 Sub-6 GHz 대역은 계속해서 초기 구축의 주요 계층으로 남을 것입니다. 이 주파수 대역은 더 높은 주파수의 대안에 비해 적은 수의 기지국으로도 전국적인 커버리지 목표를 달성할 수 있게 해줍니다.
하이브리드 구성은 2031년까지 연평균 성장률(CAGR) 19.12%로 확대될 것으로 예측됩니다. 이는 Sub-6 GHz를 통한 커버리지와 트래픽이 많은 지역에서의 밀리미터파 대역 용량을 결합한 것입니다. 이 접근 방식은 통신 사업자가 보다 광범위한 커버리지 기반을 구축한 후 그 중요성이 더욱 커질 가능성이 있습니다. Comsol사는 단일 60 MHz 주파수 블록을 사용하여 남아프리카공화국에서 SA 방식의 5G 코어 네트워크를 구축하고 있습니다. 2028년까지 수백만 가구에 서비스를 제공하겠다는 이 회사의 계획은 전용 통신 용량이 향후 하이브리드 구축을 뒷받침할 수 있음을 보여줍니다. 또한 항만, 광산, 산업 단지의 사설 네트워크에서도 단거리 및 고대역폭 통신 링크가 필요한 장소에서는 밀리미터파 시스템의 도입이 가능해집니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 5G 연혁과 진화
- 현재의 도입 주기(선구자, 채용자, 후발자)
- 업계 밸류체인 분석
- 규제 상황 및 정책 동향
- 기술 전망
- Porter's Five Forces 분석
- 5G와 Beyond 5G(6G로 가는 길)
- 거시경제 요인이 시장에 미치는 영향
제5장 시장 규모와 성장 예측
- 구성요소별
- 주파수대별
- 용도별
- 최종 이용 산업별
- 네트워크 아키텍처별
- 국가별
- 남아프리카공화국
- 나이지리아
- 이집트
- 케냐
- 기타 아프리카 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson(Ericsson)
- Nokia Corporation
- Qualcomm Incorporated
- Samsung Electronics Co., Ltd.
- ZTE Corporation
- Cisco Systems, Inc.
- Intel Corporation
- MediaTek Inc.
- NEC Corporation
- Fujitsu Limited
- CommScope Holding Company, Inc.
- Mavenir plc
- Parallel Wireless Inc.
- Juniper Networks, Inc.
- Sterlite Technologies Limited
- Aviat Networks, Inc.
- Radisys Corporation
- Ceragon Networks Ltd.
제7장 시장 기회와 향후 전망
KSM 26.10.30According to Mordor Intelligence, the Africa 5G technology market size is projected to be USD 3.15 billion in 2025, USD 3.66 billion in 2026, and reach USD 7.89 billion by 2031, growing at a CAGR of 16.61% from 2026 to 2031.
Africa 5G Technology Market Trends and Insights
Leapfrogging From 4G to 5G in Low-Fixed-Broadband Markets
Fixed broadband penetration remained in the low single digits in several African countries. Mobile networks have therefore remained the most viable broadband channel for households and businesses. This makes 5G a broadband alternative rather than only an upgrade to existing mobile plans. Sub-Saharan Africa's monthly mobile data traffic is projected to increase from 2.8 exabytes in 2025 to 9.7 exabytes by 2031. Spectrum availability will determine whether operators can carry this traffic at sustainable network costs. Mobile technologies generated USD 240 billion in economic value across Africa in 2025, equal to 7.8% of regional GDP.
Fixed Wireless Access Closing Broadband Gaps Faster Than Fiber
FWA can reduce the cost and time required to connect homes by avoiding last-mile civil works. This gives the Africa 5G technology market a practical route into areas where fiber deployment is difficult to justify. By late 2025, 25 operators had activated FWA services in markets including Angola, South Africa, Nigeria, Kenya, and Zambia. MTN Group identified FWA and fiber as the main pillars of its home broadband strategy in Nigeria and Ghana. Airtel Africa had 3,609 operational 5G sites across 7 markets in the quarter ended June 2026. Its USD 1.1 billion 2026 capital expenditure program identified home broadband as a primary investment area.
Spectrum Fragmentation Across Markets Slowing Scale Economics
Different spectrum rules make regional deployments more expensive for equipment suppliers and operators. Fewer than 16 African countries had completed 5G spectrum assignments by mid-2025. In comparison, more than 90% of European countries had allocated 5G spectrum. Egypt concluded a USD 3.5 billion spectrum package with its 4 operators in early 2026. National licensing, pricing, and coverage obligations differ across South Africa, Nigeria, and Egypt. These differences limit equipment standardization and delay the realization of regional-scale benefits across the African 5G technology market.
Other drivers and restraints analyzed in the detailed report include:
- Mobile Money, Fintech, and Enterprise Digitalization Raising Traffic Intensity
- Pan-African Neutral-Host and Infrastructure-Sharing Models Improving ROI
- High Energy and Diesel Reliance Raising Site Operating Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware accounted for 54.51% of Africa's 5G technology market share in 2025. This reflected the buildout of macro-cell sites, radio access network equipment, and antenna systems. Ericsson, Huawei, Nokia, and ZTE secured major equipment contracts in South Africa, Egypt, Nigeria, and Kenya. Licensing requirements also pushed operators to meet defined coverage commitments. MTN South Africa completed a dual-mode 5G core upgrade during the first half of 2025. The cloud-native packet core carried 2.52 million active sessions and 40 Gbps of live traffic. Hardware demand is therefore increasingly linked to software and cloud core investment. Site construction remains necessary even when core functions move into cloud environments. Coverage obligations make timing as important as the equipment selection itself. This keeps physical network assets central during the present rollout phase.
Services are projected to expand at an 18.98% CAGR from 2026 to 2031. Managed services, network-as-a-service contracts, and systems integration are becoming more important after initial coverage is established. Operators can use these arrangements to manage network complexity and contain operating costs. Software includes core network functions, OSS/BSS platforms, and network-slicing tools. Its adoption depends on the pace of SA core deployment. Ghana's wholesale network uses a software-driven Nokia cloud core, while MTN Group has pursued cloud-native modernization in South Africa, Zimbabwe, Angola, and Uganda. These deployments support longer-term service and software demand in the Africa 5G technology market.
Sub-6 GHz accounted for 75.89% of the Africa 5G technology market size in 2025. Frequencies below 6 GHz give operators a practical balance between coverage and capacity. This is important where networks must serve wide areas without very dense site deployment. Morocco licensed 3.5 GHz spectrum to Maroc Telecom, Inwi, and Orange Maroc in July 2025. The licenses required 45% population coverage by the end of 2026. ICASA's National Radio Frequency Plan 2026 also identified the upper 6 GHz and millimeter-wave capacity for mobile use. Sub-6 GHz should therefore remain the main initial rollout layer. The band supports national coverage targets with fewer base stations than higher-frequency alternatives.
Hybrid configurations are projected to expand at a 19.12% CAGR through 2031. They combine Sub-6 GHz coverage with millimeter-wave capacity in high-traffic locations. This approach may become more relevant once operators have established broader coverage footprints. Comsol is building an SA 5G core in South Africa using a single 60 MHz spectrum block. Its plan to serve millions of households by 2028 shows that the dedicated capacity can support later hybrid deployment. Private networks in ports, mines, and industrial sites can also introduce millimeter-wave systems where short-range, high-throughput links are justified.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Spectrum Band
- Sub-6 GHz
- mmWave
- Hybrid (Sub-6 GHz and mmWave)
- By Application
- Enhanced Mobile Broadband (eMBB)
- Fixed Wireless Access (FWA)
- Massive Machine-Type Communications (mMTC)
- Ultra-Reliable Low-Latency Communications (URLLC)
- By End-User Industry
- Consumer
- Manufacturing
- Healthcare
- Automotive
- Energy and Utilities
- Media and Entertainment
- Public Safety and Defense
- By Network Architecture
- Stand-Alone (SA)
- Non-Stand-Alone (NSA)
- By Country
- South Africa
- Nigeria
- Egypt
- Kenya
- Rest of Africa
List of Companies Covered in this Report:
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson (Ericsson)
- Nokia Corporation
- Qualcomm Incorporated
- Samsung Electronics Co., Ltd.
- ZTE Corporation
- Cisco Systems, Inc.
- Intel Corporation
- MediaTek Inc.
- NEC Corporation
- Fujitsu Limited
- CommScope Holding Company, Inc.
- Mavenir plc
- Parallel Wireless Inc.
- Juniper Networks, Inc.
- Sterlite Technologies Limited
- Aviat Networks, Inc.
- Radisys Corporation
- Ceragon Networks Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Leapfrogging From 4G to 5G in Low-Fixed-Broadband Markets
- 4.2.2 Fixed Wireless Access Closing Broadband Gaps Faster Than Fiber
- 4.2.3 Mobile Money, Fintech, and Enterprise Digitalization Raising Traffic Intensity
- 4.2.4 Pan-African Neutral-Host and Infrastructure-Sharing Models Improving ROI
- 4.2.5 Lower-Cost Sub-6 GHz Device Ecosystems Improving Consumer Adoption
- 4.2.6 Network Modernization Tied to Data Sovereignty and Edge-Ready Cloud Programs
- 4.3 Market Restraints
- 4.3.1 Spectrum Fragmentation Across Markets Slowing Scale Economics
- 4.3.2 High Energy and Diesel Reliance Raising Site Operating Costs
- 4.3.3 FX Volatility and Import Dependence Inflating CAPEX
- 4.3.4 Limited Fiber Backhaul and Rural Power Availability Delaying Standalone 5G Economics
- 4.4 5G Timeline and Evolution
- 4.5 Current Adoption Cycle (Forerunners, Adopters, and Laggards)
- 4.6 Industry Value Chain Analysis
- 4.7 Regulatory and Policy Landscape
- 4.8 Technological Outlook
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Suppliers
- 4.9.3 Bargaining Power of Buyers
- 4.9.4 Threat of Substitutes
- 4.9.5 Competitive Rivalry
- 4.10 5G and Beyond (6G Pathways)
- 4.11 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Spectrum Band
- 5.2.1 Sub-6 GHz
- 5.2.2 mmWave
- 5.2.3 Hybrid (Sub-6 GHz and mmWave)
- 5.3 By Application
- 5.3.1 Enhanced Mobile Broadband (eMBB)
- 5.3.2 Fixed Wireless Access (FWA)
- 5.3.3 Massive Machine-Type Communications (mMTC)
- 5.3.4 Ultra-Reliable Low-Latency Communications (URLLC)
- 5.4 By End-User Industry
- 5.4.1 Consumer
- 5.4.2 Manufacturing
- 5.4.3 Healthcare
- 5.4.4 Automotive
- 5.4.5 Energy and Utilities
- 5.4.6 Media and Entertainment
- 5.4.7 Public Safety and Defense
- 5.5 By Network Architecture
- 5.5.1 Stand-Alone (SA)
- 5.5.2 Non-Stand-Alone (NSA)
- 5.6 By Country
- 5.6.1 South Africa
- 5.6.2 Nigeria
- 5.6.3 Egypt
- 5.6.4 Kenya
- 5.6.5 Rest of Africa
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Huawei Technologies Co., Ltd.
- 6.4.2 Telefonaktiebolaget LM Ericsson (Ericsson)
- 6.4.3 Nokia Corporation
- 6.4.4 Qualcomm Incorporated
- 6.4.5 Samsung Electronics Co., Ltd.
- 6.4.6 ZTE Corporation
- 6.4.7 Cisco Systems, Inc.
- 6.4.8 Intel Corporation
- 6.4.9 MediaTek Inc.
- 6.4.10 NEC Corporation
- 6.4.11 Fujitsu Limited
- 6.4.12 CommScope Holding Company, Inc.
- 6.4.13 Mavenir plc
- 6.4.14 Parallel Wireless Inc.
- 6.4.15 Juniper Networks, Inc.
- 6.4.16 Sterlite Technologies Limited
- 6.4.17 Aviat Networks, Inc.
- 6.4.18 Radisys Corporation
- 6.4.19 Ceragon Networks Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


