

|
시장보고서
상품코드
2152969
UAV 시장 : 시스템, 최대 이륙 중량(MTOW), 플랫폼, 용도, 날개 유형, 제어, 거리, 컴퓨팅 기술, 지역별 - 세계 예측(-2031년)UAV Market by System, MTOW, Platform, Application, Wing Type, Control, Range, Compute Technology, Region - Global Forecast to 2031 |
||||||

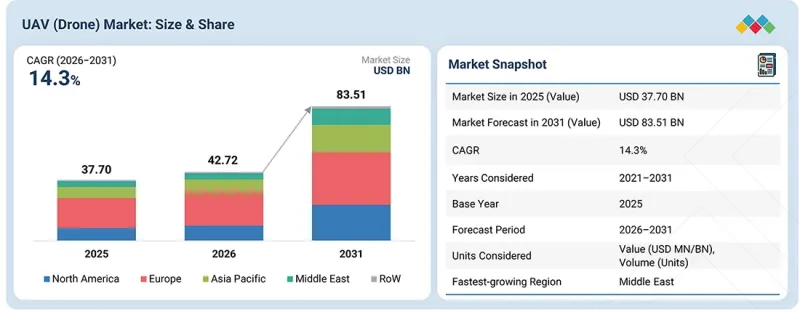
UAV(드론) 시장은 2026년 427억 2,000만 달러에서 2031년까지 835억 1,000만 달러에 달할 것으로 예상되며, 예측 기간 동안 연평균 성장률(CAGR) 14.3%로 성장할 것으로 전망됩니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 시스템, 용도, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양(APAC), 기타 지역(RoW) |
다양한 산업 분야에서 자율 운용의 활용이 증가하고 있습니다. 항공 모니터링 분야에서 실시간 데이터 수집의 중요성은 날로 커지고 있습니다. 인공지능(AI) 센서, 통신 시스템, 추진 기술 및 배터리 시스템의 개선을 통해 드론의 성능이 향상되고 있습니다. 이러한 기술 발전은 다양한 산업 분야에서 첨단 UAV(드론) 플랫폼의 더 광범위한 활용을 촉진하고 있습니다.
“2026년부터 2031년까지 물류·운송 부문이 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다.”
최종 이용 산업별로 보면 라스트 마일 배송, 화물 운송, 재고 모니터링, 창고 업무에서의 드론 활용 확대에 힘입어, 물류·운송 부문은 예측 기간 동안 UAV(드론) 시장에서 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다. 보다 신속한 배송 서비스와 효율적인 물류 업무에 대한 수요가 증가함에 따라, 기업들의 드론 활용 솔루션 도입이 가속화되고 있습니다. 자율 항법, 적재 능력, 실시간 추적 기술의 발전 또한 물류·운송 분야에서의 UAV(드론) 도입을 더욱 촉진하고 있습니다.
“2025년에는 고성능 연산 능력 및 AI 탑재 UAV 부문이 가장 큰 시장 점유율을 차지했습니다.”
연산 기술별로 보면 2025년에는 고연산 능력·AI 탑재 UAV 부문이 UAV(드론) 시장에서 가장 큰 점유율을 차지했습니다. 인간의 제어를 최소화하여 드론이 활용되는 사례가 늘어남에 따라, 이 부문은 성장을 이어가고 있습니다. 이러한 운용에서 실시간 데이터 처리가 중요해지고 있습니다. 인공지능과 기계 학습은 드론이 비행 중에 정보를 처리하는 것을 지원합니다. 또한 엣지 컴퓨팅을 통해 UAV는 기내에서 작업을 처리할 수 있게 됩니다. 이는 감시, 매핑, 점검, 국방 및 산업 용도에 유용합니다. 이러한 용도가 늘어남에 따라 고성능 연산 능력을 갖춘 UAV 플랫폼에 대한 수요도 높아지고 있습니다.
“2031년에는 유럽이 UAV(드론) 시장에서 가장 큰 점유율을 차지할 것으로 전망됩니다.”
지역별로 보면 국방 능력 강화에 대한 관심이 높아짐에 따라 2031년에는 유럽이 최대 시장 점유율을 차지할 것으로 예상됩니다. 유럽 국가들은 상황 인식 능력을 향상시키기 위해 감시, 정찰, 국경 감시 및 전술용 드론의 역량에 투자하고 있습니다. 자율 시스템, 인공지능, 그리고 첨단 센서의 도입으로 인해 국방 및 보안 분야에서의 UAV 활용은 더욱 확대되고 있습니다. 또한, 국내에서 개발된 드론 기술에 대한 수요 증가도 해당 지역의 시장 성장을 뒷받침하고 있습니다.
UAV(드론) 시장의 주요 참여자 프로필은 다음과 같습니다:
- 기업 유형별 : Tier 1 - 35%, Tier 2 - 45%, Tier 3 - 20%
- 직책별 : C레벨 임원 - 35%, 이사 - 25%, 기타 - 40%
- 지역별 : 북미 - 25%, 유럽 - 15%, 아시아태평양 - 45%, 중동 - 9%, 기타 지역 - 6%
조사 범위
본 시장 조사에서는 UAV(드론) 시장을 다양한 부문 및 하위 부문에 걸쳐 분석하고 있습니다. 그 목적은 각 지역의 시장 규모와 성장 잠재력을 추정하는 데 있습니다. 또한, 본 조사에서는 주요 시장 참여자에 대한 상세한 경쟁 분석도 제공하며, 여기에는 기업 개요, 제품 라인업, 최근 동향 및 전략적 시장 이니셔티브 등이 포함됩니다.
본 보고서를 구매해야 하는 이유
본 보고서는 시장을 선도하는 기업 및 신규 진입 기업에게 UAV(드론) 시장 전체의 매출 추정치를 제공합니다. 또한 이해관계자들이 경쟁 구도를 더 깊이 이해하고, 자사의 비즈니스를 보다 효과적으로 포지셔닝하며, 적절한 시장 진입 전략을 수립하기 위한 인사이트를 얻을 수 있도록 돕습니다. 더불어 본 보고서는 이해관계자들이 시장 역학을 이해하는 데 도움을 주며, 주요 시장 촉진요인, 시장 억제요인, 과제 및 기회에 대한 정보를 제공합니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다:
- 시장 역학 : 주요 촉진요인 분석(방위, 상업, 정부 용도에서의 자율형 UAV 수요 증가, BVLOS(시야 외) 운용의 급속한 확대 및 디지털 공역 통합), 제약요인(비행 지속 시간 제한 및 배터리 에너지 밀도 저하, 규제 분산 및 첨단 UAV 운용에 대한 접근 제한), 기회(다목적 용도를 위한 모듈형 UAV 플랫폼 개발, 드론 스웜 및 협업형 자율 운용의 부상), 그리고 과제(이종 UAV 생태계 간의 상호 운용성, 자율 의사결정의 신뢰성) 등 UAV(드론) 시장의 성장에 영향을 미치는 요인
- 시장 침투율 : 시장을 선도하는 주요 기업이 제공하는 시장에 대한 종합적인 정보
- 제품 개발/혁신 : 시장의 향후 기술, 연구개발 활동 및 신제품 출시에 대한 상세한 인사이트
- 시장 개발 : 다양한 지역의 수익성 높은 시장에 대한 종합적인 정보
- 시장 다각화 : 시장의 신제품, 미개척 지역, 최근 동향 및 투자에 관한 종합적인 정보
- 경쟁 분석 : 시장 내 주요 기업의 시장 점유율, 성장 전략, 제품 및 생산능력에 대한 상세한 평가
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- UAV(드론) 시장에서 사업자에게 매력적인 비즈니스 기회
- UAV(드론) 시장 : 용도별
- UAV(드론) 시장 : 최대 이륙 중량(MTOW)별
- UAV(드론) 시장 : 컴퓨팅 기술별
- UAV(드론) 시장 : 거리별
제4장 시장 개요
- 시장 역학
- 성장 촉진요인
- 성장 억제요인
- 기회
- 과제
- 미충족 수요와 미개척 분야
- 상호 연관된 시장 및 부문 간 기회
- 방위, 항공우주 제조 및 자율 시스템 생태계
- 물류, 디지털 인프라 및 자율 배송 생태계
- 농업, 로봇공학 및 정밀 농업 생태계
- Tier 1/2/3 기업들의 전략적 움직임
제5장 업계 동향
- 거시경제 전망
- GDP 동향 및 전망
- 세계 항공우주·방위 산업의 동향
- 세계 UAV(드론) 산업의 동향
- 가치사슬 분석
- 원자재 공급업체(약 15%)
- 부품 제조업체(약 10%)
- UAV OEM 및 시스템 통합업체(약 45%)
- UAV 서비스 제공업체 및 운영사(약 15%)
- 최종사용자(약 15%)
- 생태계 분석
- 제조업체
- 솔루션 및 서비스 제공업체
- 최종사용자
- 투자 및 자금 조달 시나리오
- 가격 분석
- 용도별 참고 가격 분석.
- 무역 분석
- 수입 시나리오(HS 코드 8806)
- 수출 시나리오(HS 코드 8806)
- 2026-2027년 주요 회의 및 행사
- 고객의 비즈니스에 영향을 미치는 동향 및 변화
- 사례 연구 분석
- SKYDIO와 미 육군 : 자율형 전술 무인항공기(UAV) 배치
- ZIPLINE과 르완다 : 자율형 의료 물품 배송
- DJI 농업 : 브라질에서의 정밀 농업
- PERCEPTO와 ICL DEAD SEA : 자율형 산업용 점검
- WING과 월마트 : 대규모 드론 배송
- 2025년 미국 관세의 영향
- 주요 관세율
- 가격에 미치는 영향 분석
- 국가 및 지역별 영향
- 최종 소비자에 미치는 영향
제6장 기술 발전, AI의 영향, 특허, 혁신 및 향후 응용
- 주요 기술
- AI를 활용한 자율 비행 및 임무 기술
- BVLOS, 탐지·회피(DAA), 및 UAS 교통 관리 기술
- 장거리 비행 추진 시스템 및 첨단 에너지 시스템
- 보완 기술
- 첨단 센싱 및 페이로드 기술
- 인공지능 및 자율 비행 기술
- 관련 기술
- 디지털 트윈 및 예측 유지보수 기술
- 엣지 컴퓨팅 및 5G/첨단 연결 기술
- 기술·제품 로드맵
- 기술 동향
- 고급 멀티센서 페이로드 및 이미징 기술
- 우수한 내결함성을 갖춘 위치 측정·항법·시간 동기화 기술
- 사이버 복원력이 뛰어난 UAV 아키텍처
- 첨단 항공전자 장비 및 실시간 비행 상태 모니터링
- 경량 첨단 소재 및 적층 제조
- 특허 분석
- 미래 응용 분야
- AI/생성형 AI의 영향
- 주요 사용 사례 및 시장 잠재력
- AI 도입 사례 연구
- 상호 연계되는 생태계와 시장 참여자에 미치는 영향
- 생성형 AI 도입에 대한 고객의 준비 현황
제7장 지속가능성과 규제 현황
- 지역별 규제 및 규정 준수
- 규제 당국, 정부 기관 및 기타 조직
- 업계 표준
- 지속가능성 추진 활동
- 친환경 애플리케이션
- 지속가능성이 규제 정책에 미치는 영향
- UAV(드론) 시장에 미치는 영향
- UAV(드론) 시장을 주도하는 규제 정책
- 인증, 표시 및 환경 기준
제8장 고객 동향과 구매 행동
- 의사결정 과정
- 구매 과정의 주요 이해관계자와 그 평가 기준
- 구매 과정의 주요 이해관계자
- 구매 기준
- 도입 장벽과 사내 과제
- 최종사용자의 충족되지 않은 요구
- 자율성 향상 및 BVLOS 운용 능력의 필요성
- 더 긴 비행 시간과 더 높은 탑재 능력의 필요성
- 비용 대비 효과가 높고, 안전하며, 통합된 UAV 시스템의 필요성
제9장 UAV(드론) 시장 : 플랫폼별(시장 규모 및 2031년까지의 전망)
- 국방
- 민간·상업
- 정부·공공안전
제10장 UAV(드론) 시장 : 시스템별(시장 규모 및 2031년까지의 전망)
- 기체
- 항공전자 장비
- 추진·동력 시스템
- 탑재체
제11장 UAV(드론) 시장 : 용도별(시장 규모 및 2031년까지의 전망)
- 군사
- 상업용
- 정부·법집행기관
- 민간용
제12장 UAV(드론) 시장 : 날개 유형별(시장 규모 및 2031년까지의 전망)
- 고정익
- 회전익
제13장 UAV(드론) 시장 : 인간 제어 아키텍처별(시장 규모 및 2031년까지의 전망)
- 휴먼-인-더-루프
- 휴먼 온 더 루프
- 휴먼 아웃 오브 더 루프
제14장 UAV(드론) 시장 : 최대 이륙 중량(MTOW)별(시장 규모 및 2031년까지의 전망)
- 2 kg 미만
- 2 KG-25 KG
- 25 KG-150 KG
- 150 KG-600 KG
- 600 KG-2,000 KG 미만
- 2,000 KG 이상
제15장 UAV(드론) 시장 : 거리별(시장 규모 및 2031년까지의 전망)
- 시야 내 비행(VLOS)(0.5 km 이하)
- 확장 가시거리 내(EVLOS)(0.5 km 초과 - 2 km)
- 시야 외(BVLOS)(2 km 초과)
제16장 UAV(드론) 시장 : 컴퓨팅 기술별(시장 규모 및 2031년까지의 전망)
- 표준 연산 능력을 갖춘 UAV
- 고성능 연산 능력/AI 탑재 UAV
제17장 UAV(드론) 시장 : 최종 이용 산업별(시장 규모 및 2031년까지의 전망)
- 국방, 보안, 법 집행
- 농업
- 물류·운송
- 에너지·공공사업
- 건설·광업
- 미디어·엔터테인먼트
- 보험
- 야생동물·임업, 환경 서비스
- 헬스케어·의료 서비스
- 교육·조사
- 레크리에이션
- 기타
제18장 UAV(드론) 시장 : 지역별(시장 규모 및 2031년까지의 전망)
- 북미
- 미국
- 캐나다
- 유럽
- 영국
- 독일
- 프랑스
- 이탈리아
- 폴란드
- 우크라이나
- 기타 유럽
- 아시아태평양
- 중국
- 일본
- 인도
- 호주
- 한국
- 기타 아시아태평양
- 중동
- 아랍에미리트
- 사우디아라비아
- 튀르키예
- 이스라엘
- 세계의 기타 지역
- 라틴아메리카
- 아프리카
제19장 경쟁 현황
- 주요 참여 기업의 전략/강점, 2021-2026년
- 수익 분석, 2021-2025년
- 시장 점유율 분석(2025년)
- 브랜드/제품 비교
- 기업 평가 및 재무 지표
- 기업 평가 매트릭스 : 주요 기업, 2025년
- 스타 기업
- 신흥 리더
- 광범위한 입지를 가진 기업
- 진출 기업
- 기업의 사업 전개
- 기업 평가 매트릭스 : 스타트업/중소기업, 2025년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹
- 경쟁 시나리오
- 제품 출시·개발
- 거래
- 기타 동향
제20장 기업 개요
- 주요 기업
- BAYKAR TECH
- DJI
- NORTHROP GRUMMAN
- ISRAEL AEROSPACE INDUSTRIES LTD.
- TELEDYNE TECHNOLOGIES INCORPORATED
- GENERAL ATOMICS
- LOCKHEED MARTIN CORPORATION
- BOEING
- AEROVIRONMENT, INC.
- TEXTRON INC.
- AIRBUS
- THALES
- ELBIT SYSTEMS LTD.
- LEONARDO S.P.A.
- AUTEL ROBOTICS
- 기타 주요 기업
- SHIELD AI
- QUANTUM-SYSTEMS GMBH
- ZIPLINE INTERNATIONAL INC.
- PERCEPTO LTD.
- FLYABILITY SA
- WINGTRA AG
- GARUDA AEROSPACE
- BRINC DRONES INC.
- ELROY AIR
- DRONAMICS GROUP LIMITED
제21장 조사 방법론
제22장 부록
KSM 26.10.26The UAV (drone) market is expected to reach USD 83.51 billion by 2031 from USD 42.72 billion in 2026, growing at a CAGR of 14.3% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Billion) |
| Segments | By System, Application and Region |
| Regions covered | North America, Europe, APAC, RoW |
The use of autonomous operations is increasing across different industries. Real-time data collection is becoming more crucial for aerial monitoring. Improvements in artificial intelligence (AI) sensors, communication systems, propulsion technologies, and battery systems are helping drones perform better. These technology improvements also support wider use of advanced UAV (drone) platforms across different industries.
"Logistics & transportation segment to grow at the highest CAGR between 2026 and 2031"
By end-use industry, the logistics & transportation segment is anticipated to record the highest CAGR in the UAV (drone) market during the forecast period, driven by the growing use of drones for last-mile delivery, cargo transport, inventory monitoring, and warehouse operations. Increasing demand for faster delivery services and efficient logistics operations is encouraging companies to adopt drone-based solutions. Advancements in autonomous navigation, payload capacity, and real-time tracking are further supporting the adoption of UAVs (drones) in logistics and transportation.
"High-compute/AI-enabled UAVs segment captured the largest market share in 2025"
By compute technology, the high-compute/AI-enabled UAVs segment accounted for the largest share of the UAV (drone) market in 2025. The segment is growing as more drones are used with less human control. Real-time data processing is becoming important for these operations. Artificial intelligence and machine learning help drones process information during flight. Edge computing also allows UAVs to handle tasks on board. This is useful for surveillance, mapping, inspection, defense, and industrial applications. As these uses increase, the demand for high-compute UAV platforms is also rising.
"Europe to account for the largest share of the UAV (drone) market in 2031"
By region, Europe is expected to hold the largest market share in 2031, due to the increasing focus on strengthening defense capabilities. European countries are investing in surveillance, reconnaissance, border monitoring, and tactical drone capabilities to improve situational awareness. The adoption of autonomous systems, artificial intelligence, and advanced sensors is further increasing the use of UAVs across defense and security applications. Growing demand for domestically developed drone technologies is also supporting the regional market growth.
The breakdown of profiles for primary participants in the UAV (drone) market is provided below:
- By Company Type: Tier 1 - 35%, Tier 2 - 45%, and Tier 3 - 20%
- By Designation: C-level Executives - 35%, Directors - 25%, and Others - 40%
- By Region: North America - 25%, Europe - 15%, Asia Pacific - 45%, Middle East - 9%, and RoW - 6%
The report profiles key players in the UAV (drone) market with their respective market ranking analysis. Prominent players profiled in this report are BAYKAR TECH (Turkiye), DJI (China), General Atomics (US), Northrop Grumman (US), and Israel Aerospace Industries (Israel). Apart from this, AeroVironment, Inc. (US), Elbit Systems Ltd. (Israel), Boeing (US), Airbus (Netherlands), and Textron Inc. (US), among others, are key companies operating in the market.
Research Coverage
This market study examines the UAV (drone) market across various segments and subsegments. It aims to estimate the market's size and growth potential in different regions. The study also provides a detailed competitive analysis of key market players, including their company profiles, product offerings, recent developments, and strategic market initiatives.
Reasons to Buy This Report
The report will assist market leaders and new entrants with estimates of the revenue figures for the overall UAV (drone) market. It will also enable stakeholders to understand the competitive landscape better and gain insights to position their businesses more effectively and develop appropriate go-to-market strategies. Additionally, the report will help stakeholders understand the market dynamics and provide information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Market Dynamics: Analysis of Key Drivers (Growing demand for autonomous UAVs across defense, commercial, and government applications, Rapid expansion of BVLOS operations and digital airspace integration), Restraints (Limited flight endurance and battery energy density, Regulatory fragmentation and limited access to advanced UAV operations), Opportunities (Development of modular UAV platforms for multi-mission applications, Rise in drone swarm and collaborative autonomous operations), and Challenges (Interoperability across heterogeneous UAV ecosystems, Reliability of autonomous decision-making) influencing the growth of the UAV (drone) market
- Market Penetration: Comprehensive information on the market offered by the top players in the market
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and product launches in the market
- Market Development: Comprehensive information about lucrative markets across varied regions
- Market Diversification: Exhaustive information about new products, untapped geographies, recent developments, and investments in the market
- Competitive Assessment: In-depth assessment of market share, growth strategies, products, and manufacturing capabilities of leading players in the market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 UAV (DRONE) MARKET SEGMENTATION & REGIONAL SNAPSHOT
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN UAV (DRONE) MARKET
- 3.2 UAV (DRONE) MARKET, BY APPLICATION
- 3.3 UAV (DRONE) MARKET, BY MTOW
- 3.4 UAV (DRONE) MARKET, BY COMPUTE TECHNOLOGY
- 3.5 UAV (DRONE) MARKET, BY RANGE
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing demand for autonomous unmanned aerial vehicles (UAVs) across defense, commercial, and government applications
- 4.2.1.2 Expansion of beyond visual line of sight (BVLOS) operations and digital airspace integration
- 4.2.1.3 Increasing defense modernization and adoption of unmanned systems
- 4.2.2 RESTRAINTS
- 4.2.2.1 Limited flight endurance and battery energy density
- 4.2.2.2 Regulatory fragmentation and limited access to advanced UAV operations
- 4.2.2.3 Increasing cybersecurity and supply chain security requirements
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Integration of UAVs with digital twins and predictive maintenance
- 4.2.3.2 Development of modular UAV platforms for multi-mission applications
- 4.2.3.3 Expansion of Drone-in-a-Box solutions for remote and continuous operations
- 4.2.3.4 Growth of drone swarm and collaborative autonomous operations
- 4.2.4 CHALLENGES
- 4.2.4.1 Interoperability across heterogeneous UAV ecosystems
- 4.2.4.2 UAV traffic management at high deployment density
- 4.2.4.3 Reliability of autonomous decision-making
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 DEFENSE, AEROSPACE MANUFACTURING, AND AUTONOMOUS SYSTEMS ECOSYSTEMS
- 4.4.2 LOGISTICS, DIGITAL INFRASTRUCTURE, AND AUTONOMOUS DELIVERY ECOSYSTEMS
- 4.4.3 AGRICULTURE, ROBOTICS, AND PRECISION FARMING ECOSYSTEMS
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 MACROECONOMIC OUTLOOK
- 5.1.1 GDP TRENDS AND FORECAST
- 5.1.2 TRENDS IN GLOBAL AEROSPACE AND DEFENSE INDUSTRY
- 5.1.3 TRENDS IN GLOBAL UAV (DRONE) INDUSTRY
- 5.2 VALUE CHAIN ANALYSIS
- 5.2.1 RAW MATERIAL SUPPLIERS (~15%)
- 5.2.2 COMPONENT MANUFACTURERS (~10%)
- 5.2.3 UAV OEMS AND SYSTEM INTEGRATORS (~45%)
- 5.2.4 UAV SERVICE PROVIDERS AND OPERATORS (~15%)
- 5.2.5 END USERS (~15%)
- 5.3 ECOSYSTEM ANALYSIS
- 5.3.1 MANUFACTURERS
- 5.3.2 SOLUTION AND SERVICE PROVIDERS
- 5.3.3 END USERS
- 5.4 INVESTMENT AND FUNDING SCENARIO
- 5.5 PRICING ANALYSIS
- 5.5.1 INDICATIVE PRICING ANALYSIS, BY APPLICATION.
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 8806)
- 5.6.2 EXPORT SCENARIO (HS CODE 8806)
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 SKYDIO AND US ARMY: AUTONOMOUS TACTICAL UAV DEPLOYMENT
- 5.9.2 ZIPLINE AND RWANDA: AUTONOMOUS HEALTHCARE DELIVERY
- 5.9.3 DJI AGRICULTURE: PRECISION FARMING IN BRAZIL
- 5.9.4 PERCEPTO AND ICL DEAD SEA: AUTONOMOUS INDUSTRIAL INSPECTION
- 5.9.5 WING AND WALMART: DRONE DELIVERY AT SCALE
- 5.10 IMPACT OF 2025 US TARIFFS
- 5.10.1 KEY TARIFF RATES
- 5.10.2 PRICE IMPACT ANALYSIS
- 5.10.3 IMPACT ON COUNTRY/REGION
- 5.10.3.1 US
- 5.10.3.2 Europe
- 5.10.3.3 Asia Pacific
- 5.10.4 IMPACT ON END USERS
- 5.10.4.1 Military
- 5.10.4.2 Commercial
- 5.10.4.3 Government & law enforcement
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 AI-ENABLED AUTONOMOUS FLIGHT AND MISSION TECHNOLOGY
- 6.1.2 BVLOS, DETECT-AND-AVOID (DAA), AND UAS TRAFFIC MANAGEMENT TECHNOLOGY
- 6.1.3 HIGH-ENDURANCE PROPULSION AND ADVANCED ENERGY SYSTEMS
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 ADVANCED SENSING AND PAYLOAD TECHNOLOGIES
- 6.2.2 ARTIFICIAL INTELLIGENCE AND AUTONOMOUS FLIGHT TECHNOLOGIES
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 DIGITAL TWIN AND PREDICTIVE MAINTENANCE TECHNOLOGY
- 6.3.2 EDGE COMPUTING AND 5G/ADVANCED CONNECTIVITY TECHNOLOGY
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.5 TECHNOLOGY TRENDS
- 6.5.1 ADVANCED MULTI-SENSOR PAYLOAD AND IMAGING TECHNOLOGY
- 6.5.2 RESILIENT POSITIONING, NAVIGATION, AND TIMING TECHNOLOGY
- 6.5.3 CYBER-RESILIENT UAV ARCHITECTURES
- 6.5.4 ADVANCED AVIONICS AND REAL-TIME FLIGHT HEALTH MONITORING
- 6.5.5 LIGHTWEIGHT ADVANCED MATERIALS AND ADDITIVE MANUFACTURING
- 6.6 PATENT ANALYSIS
- 6.7 FUTURE APPLICATIONS
- 6.8 IMPACT OF AI/GENERATIVE AI
- 6.8.1 TOP USE CASES AND MARKET POTENTIAL
- 6.8.2 CASE STUDIES OF AI IMPLEMENTATION
- 6.8.3 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.8.4 CLIENTS' READINESS TO ADOPT GENERATIVE AI
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 ECO-APPLICATIONS
- 7.3 IMPACT OF SUSTAINABILITY ON REGULATORY POLICIES
- 7.3.1 IMPACT ON UAV (DRONE) MARKET
- 7.3.2 REGULATORY POLICIES DRIVING UAV (DRONE) MARKET
- 7.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF END USERS
- 8.4.1 NEED FOR ENHANCED AUTONOMY AND BVLOS OPERATIONAL CAPABILITIES
- 8.4.2 NEED FOR LONGER ENDURANCE AND HIGHER PAYLOAD CAPACITY
- 8.4.3 NEED FOR COST-EFFECTIVE, SECURE, AND INTEGRATED UAV SYSTEMS
9 UAV (DRONE) MARKET, BY PLATFORM (MARKET SIZE & FORECAST TO 2031-USD MILLION)
- 9.1 INTRODUCTION
- 9.2 DEFENSE
- 9.2.1 SMALL
- 9.2.1.1 Growing adoption of small UAVs for surveillance, reconnaissance, and border monitoring
- 9.2.2 TACTICAL
- 9.2.2.1 Increasing adoption of tactical UAVs for intelligence and reconnaissance
- 9.2.3 STRATEGIC
- 9.2.3.1 MALE
- 9.2.3.1.1 Increasing demand for persistent long-endurance intelligence and surveillance
- 9.2.3.2 HALE
- 9.2.3.2.1 Growing need for persistent wide-area surveillance
- 9.2.3.1 MALE
- 9.2.1 SMALL
- 9.3 CIVIL & COMMERCIAL
- 9.3.1 SMALL
- 9.3.1.1 Growing adoption of small UAVs for commercial delivery, agriculture, and inspection
- 9.3.2 MEDIUM
- 9.3.2.1 Growing adoption of medium UAVs for high-capacity commercial operations
- 9.3.3 LARGE & VERY LARGE
- 9.3.3.1 Growing demand for heavy-lift UAVs for cargo, logistics, and industrial operations
- 9.3.1 SMALL
- 9.4 GOVERNMENT & PUBLIC SAFETY
- 9.4.1 GROWING ADOPTION OF UAVS FOR EMERGENCY RESPONSE AND PUBLIC SAFETY
10 UAV (DRONE) MARKET, BY SYSTEM (MARKET SIZE & FORECAST TO 2031-USD MILLION)
- 10.1 INTRODUCTION
- 10.2 AIRFRAMES
- 10.2.1 METALS & ALLOYS
- 10.2.1.1 Increasing demand for lightweight and high-strength metal structures
- 10.2.2 COMPOSITES
- 10.2.2.1 Increasing adoption of lightweight composite structures
- 10.2.3 OTHER MATERIALS
- 10.2.1 METALS & ALLOYS
- 10.3 AVIONICS
- 10.3.1 FLIGHT CONTROL SYSTEMS
- 10.3.1.1 More autonomous and reliable flight control changing UAV design priorities
- 10.3.2 NAVIGATION SYSTEMS
- 10.3.2.1 Growing demand for accurate and resilient navigation
- 10.3.3 SENSORS
- 10.3.3.1 Growing demand for smarter sensing capabilities
- 10.3.4 COMMUNICATION & DATA LINK SYSTEMS
- 10.3.4.1 Growing demand for reliable connectivity and expansion of BVLOS
- 10.3.5 OTHER AVIONICS
- 10.3.1 FLIGHT CONTROL SYSTEMS
- 10.4 PROPULSION & POWER SYSTEMS
- 10.4.1 ENGINES
- 10.4.1.1 Growing demand for high-endurance propulsion
- 10.4.2 ELECTRIC MOTORS & DRIVES
- 10.4.2.1 Growing demand for efficient electric propulsion
- 10.4.3 BATTERIES & ENERGY STORAGE SYSTEMS
- 10.4.3.1 Growing demand for longer flight endurance
- 10.4.4 MOTOR/ENGINE CONTROL ELECTRONICS
- 10.4.4.1 Growing demand for precise propulsion control
- 10.4.5 PROPELLERS & ROTORS
- 10.4.5.1 Growing focus on propulsion efficiency
- 10.4.6 OTHER PROPULSION & POWER COMPONENTS
- 10.4.1 ENGINES
- 10.5 PAYLOADS
- 10.5.1 EO/IR & IMAGING PAYLOADS
- 10.5.1.1 Growing demand for high-resolution aerial intelligence
- 10.5.2 RADAR PAYLOADS
- 10.5.2.1 Growing demand for all-weather detection
- 10.5.3 LIDAR PAYLOADS
- 10.5.3.1 Growing demand for accurate 3D mapping
- 10.5.4 CBRN DETECTION PAYLOADS
- 10.5.4.1 Growing demand for remote hazard detection
- 10.5.5 SIGINT & ELECTRONIC WARFARE PAYLOADS
- 10.5.5.1 Growing demand for electromagnetic spectrum awareness
- 10.5.6 COMMUNICATION RELAY PAYLOADS
- 10.5.6.1 Growing demand for flexible aerial connectivity
- 10.5.7 WEAPON & EFFECT PAYLOADS
- 10.5.7.1 Growing demand for modular mission effects
- 10.5.8 OTHER MISSION PAYLOADS
- 10.5.1 EO/IR & IMAGING PAYLOADS
11 UAV (DRONE) MARKET, BY APPLICATION (MARKET SIZE & FORECAST TO 2031-USD MILLION)
- 11.1 INTRODUCTION
- 11.2 MILITARY
- 11.2.1 ISR
- 11.2.1.1 Growing demand for persistent aerial intelligence
- 11.2.2 COMBAT OPERATIONS
- 11.2.2.1 Unmanned combat aerial vehicle (UCAV)
- 11.2.2.1.1 Growing demand for autonomous combat air capabilities
- 11.2.2.2 Loitering munitions
- 11.2.2.2.1 Growing demand for flexible precision capabilities
- 11.2.2.1 Unmanned combat aerial vehicle (UCAV)
- 11.2.3 LOGISTICS, DELIVERY & RESUPPLY
- 11.2.3.1 Growing demand for rapid and flexible aerial logistics
- 11.2.4 OTHER MISSION SUPPORT
- 11.2.1 ISR
- 11.3 COMMERCIAL
- 11.3.1 INFRASTRUCTURE INSPECTION & MAINTENANCE
- 11.3.1.1 Growing demand for faster asset assessment
- 11.3.2 SURVEYING, MAPPING & CONSTRUCTION
- 11.3.2.1 Growing demand for faster and more accurate site data
- 11.3.3 AGRICULTURE & FORESTRY OPERATIONS
- 11.3.3.1 Growing demand for precision field management
- 11.3.4 LOGISTICS, DELIVERY & TRANSPORTATION
- 11.3.4.1 Growing demand for faster last-mile movement
- 11.3.5 ENVIRONMENTAL & RESOURCE MONITORING
- 11.3.5.1 Growing demand for high-resolution environmental data
- 11.3.6 MEDIA, PHOTOGRAPHY & VIDEOGRAPHY
- 11.3.6.1 Growing demand for flexible aerial content creation
- 11.3.7 INDUSTRIAL & WAREHOUSE OPERATIONS
- 11.3.7.1 Growing demand for automated asset visibility
- 11.3.8 OTHER COMMERCIAL APPLICATIONS
- 11.3.1 INFRASTRUCTURE INSPECTION & MAINTENANCE
- 11.4 GOVERNMENT & LAW ENFORCEMENT
- 11.4.1 BORDER SECURITY & SURVEILLANCE
- 11.4.1.1 Growing demand for persistent border monitoring
- 11.4.2 PUBLIC SAFETY & DISASTER RESPONSE
- 11.4.2.1 Growing demand for faster emergency situational awareness
- 11.4.3 LAW ENFORCEMENT & POLICING
- 11.4.3.1 Growing adoption of real-time aerial support
- 11.4.4 SEARCH & RESCUE
- 11.4.4.1 Growing demand for rapid aerial search capabilities
- 11.4.5 MARITIME & COASTAL SURVEILLANCE
- 11.4.5.1 Growing demand for persistent coastal monitoring
- 11.4.6 ENVIRONMENTAL & RESOURCE PROTECTION
- 11.4.6.1 Growing demand for high-resolution environmental monitoring
- 11.4.7 OTHER GOVERNMENT APPLICATIONS
- 11.4.1 BORDER SECURITY & SURVEILLANCE
- 11.5 CONSUMER
- 11.5.1 PROSUMERS
- 11.5.1.1 Growing demand for professional-grade aerial content
- 11.5.2 HOBBYISTS
- 11.5.2.1 Growing interest in recreational and immersive flying
- 11.5.1 PROSUMERS
12 UAV (DRONE) MARKET, BY WING TYPE (MARKET SIZE & FORECAST TO 2031-USD MILLION)
- 12.1 INTRODUCTION
- 12.2 FIXED WING
- 12.2.1 CONVENTIONAL TAKE-OFF AND LANDING (CTOL)
- 12.2.1.1 Growing demand for persistent surveillance and long-range unmanned operations
- 12.2.2 SHORT TAKE-OFF AND LANDING (STOL)
- 12.2.2.1 Growing demand for runway-independent operations
- 12.2.3 VERTICAL TAKE-OFF AND LANDING (VTOL)
- 12.2.3.1 Growing demand for flexible fixed-wing operations
- 12.2.1 CONVENTIONAL TAKE-OFF AND LANDING (CTOL)
- 12.3 ROTARY WING
- 12.3.1 SINGLE ROTOR
- 12.3.1.1 Growing demand for high-endurance heavy-payload operations
- 12.3.2 MULTI ROTOR
- 12.3.2.1 Dual rotor
- 12.3.2.1.1 Growing demand for compact and efficient rotor configurations
- 12.3.2.2 Tricopter
- 12.3.2.2.1 Growing demand for agile and lightweight UAVs
- 12.3.2.3 Quadcopter
- 12.3.2.3.1 Growing demand for versatile and easy-to-deploy UAVs
- 12.3.2.4 Hexacopter
- 12.3.2.4.1 Growing demand for higher payload capacity and flight redundancy
- 12.3.2.5 Octacopter
- 12.3.2.5.1 Growing demand for heavy-payload and redundant UAV operations
- 12.3.2.6 Others
- 12.3.2.1 Dual rotor
- 12.3.1 SINGLE ROTOR
13 UAV (DRONE) MARKET, BY HUMAN CONTROL ARCHITECTURE (MARKET SIZE & FORECAST TO 2031-USD MILLION)
- 13.1 INTRODUCTION
- 13.2 HUMAN IN THE LOOP
- 13.2.1 GROWING DEMAND FOR DIRECT HUMAN CONTROL
- 13.3 HUMAN ON THE LOOP
- 13.3.1 GROWING ADOPTION OF SUPERVISED AUTONOMY
- 13.4 HUMAN OUT OF THE LOOP
- 13.4.1 GROWING DEMAND FOR FULLY AUTONOMOUS UAV OPERATIONS
14 UAV (DRONE) MARKET, BY MTOW (MARKET SIZE & FORECAST TO 2031-USD MILLION)
- 14.1 INTRODUCTION
- 14.2 <2 KG
- 14.2.1 GROWING DEMAND FOR LIGHTWEIGHT AND PORTABLE UAVS
- 14.3 >=2 KG TO <25 KG
- 14.3.1 GROWING DEMAND FOR VERSATILE ENTERPRISE UAVS
- 14.4 >=25 KG TO <150 KG
- 14.4.1 GROWING DEMAND FOR HIGH-PAYLOAD AGRICULTURAL AND INDUSTRIAL UAVS
- 14.5 >=150 KG TO <600 KG
- 14.5.1 GROWING DEMAND FOR AUTONOMOUS CARGO MOVEMENT AND HIGH-CAPACITY AERIAL OPERATIONS
- 14.6 >=600 KG TO <2,000 KG
- 14.6.1 GROWING DEMAND FOR LONG-ENDURANCE AND HIGH-PAYLOAD UAVS
- 14.7 >=2,000 KG
- 14.7.1 GROWING DEMAND FOR STRATEGIC LONG-ENDURANCE UAVS
15 UAV (DRONE) MARKET, BY RANGE (MARKET SIZE & FORECAST TO 2031-USD MILLION)
- 15.1 INTRODUCTION
- 15.2 VISUAL LINE OF SIGHT (VLOS) (<=0.5 KM)
- 15.2.1 GROWING DEMAND FOR DIRECT AND FLEXIBLE UAV OPERATIONS
- 15.3 EXTENDED VISUAL LINE OF SIGHT (EVLOS) (>0.5 KM TO 2 KM)
- 15.3.1 GROWING DEMAND FOR EXTENDED OPERATIONAL COVERAGE
- 15.4 BEYOND VISUAL LINE OF SIGHT (BVLOS) (>2 KM)
- 15.4.1 GROWING DEMAND FOR LONG-RANGE AUTONOMOUS OPERATIONS
16 UAV (DRONE) MARKET, BY COMPUTE TECHNOLOGY (MARKET SIZE & FORECAST TO 2031-USD MILLION)
- 16.1 INTRODUCTION
- 16.2 STANDARD-COMPUTE UAVS
- 16.2.1 GROWING DEMAND FOR RELIABLE ONBOARD PROCESSING
- 16.3 HIGH-COMPUTE/AI-ENABLED UAVS
- 16.3.1 GROWING DEMAND FOR REAL-TIME AUTONOMOUS INTELLIGENCE
17 UAV (DRONE) MARKET, BY END-USE INDUSTRY (MARKET SIZE & FORECAST TO 2031-USD MILLION)
- 17.1 INTRODUCTION
- 17.2 DEFENSE, SECURITY, & LAW ENFORCEMENT
- 17.2.1 GROWING DEMAND FOR PERSISTENT AERIAL INTELLIGENCE
- 17.3 AGRICULTURE
- 17.3.1 GROWING DEMAND FOR PRECISION FARM MANAGEMENT
- 17.4 LOGISTICS & TRANSPORTATION
- 17.4.1 GROWING DEMAND FOR FASTER AERIAL DELIVERY
- 17.5 ENERGY & UTILITIES
- 17.5.1 GROWING DEMAND FOR SAFER INFRASTRUCTURE INSPECTION
- 17.6 CONSTRUCTION & MINING
- 17.6.1 GROWING DEMAND FOR FASTER SITE INTELLIGENCE
- 17.7 MEDIA & ENTERTAINMENT
- 17.7.1 GROWING DEMAND FOR FLEXIBLE AERIAL CONTENT PRODUCTION
- 17.8 INSURANCE
- 17.8.1 GROWING DEMAND FOR FASTER RISK AND DAMAGE ASSESSMENT
- 17.9 WILDLIFE & FORESTRY, ENVIRONMENTAL SERVICES
- 17.9.1 GROWING DEMAND FOR HIGH-RESOLUTION ENVIRONMENTAL INTELLIGENCE
- 17.10 HEALTHCARE & MEDICAL SERVICES
- 17.10.1 GROWING DEMAND FOR RAPID MEDICAL LOGISTICS
- 17.11 EDUCATION & RESEARCH
- 17.11.1 GROWING USE OF UAVS FOR PRACTICAL LEARNING AND SCIENTIFIC RESEARCH
- 17.12 RECREATIONAL
- 17.12.1 GROWING INTEREST IN IMMERSIVE AND COMPETITIVE DRONE FLYING
- 17.13 OTHERS
18 UAV (DRONE) MARKET, BY REGION (MARKET SIZE & FORECAST TO 2031 - USD MILLION)
- 18.1 INTRODUCTION
- 18.2 NORTH AMERICA
- 18.2.1 US
- 18.2.1.1 Expansion of commercial drone operations and BVLOS regulatory development to drive market
- 18.2.2 CANADA
- 18.2.2.1 Integration of drones into low-level airspace to drive market
- 18.2.1 US
- 18.3 EUROPE
- 18.3.1 UK
- 18.3.1.1 Increasing adoption of UAVs across defense and commercial applications to drive market
- 18.3.2 GERMANY
- 18.3.2.1 Increasing defense adoption and development of BVLOS drone infrastructure to drive market
- 18.3.3 FRANCE
- 18.3.3.1 Increasing defense modernization and development of indigenous UAV capabilities to drive market
- 18.3.4 ITALY
- 18.3.4.1 Expansion of U-space infrastructure and increasing adoption of UAVs across commercial and defense applications to drive market
- 18.3.5 POLAND
- 18.3.5.1 Strengthening domestic drone capabilities and increasing defense adoption to drive market
- 18.3.6 UKRAINE
- 18.3.6.1 Rapid expansion of domestic UAV production and increasing military adoption to drive market
- 18.3.7 REST OF EUROPE
- 18.3.1 UK
- 18.4 ASIA PACIFIC
- 18.4.1 CHINA
- 18.4.1.1 Expansion of the low-altitude infrastructure to drive market
- 18.4.2 JAPAN
- 18.4.2.1 Expansion of commercial drone operations and development of drone traffic infrastructure to drive market
- 18.4.3 INDIA
- 18.4.3.1 Expansion of indigenous drone manufacturing to drive market
- 18.4.4 AUSTRALIA
- 18.4.4.1 Growing use of drone-in-a-box systems and remote operations to drive market
- 18.4.5 SOUTH KOREA
- 18.4.5.1 Expansion of commercial drone services to drive market
- 18.4.6 REST OF ASIA PACIFIC
- 18.4.1 CHINA
- 18.5 MIDDLE EAST
- 18.5.1 UAE
- 18.5.1.1 Increasing adoption of drones for autonomous logistics to drive market
- 18.5.2 SAUDI ARABIA
- 18.5.2.1 Increasing adoption across security, industrial, and commercial applications to drive market
- 18.5.3 TURKEY
- 18.5.3.1 Increasing international demand for Turkish-developed UAV platforms to drive market
- 18.5.4 ISRAEL
- 18.5.4.1 Strong defense demand and continued development of autonomous UAV technologies to drive market
- 18.5.4.2 Rest of Middle East
- 18.5.1 UAE
- 18.6 REST OF THE WORLD
- 18.6.1 LATIN AMERICA
- 18.6.1.1 Growing adoption of UAVs in agriculture, infrastructure, and commercial services to drive market
- 18.6.2 AFRICA
- 18.6.2.1 Growing adoption of UAVs for agriculture, infrastructure, public safety, and remote-area operations to drive market
- 18.6.1 LATIN AMERICA
19 COMPETITIVE LANDSCAPE
- 19.1 INTRODUCTION
- 19.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2021-2026
- 19.3 REVENUE ANALYSIS, 2021-2025
- 19.4 MARKET SHARE ANALYSIS, 2025
- 19.5 BRAND/PRODUCT COMPARISON
- 19.6 COMPANY VALUATION AND FINANCIAL METRICS
- 19.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 19.7.1 STARS
- 19.7.2 EMERGING LEADERS
- 19.7.3 PERVASIVE PLAYERS
- 19.7.4 PARTICIPANTS
- 19.7.5 COMPANY FOOTPRINT
- 19.7.5.1 Company footprint
- 19.7.5.2 Regional footprint
- 19.7.5.3 Platform footprint
- 19.7.5.4 Wing type footprint
- 19.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 19.8.1 PROGRESSIVE COMPANIES
- 19.8.2 RESPONSIVE COMPANIES
- 19.8.3 DYNAMIC COMPANIES
- 19.8.4 STARTING BLOCKS
- 19.8.5 COMPETITIVE BENCHMARKING
- 19.8.5.1 List of startups/SMEs
- 19.8.5.2 Competitive benchmarking of startups/smes
- 19.9 COMPETITIVE SCENARIO
- 19.9.1 PRODUCT LAUNCHES/DEVELOPMENTS
- 19.9.2 DEALS
- 19.9.3 OTHER DEVELOPMENTS
20 COMPANY PROFILES
- 20.1 KEY PLAYERS
- 20.1.1 BAYKAR TECH
- 20.1.1.1 Business overview
- 20.1.1.2 Products offered
- 20.1.1.3 Recent developments
- 20.1.1.4 MnM view
- 20.1.1.4.1 Key strengths
- 20.1.1.4.2 Strategic choices
- 20.1.1.4.3 Weaknesses and competitive threats
- 20.1.2 DJI
- 20.1.2.1 Business overview
- 20.1.2.2 Products offered
- 20.1.2.3 Recent developments
- 20.1.2.4 MnM view
- 20.1.2.4.1 Key strengths
- 20.1.2.4.2 Strategic choices
- 20.1.2.4.3 Weaknesses and competitive threats
- 20.1.3 NORTHROP GRUMMAN
- 20.1.3.1 Business overview
- 20.1.3.2 Products offered
- 20.1.3.3 Recent developments
- 20.1.3.4 MnM view
- 20.1.3.4.1 Key strengths
- 20.1.3.4.2 Strategic choices
- 20.1.3.4.3 Weaknesses and competitive threats
- 20.1.4 ISRAEL AEROSPACE INDUSTRIES LTD.
- 20.1.4.1 Business overview
- 20.1.4.2 Products offered
- 20.1.4.3 Recent developments
- 20.1.4.4 MnM view
- 20.1.4.4.1 Key strengths
- 20.1.4.4.2 Strategic choices
- 20.1.4.4.3 Weaknesses and competitive threats
- 20.1.5 TELEDYNE TECHNOLOGIES INCORPORATED
- 20.1.5.1 Business overview
- 20.1.5.2 Products offered
- 20.1.5.3 Recent developments
- 20.1.5.4 MnM view
- 20.1.5.4.1 Key strengths
- 20.1.5.4.2 Strategic choices
- 20.1.5.4.3 Weaknesses and competitive threats
- 20.1.6 GENERAL ATOMICS
- 20.1.6.1 Business overview
- 20.1.6.2 Products offered
- 20.1.6.3 Recent developments
- 20.1.6.4 MnM view
- 20.1.6.4.1 Key strengths
- 20.1.6.4.2 Strategic choices
- 20.1.6.4.3 Weaknesses and competitive threats
- 20.1.7 LOCKHEED MARTIN CORPORATION
- 20.1.7.1 Business overview
- 20.1.7.2 Products offered
- 20.1.7.3 Recent developments
- 20.1.8 BOEING
- 20.1.8.1 Business overview
- 20.1.8.2 Products offered
- 20.1.8.3 Recent developments
- 20.1.9 AEROVIRONMENT, INC.
- 20.1.9.1 Business overview
- 20.1.9.2 Products offered
- 20.1.9.3 Recent developments
- 20.1.10 TEXTRON INC.
- 20.1.10.1 Business overview
- 20.1.10.2 Products offered
- 20.1.10.3 Recent developments
- 20.1.11 AIRBUS
- 20.1.11.1 Business overview
- 20.1.11.2 Products offered
- 20.1.11.3 Recent developments
- 20.1.12 THALES
- 20.1.12.1 Business overview
- 20.1.12.2 Products offered
- 20.1.12.3 Recent developments
- 20.1.13 ELBIT SYSTEMS LTD.
- 20.1.13.1 Business overview
- 20.1.13.2 Products offered
- 20.1.13.3 Recent developments
- 20.1.14 LEONARDO S.P.A.
- 20.1.14.1 Business overview
- 20.1.14.2 Products offered
- 20.1.14.3 Recent developments
- 20.1.15 AUTEL ROBOTICS
- 20.1.15.1 Business overview
- 20.1.15.2 Products offered
- 20.1.15.3 Recent developments
- 20.1.1 BAYKAR TECH
- 20.2 OTHER PLAYERS
- 20.2.1 SHIELD AI
- 20.2.2 QUANTUM-SYSTEMS GMBH
- 20.2.3 ZIPLINE INTERNATIONAL INC.
- 20.2.4 PERCEPTO LTD.
- 20.2.5 FLYABILITY SA
- 20.2.6 WINGTRA AG
- 20.2.7 GARUDA AEROSPACE
- 20.2.8 BRINC DRONES INC.
- 20.2.9 ELROY AIR
- 20.2.10 DRONAMICS GROUP LIMITED
21 RESEARCH METHODOLOGY
- 21.1 RESEARCH DATA
- 21.1.1 SECONDARY DATA
- 21.1.1.1 Key data from secondary sources
- 21.1.2 PRIMARY DATA
- 21.1.2.1 Primary interview participants
- 21.1.2.2 Key data from primary sources
- 21.1.2.3 Breakdown of primary interviews
- 21.1.1 SECONDARY DATA
- 21.2 MARKET SIZE ESTIMATION
- 21.2.1 BOTTOM-UP APPROACH
- 21.2.2 TOP-DOWN APPROACH
- 21.2.3 BASE NUMBER CALCULATION
- 21.3 DATA TRIANGULATION
- 21.4 FACTOR ANALYSIS
- 21.4.1 DEMAND-SIDE INDICATORS
- 21.4.2 SUPPLY-SIDE INDICATORS
- 21.5 RESEARCH ASSUMPTIONS
- 21.6 RESEARCH LIMITATIONS
- 21.7 RISK ASSESSMENT
22 APPENDIX
- 22.1 DISCUSSION GUIDE
- 22.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 22.3 CUSTOMIZATION OPTIONS
- 22.4 RELATED REPORTS
- 22.5 AUTHOR DETAILS


