

|
시장보고서
상품코드
2100723
중국의 특수 비료 시장 : 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)China Specialty Fertilizer - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
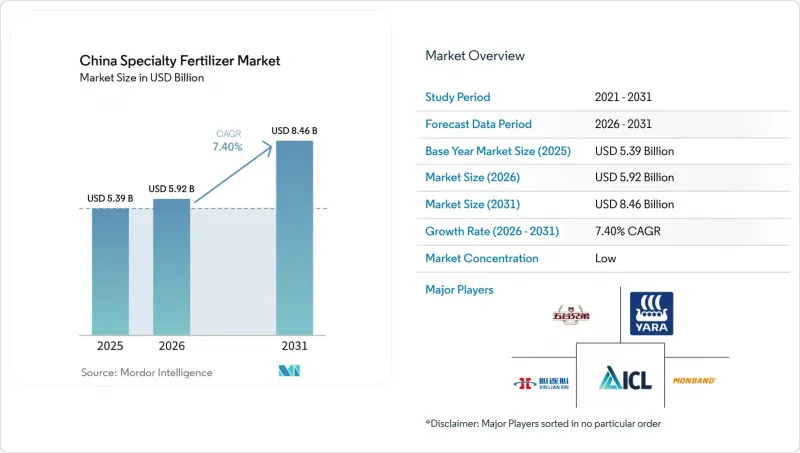
에 의하면, 중국 특수 비료 시장 규모는 2025년 53억 9,000만 달러에서 2026년에는 59억 2,000만 달러로 확대되어 2031년까지 84억 6,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년까지 CAGR 7.40%를 나타낼 전망입니다.

본 보고서는 특수 비료의 유형(CRF, 액체 비료, SRF, 수용성 비료), 시용 방법(비료 관개, 엽면 시비, 토양 시비) 및 작물 유형(밭작물, 원예작물, 잔디 및 관상용 작물)별로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(미터톤)으로 제시되어 있습니다.
중국 특수 비료 시장 동향 및 인사이트
고효율 비료에 대한 정부 보조금
중앙 정부 및 각 성의 보조금 제도에서는 방출 조절 비료 비용의 최대 30%가 보조되고 있으며, 이로 인해 상업 농가 및 협동조합의 도입 경제성이 근본적으로 변화하고 있습니다. 농림부가 2024년에 수립한 정책 프레임워크에 따르면, 이러한 우대 조치가 2027년까지 연장되며, 주요 곡물 생산 지역에서 1,500만 헥타르에 고효율 비료를 시비하는 것을 목표로 하고 있습니다. 이러한 정책 구조로 인해 보조금 대상 사업자는 기존 비료와 동등한 비용을 실현할 수 있는 반면, 보조금 대상에서 제외되는 소규모 농가는 여전히 가격 면에서 장벽에 직면하는 등 양극화된 시장이 형성되고 있습니다. 이 보조금 제도는 국산 영양 성분 원료의 사용을 의무화함으로써 국내 제조업체를 지원하고, 기술 이전을 촉진하는 동시에 중국 내 생산 능력 향상을 도모하고 있습니다.
보호 재배 및 온실 재배 확대
중국의 보호재배 면적은 2024년에 420만 헥타르로 확대되었으며, 그 성장의 85%를 플라스틱 필름 온실과 태양열 온실이 주도하고 있어 수용성 및 액체 비료 제제에 대한 집중적인 수요를 창출하고 있습니다. 신장 위구르 자치구의 온실 채소 생산량은 면화 이외의 농산물 다각화를 도모하는 정부의 이니셔티브에 힘입어 단독으로 전년 대비 23% 증가했습니다. 이러한 확대 추세는 지역에 뿌리를 둔 공급망의 기회를 창출하고 있습니다. 이는 온실 운영자들이 기존의 벌크 비료 판매업체로는 효율적으로 대응할 수 없는 특수한 양액의 빈번하고 소량 납품을 필요로 하기 때문입니다. 통제된 환경 하에서의 연중 생산 주기로의 추세는 정확한 시비 시기를 요구하며, 기술적 자문 능력을 갖춘 공급업체에 유리하게 작용하고 있습니다.
기존 비료에 비해 높은 톤당 비용
특수 비료는 기존 NPK 비료에 비해 1.5배에서 3배 높은 가격으로 책정되어 있어, 평균 경작 면적이 0.6헥타르 미만인 중국의 2억 가구에 달하는 소규모 농가에게 도입 장벽이 되고 있습니다. 대상 농가에게 정부가 비용의 30%를 보조하고 있음에도 불구하고, 특히 연안 지역에 비해 농업 소득이 낮은 개발도상인 중부 및 서부 성에서는 이익률이 낮은 농가에게 절대적인 가격 차이가 여전히 장벽으로 작용하고 있습니다. 이러한 비용 구조로 인해 대규모 상업 농가나 협동조합이 특수 비료 도입을 주도하는 반면, 수적으로 압도적 다수를 차지하는 소규모 농가층은 기존 제품에 의존하는 양극화된 시장이 형성되고 있습니다. 농산물 가격이 하락하는 시기에는 농가들이 장기적인 토양 건전성보다 당장의 비용 절감을 우선시하기 때문에 가격 차이는 더욱 확대됩니다.
부문 분석
액체 비료는 확립된 시비 및 관개 인프라에 힘입어 2025년 중국 특수 비료 시장 규모에서 42.0%라는 최대 시장 점유율을 유지하고 있습니다. 액체 비료는 시장의 큰 비중을 차지하고 있으며, 식물이 흡수하기 쉽고 관개 및 살포 시스템을 포함한 다양한 시비 방법에 대응할 수 있다는 장점이 있습니다. SRF(방출 조절 비료) 부문은 시장 점유율은 작지만, 장기간에 걸쳐 지속적으로 영양분을 공급하는 중요한 역할을 수행하고 있으며, 특히 생육 기간이 긴 작물에 유익합니다. 이러한 세분화 추세는 근본적인 농업 관행과 인프라 구축을 반영하며, 전문 공급업체에게 타겟을 명확히 한 시장 기회를 창출하고 있습니다.
방출 조절 비료(CRF)는 정부의 탄소 크레딧 시범 사업 및 정밀 농업 도입을 배경으로, 2031년까지 연평균 성장률(CAGR) 9.2%를 기록하며 가장 빠르게 성장하는 특수 비료로 부상하고 있습니다. CRF 부문은 고분자 코팅 화학 분야의 기술적 진보의 혜택을 받고 있으며, 각 제조업체는 환경 규제를 충족하면서도 정확한 영양분 방출을 유지하는 생분해성 대체품을 개발하고 있습니다. 수용성 비료는 온실 및 수경 재배, 특히 정밀한 영양분 관리가 필요한 보호 재배에 적합합니다. 지역별 선호도는 큰 차이를 보이며, 북부 주에서는 곡물 생산 효율화를 위해 방출 조절 비료가 선호되는 반면, 남부 지역에서는 집약적인 채소 재배를 위한 액체 제제가 중시되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 개 보고서의 내용
제3장 주요 요약 및 주요 조사 결과
제4장 주요 업계 동향
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 비료 업계 CEO가 직면하는 중요 전략적 과제
JHS 26.08.07According to Mordor Intelligence, the China specialty fertilizer market size is projected to grow from USD 5.39 billion in 2025 to USD 5.92 billion in 2026 and is forecast to reach USD 8.46 billion by 2031, registering a CAGR of 7.40% during 2026-2031.
This report is Segmented by Speciality Type (CRF, Liquid Fertilizer, SRF, and Water Soluble), by Application Mode (Fertigation, Foliar, and Soil), and by Crop Type (Field Crops, Horticultural Crops, and Turf and Ornamental). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Metric Tons)
China Specialty Fertilizer Market Trends and Insights
Government Subsidies for High-Efficiency Fertilizers
Central and provincial subsidy schemes reimburse up to 30% of controlled-release fertilizer costs, fundamentally altering adoption economics for commercial growers and cooperatives. The Ministry of Agriculture's 2024 policy framework extends these incentives through 2027, targeting 15 million hectares of high-efficiency fertilizer application across major grain-producing regions. This policy architecture creates a two-tier market where subsidized operations achieve cost parity with conventional fertilizers, while unsubsidized smallholders face persistent price barriers. The subsidy structure supports domestic manufacturers by requiring the use of locally sourced nutrient inputs, facilitating technology transfer, and enhancing production capacity within China.
Expansion Of Protected Horticulture and Greenhouse Cultivation
China's protected horticulture area expanded to 4.2 million hectares in 2024, with plastic-film greenhouses and solar greenhouses driving 85% of this growth, creating concentrated demand for water-soluble and liquid fertilizer formulations. Xinjiang's greenhouse vegetable production alone increased 23% year-over-year, supported by government initiatives to diversify the region's agricultural output beyond cotton. This expansion pattern generates localized supply chain opportunities, as greenhouse operators require frequent, small-batch deliveries of specialized nutrient solutions that traditional bulk fertilizer distributors cannot efficiently serve. The trend toward year-round production cycles in controlled environments necessitates precise nutrient timing, favoring suppliers with technical advisory capabilities.
Higher Per-Ton Cost Versus Conventional Fertilizers
Specialty fertilizers command prices 1.5 to 3 times higher than conventional NPK, creating adoption barriers for China's 200 million smallholder farming households with average landholdings below 0.6 hectares. Despite government subsidies covering 30% of costs for eligible operations, the absolute price differential remains prohibitive for farmers operating on thin margins, particularly in less-developed central and western provinces where agricultural incomes lag coastal regions. This cost structure creates a bifurcated market where large commercial operations and cooperatives drive specialty fertilizer adoption, while the numerically dominant smallholder segment relies on conventional products. The pricing gap widens during commodity price downturns, as farmers prioritize immediate cost reduction over long-term soil health benefits.
Other drivers and restraints analyzed in the detailed report include:
- Rising Adoption of Fertigation and Precision Irrigation Systems
- Shift of Tea and Specialty Cash Crops Toward Customized Nutrient Blends
- Stringent Environmental Regulations on Polymer Coatings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Liquid fertilizers maintain the largest market share at 42.0% of the China specialty fertilizer market size in 2025, supported by established fertigation infrastructure. Liquid fertilizers account for a significant share of the market, offering advantages such as easy plant absorption and compatibility with various application methods, including irrigation and spraying systems. The SRF segment, while smaller in market share, plays a crucial role in providing sustained nutrient release over extended periods, particularly beneficial for long-duration crops. This segmentation pattern reflects underlying agricultural practices and infrastructure development, creating targeted market opportunities for specialized suppliers.
Controlled-release fertilizers emerge as the fastest-growing specialty type at 9.2% CAGR through 2031, driven by government carbon credit pilots and precision agriculture adoption. The CRF segment benefits from technological advances in polymer coating chemistry, with manufacturers developing biodegradable alternatives that meet environmental regulations while maintaining precise nutrient release. Water-soluble fertilizers are well-suited for greenhouse and hydroponic applications, particularly in protected horticulture operations that require precise nutrient control. Regional preferences vary significantly: northern provinces favor CRF for grain production efficiency, while southern regions emphasize liquid formulations for intensive vegetable cultivation.
Complete Report Scope:
- Speciality Type
- CRF
- Polymer Coated
- Polymer-Sulfur Coated
- Others
- Liquid Fertilizer
- SRF
- Water Soluble
- CRF
- Application Mode
- Fertigation
- Foliar
- Soil
- Crop Type
- Field Crops
- Horticultural Crops
- Turf & Ornamental
List of Companies Covered in this Report:
- Hebei Woze Wufeng Biological Technology Co., Ltd
- Yara International ASA
- ICL Group Ltd
- Henan XinlianXin Chemicals Group Company Limited
- Hebei Monband Water Soluble Fertilizer Co. Ltd
- Kingenta Ecological Engineering Group Co. Ltd.
- Hubei Xinyangfeng Agricultural Technology Co. Ltd.
- Compo Expert GmbH
- Haifa Group
- Sociedad Quimica y Minera de Chile SA (SQM)
- Zouping Hongyun Biotechnology Co. Ltd.
- Sinochem Fertilizer Co. Ltd.
- Shandong Lvfeng Fertilizer Co. Ltd.
- Hebei HeRong Fertilizer Co. Ltd.
- Jiangsu Huifeng Agrochemical Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
- 1.3 Research Methodology
2 REPORT OFFERS
3 EXECUTIVE SUMMARY & KEY FINDINGS
4 KEY INDUSTRY TRENDS
- 4.1 Acreage Of Major Crop Types
- 4.1.1 Field Crops
- 4.1.2 Horticultural Crops
- 4.2 Average Nutrient Application Rates
- 4.2.1 Micronutrients
- 4.2.1.1 Field Crops
- 4.2.1.2 Horticultural Crops
- 4.2.2 Primary Nutrients
- 4.2.2.1 Field Crops
- 4.2.2.2 Horticultural Crops
- 4.2.3 Secondary Macronutrients
- 4.2.3.1 Field Crops
- 4.2.3.2 Horticultural Crops
- 4.2.1 Micronutrients
- 4.3 Agricultural Land Equipped For Irrigation
- 4.4 Regulatory Framework
- 4.5 Value Chain & Distribution Channel Analysis
- 4.6 Market Drivers
- 4.6.1 Government subsidies for high-efficiency fertilizers
- 4.6.2 Expansion of protected horticulture and greenhouse cultivation
- 4.6.3 Rising adoption of fertigation and precision irrigation systems
- 4.6.4 Shift of tea and specialty cash crops toward customized nutrient blends
- 4.6.5 E-commerce direct-to-farmer channels reducing distribution friction
- 4.6.6 Carbon-footprint linked ag-input credit pilots accelerating coated fertilizer demand
- 4.7 Market Restraints
- 4.7.1 Higher per-ton cost versus conventional fertilizers
- 4.7.2 Stringent environmental regulations on polymer coatings
- 4.7.3 Limited field-level agronomic advisory for smallholders
- 4.7.4 Microplastic concerns in green-food certification schemes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE AND VOLUME)
- 5.1 Speciality Type
- 5.1.1 CRF
- 5.1.1.1 Polymer Coated
- 5.1.1.2 Polymer-Sulfur Coated
- 5.1.1.3 Others
- 5.1.2 Liquid Fertilizer
- 5.1.3 SRF
- 5.1.4 Water Soluble
- 5.1.1 CRF
- 5.2 Application Mode
- 5.2.1 Fertigation
- 5.2.2 Foliar
- 5.2.3 Soil
- 5.3 Crop Type
- 5.3.1 Field Crops
- 5.3.2 Horticultural Crops
- 5.3.3 Turf & Ornamental
6 COMPETITIVE LANDSCAPE
- 6.1 Key Strategic Moves
- 6.2 Market Share Analysis
- 6.3 Company Landscape
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Business Segments, Financials, Key Information, Market Rank, Market Share, Products and Services, and Analysis of Recent Developments).
- 6.4.1 Hebei Woze Wufeng Biological Technology Co., Ltd
- 6.4.2 Yara International ASA
- 6.4.3 ICL Group Ltd
- 6.4.4 Henan XinlianXin Chemicals Group Company Limited
- 6.4.5 Hebei Monband Water Soluble Fertilizer Co. Ltd
- 6.4.6 Kingenta Ecological Engineering Group Co. Ltd.
- 6.4.7 Hubei Xinyangfeng Agricultural Technology Co. Ltd.
- 6.4.8 Compo Expert GmbH
- 6.4.9 Haifa Group
- 6.4.10 Sociedad Quimica y Minera de Chile SA (SQM)
- 6.4.11 Zouping Hongyun Biotechnology Co. Ltd.
- 6.4.12 Sinochem Fertilizer Co. Ltd.
- 6.4.13 Shandong Lvfeng Fertilizer Co. Ltd.
- 6.4.14 Hebei HeRong Fertilizer Co. Ltd.
- 6.4.15 Jiangsu Huifeng Agrochemical Co. Ltd.


