

|
시장보고서
상품코드
2118123
영국의 의료 관련 소포 라스트 마일 배송 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United Kingdom Healthcare Parcel Last-mile Delivery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
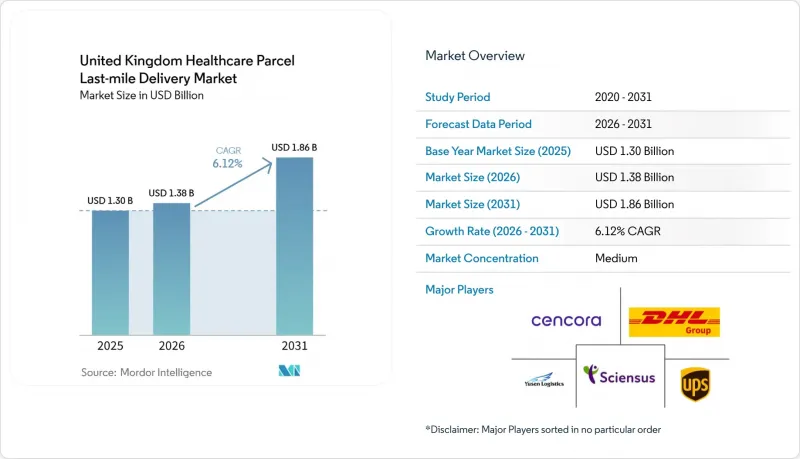
에 의하면, 영국 의료 관련 소포 라스트 마일 배송 시장 규모는 2025년에 13억 달러로 평가되었고, 2026년 13억 8,000만 달러에서 2031년까지 18억 6,000만 달러에 이를 것으로 추정되며, 예측 기간(2026-2031년) CAGR은 6.12%를 나타낼 전망입니다.
영국의 의료 관련 소포 라스트 마일 배송 시장의 성장은 일원화된 조제 방식에서 가정이나 약국, 더 엄격한 서비스 요건이 요구되는 의료 현장에 있는 환자에게 직접 전달되는 소포 주도형 유통으로 꾸준히 전환되고 있음을 반영합니다. 본 보고서는 배송 유형별(표준 배송, 당일 배송, 익일 배송), 온도 유형별(온도 제어형, 온도 관리 없음), 제품 유형별(의약품, 백신, 기타), 제공 모델별(B2C, B2B), 최종 사용자별(온라인 약국 및 오프라인 약국, 병원 및 클리닉, 기타), 지역별(잉글랜드, 스코틀랜드, 기타)로 세분화되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시됩니다.
영국의 의료 관련 소포 라스트 마일 배송 시장 동향 및 인사이트
시간적 제약이 있는 의료 관련 소포에 대한 당일·익일 배송 수요 증가
규제 대상인 조제 의약품의 긴급성으로 인해, 영국의 의료 관련 소포 라스트 마일 배송 시장에서는 당일·익일 배송이 단순한 프리미엄 부가 서비스가 아닌 핵심 서비스 수준으로 점점 더 자리 잡고 있습니다. 이러한 변화는 처방전의 디지털 가시화를 통해 더욱 가속화되고 있습니다. 2025년에 출시된 NHS 앱의 처방전 추적 기능은 잉글랜드의 모든 부츠(Boots) 매장을 포함한 약 1,650개의 약국을 포괄하고 있어, 이를 통해 소포 배송 현황의 명확화와 배송 시간대 준수에 대한 기대가 높아지고 있습니다. 처방전 처리량이 많은 점도 이 서비스 수요를 뒷받침하고 있습니다. 2025 회계연도, 잉글랜드의 지역 약국에서는 약 12억 건의 조제가 이루어졌으며, 약국과 환자를 경유하여 일상적인 배송부터 긴급 배송에 이르기까지 다양한 화물이 이동하고 있습니다. 그 결과, 영국의 의료 관련 소포 라스트 마일 배송 시장에서 더 엄격한 접수 마감 시간을 유지하고, 실시간 가시성을 제공하며, 예외 상황을 더 효과적으로 처리할 수 있는 사업자는 지속적인 의료 관련 배송 업무를 수주하는 데 유리한 입장에 있습니다. 이러한 영향은 우선 도시 지역에서 두드러지게 나타나지만, 그곳에서 확립된 서비스 기준은 더 광범위한 시장 전체의 조달에 대한 기대치를 형성하는 경향이 있습니다.
재택 간병의 확대와 환자에 대한 직접 배송
NHS(국민보건서비스)와 관련된 치료 경로가 병원 외 치료에 점점 더 의존하게 됨에 따라, 재택 간호는 영국의 의료 관련 소포 라스트 마일 배송 시장에서 더욱 중요한 운영 모델로 자리 잡고 있습니다. 재택 임상 케어는 불필요한 병원 방문을 줄이고, 급성기 의료의 수용 여력을 확보하면서도 동등한 치료 성과를 유지할 수 있어, 재택 배송 및 연계된 환자 서비스로의 광범위한 전환을 뒷받침하고 있습니다. 시설 내 조제에서 재택 케어로의 전환이 한 건 발생할 때마다, 보다 지속적인 소포 배송 관계가 형성되며, 여기에는 대개 엄격한 일정 관리, 환자와의 소통, 경우에 따라 간호사가 조정하는 배송 시간대 설정이 필요합니다. 이로 인해 영국의 의료 관련 소포 라스트 마일 배송 시장에서 소포 공급업체의 역할은 단순한 운송업체에서 치료의 연속성을 유지하는 서비스 파트너로 변화하고 있습니다. 또한, 환자가 재택 간호 채널에 등록되면 배송은 일회성 발송이 아닌 지속적인 간호 루틴의 일부가 되므로, 장기적인 수요 강화에도 기여합니다.
수거 밀도가 낮은 의료 배송 노선에서의 라스트 마일 비용 상승
수거 밀도가 낮은 배송 노선은 여전히 영국의 의료 관련 소포 라스트 마일 배송 시장에 큰 걸림돌이 되고 있습니다. 이는 규제 대상인 의료 소포가 일반 전자상거래(EC) 화물에 비해 수거 및 혼재가 어렵기 때문입니다. 배송에는 더 엄격한 신원 확인, 더 세밀한 시간 관리, 경우에 따라서는 온도 조절 조건이 필요한 경우가 많아, 이로 인해 저비용 수거 모델이나 유연한 수거 거점의 활용이 제한됩니다. 이러한 부담은 잉글랜드, 웨일스, 북아일랜드, 스코틀랜드 일부 지역 등에서 더욱 두드러지게 나타납니다. 이 지역들에서는 의료 소포 1건을 배달하는 데 소요되는 이동 시간이 구조적으로 길어지는 경향이 있습니다. 그 결과, 보다 신속한 서비스가 가능한 도시 지역의 밀집 노선과 소포 1건당 운영 부담이 큰 외곽 지역 노선 사이에서 영국의 의료 관련 소포 라스트 마일 배송 시장에서 이익률 격차가 발생하고 있습니다. 이러한 노선에서 위탁 업무 지원이 강화되거나 의료 수요가 더욱 증가하지 않는 한, 비용 상승은 지속적인 상업적 압박 요인으로 남을 가능성이 높다고 볼 수 있습니다.
부문 분석
2025년, 영국의 의료 관련 소포 라스트 마일 배송 시장에서 익일 배송은 42%의 점유율을 차지하며 가장 큰 배송 형태로 자리 잡았습니다. 이는 야간 보충이 도매업체, 약국, NHS(국민건강서비스) 관련 주문 주기의 운영 리듬과 여전히 부합하기 때문입니다. 영국의 의료 관련 소포 라스트 마일 배송 시장에서 익일 배송 서비스는 정기적인 공급과 긴급한 지점 간 배송 사이의 실용적인 중간 선택지로 계속 자리 잡고 있습니다. 이 부문은 예측 가능한 배송 경로, 정기적인 배송 패턴, 긴급 배송의 전체 비용을 부담하지 않으면서도 신뢰할 수 있는 배송이 필요한 상온 및 규제 대상 의료 제품의 폭넓은 품목 구성을 장점으로 가지고 있습니다. 또한, 많은 의료 관련 구매 담당자들이 여전히 서비스 품질과 조달 규율 간의 균형을 맞추려고 노력하고 있기 때문에 이 부문은 중요한 위치를 차지하고 있으며, 익일 배송 네트워크는 이를 대규모로 실현하기에 적합합니다.
당일 배송은 가장 빠르게 성장하는 부문으로, 2031년까지 연평균 성장률(CAGR) 10.20%로 확대될 것으로 예측됩니다. 이러한 변화를 가장 강력하게 시사하는 사건은 2026년 4월, Matternet이 런던 도심에서 NHS를 위한 드론 운항을 시작하여 두 주요 병원 캠퍼스 간에 진단 검체,검사 검체, 의약품을 수 분 만에 수송한 것입니다. 이로 인해 지상 배송 업체의 역할이 사라지는 것은 아니지만, 긴급성이 높은 의료 수요에 있어 배송 시간 단축과 보다 전문적인 경로 설계가 요구되고 있음을 보여줍니다.
2025년 영국의 의료 관련 소포 라스트 마일 배송 시장 규모에서 온도 관리가 필요 없는 소포는 51.26%를 차지했으며, 가장 큰 온도 관리 부문이 되었습니다. 이는 대량으로 유통되는 상온 의약품, 의료기기, 재택치료 용품이 여전히 소포 시장의 대부분을 차지하고 있기 때문입니다. 이러한 물류의 대부분은 첨단 온도 관리 인프라보다는 신뢰성, 시기적절성, 소포의 가시성에 의존하고 있습니다. 또한 이 부문은 냉장 및 초저온 운송에 비해 경로 계획이 용이하고 취급도 복잡하지 않다는 장점이 있습니다.
온도 관리 배송의 취급량은 적지만, 바이오의약품, 바이오시밀러, 첨단 치료법이 의료 물류 수요에서 더 큰 비중을 차지하게 됨에 따라, 이 부문의 영국 의료 관련 소포 라스트 마일 배송 시장은 2031년까지 연평균 성장률(CAGR) 6.98%를 나타낼 것으로 예측됩니다. FedEx는 2025년 IATA CEIV Pharma 기업 인증을 획득하여 이 시장 부문을 강화하고, 인증된 취급 대상 범위를 전 세계 의료 관련 화물 취급량의 90% 이상으로 확대했습니다. Kuehne+Nagel은 2026년 6월, 자체 관리 네트워크를 확충하여 유럽 게이트웨이를 경유하는 정시 배송이 요구되는 의약품 화물의 신뢰성을 향상시키고, 영국공급망을 지원하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측(금액, 2026-2031년)
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the United Kingdom healthcare parcel last-mile delivery market size was valued at USD 1.30 billion in 2025 and is estimated to grow from USD 1.38 billion in 2026 to reach USD 1.86 billion by 2031, at a CAGR of 6.12% during the forecast period (2026-2031).
Growth in the United Kingdom healthcare parcel last-mile delivery market reflects a steady shift away from centralized dispensing toward parcel-led distribution that reaches patients at home, in pharmacies, and in care settings with tighter service requirements. This report is Segmented by Delivery Type (Standard, Same-Day, Next-Day), by Temperature Type (Temperature Type, Non-Temperature Controlled), by Product Type (Pharmaceuticals, Vaccines, and More), by Delivery Model (B2C, B2B), by End User (E-Pharmacies, Hospitals, and More), and by Geography (England, Scotland, and More). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Healthcare Parcel Last-mile Delivery Market Trends and Insights
Rising Same-Day and Next-Day Demand for Time-Critical Healthcare Parcels
Urgency in regulated dispensing means that same-day and next-day delivery are increasingly treated as core service tiers in the United Kingdom healthcare parcel last-mile delivery market rather than premium add-ons. This shift is reinforced by digital prescription visibility, as the NHS App prescription tracker launched in 2025 and covered around 1,650 pharmacies, including every Boots store in England, which raises expectations for clearer parcel status and tighter delivery windows. Large prescription volumes also support this service need, as England's community pharmacies dispensed nearly 1.2 billion items in FY 2025, leaving a broad base of routine and urgent shipments moving through pharmacy and patient channels. As a result, operators in the United Kingdom healthcare parcel last-mile delivery market that can maintain tighter cut-off times, provide live visibility, and handle exceptions more effectively are better placed to win recurring healthcare flows. The effect is most visible first in urban areas, but the service standard set there tends to shape procurement expectations across the wider market.
Expansion of Home-Based Care and Direct-to-Patient Delivery
Home-based care is becoming a larger operating model for the United Kingdom healthcare parcel last-mile delivery market, as NHS-linked care pathways increasingly rely on treatment outside hospital settings. Clinical home care can reduce unnecessary hospital visits, free up acute care capacity, and maintain comparable outcomes, supporting a broader shift toward home delivery and coordinated patient services. Each shift from site-based dispensing to home care creates a more recurring parcel relationship that often needs scheduling discipline, patient communication, and, in some cases, nurse-coordinated delivery windows. That changes the role of parcel operators from simple transport vendors to service partners that help maintain treatment continuity in the United Kingdom healthcare parcel last-mile delivery market. It also supports stronger long-run demand because once a patient is enrolled in a home-based pathway, delivery becomes part of an ongoing care routine rather than a one-time shipment.
Last-Mile Cost Inflation in Low-Drop Density Healthcare Routes
Low-density delivery routes remain a meaningful brake on the United Kingdom healthcare parcel last-mile delivery market because regulated healthcare parcels are harder to consolidate than standard e-commerce volumes. Deliveries often require stronger identity checks, tighter timing, and, in some cases, controlled-temperature conditions, which limit the use of cheaper drop models and flexible consolidation points. That burden is more visible in rural England, Wales, Northern Ireland, and parts of Scotland, where travel time per successful healthcare drop tends to be structurally higher. The result is a margin gap in the United Kingdom healthcare parcel last-mile delivery market between dense urban routes, which can support faster service, and remote routes, which require greater operational effort per parcel. Unless those routes gain better commissioning support or denser healthcare demand, cost inflation is likely to remain a persistent commercial pressure.
Other drivers and restraints analyzed in the detailed report include:
- Cold Chain Compliance Pressure Across Clinical and Pharmaceutical Parcels
- NHS and Private Provider Outsourcing of Non-Core Logistics
- Chain-of-Custody Risk in Multi-Hand-Off Healthcare Deliveries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Next-day delivery held 42% of the United Kingdom healthcare parcel last-mile delivery market share in 2025, making it the largest delivery type, as overnight replenishment still aligns with the operating rhythms of wholesalers, pharmacies, and NHS-linked ordering cycles. In the United Kingdom healthcare parcel last-mile delivery market, next-day services remain the practical middle ground between routine scheduled supply and urgent point-to-point dispatch. This segment benefits from predictable routing, repeat-delivery patterns, and a broad base of ambient and regulated healthcare products that require reliable delivery without incurring full emergency costs. It also remains important because many healthcare buyers still balance service quality with procurement discipline, and next-day networks are well placed to do that at scale.
Same-day delivery is the fastest-growing segment, and it is projected to expand at a 10.20% CAGR through 2031. The strongest signal behind that shift came in April 2026, when Matternet launched NHS drone operations in Central London to move diagnostic samples, laboratory specimens, and pharmaceuticals between 2 major hospital campuses in minutes. This does not remove the role of road-based couriers, but it shows that high-acuity healthcare demand is moving toward shorter delivery windows and more specialized route design.
Non-temperature-controlled parcels accounted for 51.26% of the United Kingdom healthcare parcel last-mile delivery market size in 2025, making them the largest temperature segment, as high-volume ambient medicines, devices, and home healthcare supplies still represent the broadest parcel base. Much of this flow depends on reliability, timing, and parcel visibility rather than advanced thermal infrastructure. The segment also benefits from easier route planning and lower handling complexity compared with chilled or cryogenic transport.
Temperature-controlled delivery is smaller in volume, but the United Kingdom healthcare parcel last-mile delivery market for this segment is forecast to grow at a 6.98% CAGR through 2031 as biologics, biosimilars, and advanced therapies claim a larger share of healthcare logistics demand. FedEx strengthened this part of the market in 2025 through its IATA CEIV Pharma corporate certificate, which extended certified handling to more than 90% of its global healthcare volume. Kuehne+Nagel expanded its own-controlled network in June 2026, improving reliability for time-sensitive pharmaceutical cargo moving through European gateways, supporting the United Kingdom's supply chains.
Complete Report Scope:
- By Delivery Type
- Standard Delivery
- Same-Day Delivery
- Next-Day Delivery
- By Temperature Type
- Temperature Controlled
- Non-Temperature Controlled
- By Product Type
- Pharmaceuticals
- Prescription and Specialty Drugs
- OTC Drugs
- Biopharmaceuticals (Biologics and Biosimilars)
- Vaccines
- Clinical Trial Materials
- Cell and Gene Therapies
- Medical Devices
- Veterinary Medicine
- Blood, Plasma and Blood Components
- Diagnostic and Laboratory Products
- Home Healthcare Supplies
- Others
- Pharmaceuticals
- By Delivery Model
- B2C
- B2B
- By End User
- Hospitals and Clinics
- E-Pharmacies and Pharmacies
- Diagnostic Laboratories
- Home Healthcare Providers
- Direct-to-Patient Deliveries
- Others
- By Geography
- England
- Scotland
- Wales
- Northern Ireland
List of Companies Covered in this Report:
- Sciensus
- Yusen Logistics Group (including Movianto)
- Life Couriers UK Limited
- Phoenix Healthcare Distribution
- AAH Pharmaceuticals
- DHL Group
- UPS
- Oximio
- GXO Logistics, Inc.
- Royal Mail Group
- Polar Speed
- CitySprint
- Cencora
- FedEx
- DPDgroup
- Uniphar Logistics UK
- Geopost
- Matternet, Inc.
- CEVA Logistics
- Kuehne+Nagel
- EMED Group
- BAP Pharma Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview and Role of Parcel Last-Mile Delivery in Healthcare Logistics
- 4.2 Healthcare Spending Trends
- 4.3 Market Drivers
- 4.3.1 Rising Same-Day and Next-Day Demand for Time-Critical Healthcare Parcels
- 4.3.2 Expansion of Home-Based Care and Direct-to-Patient Delivery
- 4.3.3 Cold Chain Compliance Pressure Across Clinical and Pharmaceutical Parcels
- 4.3.4 NHS and Private Provider Outsourcing of Non-Core Logistics
- 4.3.5 Higher Parcel Traceability Expectations for Regulated Healthcare Shipments
- 4.3.6 Growing Cross-Channel Fulfillment by E-Pharmacies and Omnichannel Pharmacies
- 4.4 Market Restraints
- 4.4.1 Last-Mile Cost Inflation in Low-Drop Density Healthcare Routes
- 4.4.2 Chain-of-Custody Risk in Multi-Hand-Off Healthcare Deliveries
- 4.4.3 Packaging and Temperature Excursion Losses for Sensitive Parcels
- 4.4.4 Fragmented Service Requirements Across NHS, Private, and Consumer-Directed Deliveries
- 4.5 Regulatory Framework
- 4.6 Value Chain and Distribution Channel Architecture Analysis
- 4.7 Technology Innovations Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Rivalry Among Competitors
- 4.9 Evolution of Healthcare Parcel Last-Mile Delivery Requirements
- 4.10 Impact of Geo-Political Events on Supply Chain Shifts
5 Market Size and Growth Forecasts (Value, 2026-2031)
- 5.1 By Delivery Type
- 5.1.1 Standard Delivery
- 5.1.2 Same-Day Delivery
- 5.1.3 Next-Day Delivery
- 5.2 By Temperature Type
- 5.2.1 Temperature Controlled
- 5.2.2 Non-Temperature Controlled
- 5.3 By Product Type
- 5.3.1 Pharmaceuticals
- 5.3.1.1 Prescription and Specialty Drugs
- 5.3.1.2 OTC Drugs
- 5.3.2 Biopharmaceuticals (Biologics and Biosimilars)
- 5.3.3 Vaccines
- 5.3.4 Clinical Trial Materials
- 5.3.5 Cell and Gene Therapies
- 5.3.6 Medical Devices
- 5.3.7 Veterinary Medicine
- 5.3.8 Blood, Plasma and Blood Components
- 5.3.9 Diagnostic and Laboratory Products
- 5.3.10 Home Healthcare Supplies
- 5.3.11 Others
- 5.3.1 Pharmaceuticals
- 5.4 By Delivery Model
- 5.4.1 B2C
- 5.4.2 B2B
- 5.5 By End User
- 5.5.1 Hospitals and Clinics
- 5.5.2 E-Pharmacies and Pharmacies
- 5.5.3 Diagnostic Laboratories
- 5.5.4 Home Healthcare Providers
- 5.5.5 Direct-to-Patient Deliveries
- 5.5.6 Others
- 5.6 By Geography
- 5.6.1 England
- 5.6.2 Scotland
- 5.6.3 Wales
- 5.6.4 Northern Ireland
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Sciensus
- 6.4.2 Yusen Logistics Group (including Movianto)
- 6.4.3 Life Couriers UK Limited
- 6.4.4 Phoenix Healthcare Distribution
- 6.4.5 AAH Pharmaceuticals
- 6.4.6 DHL Group
- 6.4.7 UPS
- 6.4.8 Oximio
- 6.4.9 GXO Logistics, Inc.
- 6.4.10 Royal Mail Group
- 6.4.11 Polar Speed
- 6.4.12 CitySprint
- 6.4.13 Cencora
- 6.4.14 FedEx
- 6.4.15 DPDgroup
- 6.4.16 Uniphar Logistics UK
- 6.4.17 Geopost
- 6.4.18 Matternet, Inc.
- 6.4.19 CEVA Logistics
- 6.4.20 Kuehne+Nagel
- 6.4.21 EMED Group
- 6.4.22 BAP Pharma Limited
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


