

|
시장보고서
상품코드
2118124
미국의 플라스틱 폐기물 관리 서비스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Plastic Waste Management Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 미국의 플라스틱 폐기물 관리 서비스 시장 규모는 2025년 65억 5,000만 달러로 평가되었고, 2026년 68억 달러에서 2031년까지 82억 3,000만 달러로 확대될 것으로 예측되며, 2026-2031년 CAGR 3.89%를 기록하는 전망입니다.
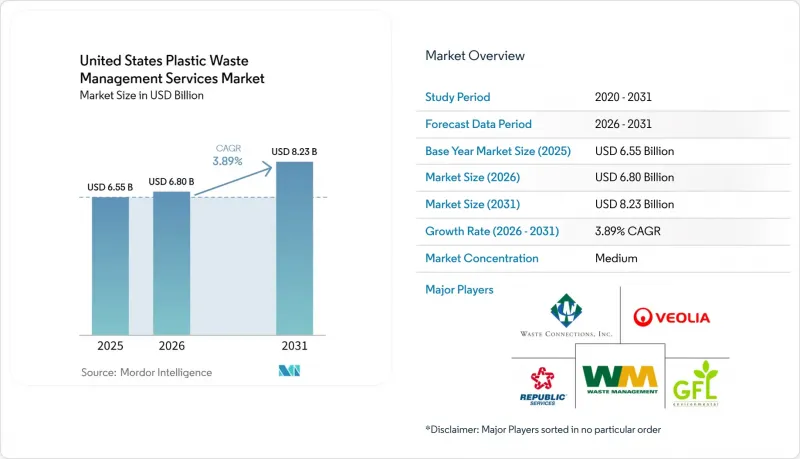
본 보고서는 발생원별(주거, 상업시설, 산업 시설, 기타), 서비스 제공업체별(공공·지자체, 민간 폐기물 관리 기업, 기타), 서비스 유형별(수집, 운송, 선별·분리, 처분·처리, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(톤) 단위로 제시되어 있습니다.
미국의 플라스틱 폐기물 관리 서비스 시장 동향 및 인사이트
플라스틱 포장에 대한 재생재 함유율 의무화
각 주의 재활용 소재 함유율 관련 법안은 자발적인 포장재 관련 공약의 범위를 넘어 수요를 확대함으로써, 미국 플라스틱 폐기물 관리 서비스 시장에서 재활용 수지에 대한 보다 견고한 수요 하한선을 형성하고 있습니다. 2025년 8월까지 5개 주가 플라스틱 포장재에 대한 사용 후 재활용 소재의 최소 함유율에 관한 법률을 제정했으며, 메인주는 2026년 1월 1일부터 플라스틱 음료 용기에 대해 25%의 함유율 요건을 도입했습니다. 또한 캘리포니아주는 SB 54에 따라 포장의 광범위한 전환을 추진하고 있습니다. 이 법은 2032년까지 모든 일회용 포장을 재활용 가능하거나 퇴비화 가능하도록 의무화하고 있으며, 이미 브랜드의 디자인 변경 및 공급업체 선정에 영향을 미치고 있습니다. APR이 인용한 2024년 캘리포니아 대학교 버클리 캠퍼스의 연구에 따르면, 2050년까지 전국적으로 40%의 재활용 소재 함유율을 의무화할 경우, 미국의 플라스틱 폐기물을 50% 감축하고, 버진 플라스틱 생산을 44% 감축하며,온실가스 배출을 17% 줄일 수 있는 것으로 밝혀졌습니다. 이는 장기적인 인프라 계획이 현재 수거 능력 확충에 점점 더 중점을 두고 있는 이유를 설명하는 요인 중 하나입니다. 또한 각 주가 APR 인증 방식이나 CalRecycle의 규정 제정 체계와 같은 검증 도구를 활용함에 따라 규정 준수 체계도 더욱 공식화되고 있으며, 이를 통해 분리수거 및 재처리 프로젝트에 대한 자금 조달이 더 용이해지는 여건이 조성되고 있습니다.
매립 처리비 급등이 재활용의 경제성 향상으로 이어져
미국의 플라스틱 폐기물 관리 서비스 시장은 처리 비용 상승의 혜택을 받고 있습니다. 이로 인해 재활용 제품 가격이 부진한 상황에서도 폐기물 전환(디버전)의 상대적 경제성이 향상되고 있습니다. 폐기물 에너지화(WTE) 시설을 보유한 주에서는 평균 처분 비용이 톤당 71.3달러에 달한 반면, 그러한 인프라가 없는 주에서는 톤당 55.6달러에 그치고 있어, 인구 밀도가 높은 연안 지역에서 처분 압력이 가장 강하다는 사실이 드러났습니다. 이러한 압박은 미국의 플라스틱 폐기물 관리 서비스 시장이 ‘서비스 대가형’ 가격 책정으로 전환되는 한 요인이 되고 있습니다. 이는 사업자가 회피된 처리 비용을 근거로 처리 요금을 보다 직접적으로 정당화할 수 있게 되었기 때문입니다. Waste Connections사는 연례 보고서에서 실제 비용을 더 적절하게 반영하기 위해 재활용 수거 및 처리 요금을 인상했다고 밝혔습니다.
자재 회수 시설의 자본 집약적 현대화
미국의 플라스틱 폐기물 관리 서비스 시장은 여전히 큰 자본적 장벽에 직면해 있습니다. 정책 목표를 달성하려면 많은 시설에서 대규모 개보수가 필요하기 때문입니다. 프로젝트 사례는 그 규모를 여실히 보여주는데, 레인 카운티의 시설은 1억 5,000만 달러, 램키(Lampkey)사의 콜럼버스 센터는 1억 달러, 애틀랜틱 코스트 리사이클링(Atlantic Coast Recycling)사의 파사익(Pasayk) 재개발은 4,700만 달러로 추산됩니다. 소규모 공영 시스템이나 지방자치단체의 경우, 막대한 보조금이나 안정적인 생산자 책임 제도를 통한 자금원이 없다면 이러한 투자액을 충당하기 어렵습니다. 자금 조달 비용의 급등과 장기적인 원료 공급량의 불확실성도, 특히 독립 재활용 업체나 지방자치단체가 소유한 시설에서 투자 결정을 더욱 지연시키고 있습니다. 또한, 수거 가능 자재 목록이 변경됨에 따라 이 문제는 반복적으로 발생하고 있습니다. 즉, 현재의 폐기물 흐름에 대응하기 위해 개조된 시설이라 하더라도, 포장 규제의 확대에 따라 3-5년 이내에 다시 설비를 추가해야 할 가능성이 있습니다.
부문별 분석
2025년, 미국 플라스틱 폐기물 관리 서비스 시장 점유율의 41.2%를 산업계 발생원이 차지했으며, 발생원 카테고리 중 최대의 수익 기반이 되었습니다. 이러한 위상은 플라스틱이 집중적으로 발생하는 자동차, 전자기기, 화학, 물류 각 사업 분야에서 산업 유래 스크랩이 안정적으로 유입되고 있음을 반영합니다. 이러한 폐기물 흐름에는 일반적으로 비교적 깨끗한 퍼지 재료, 규격 외 펠릿, 필름 자투리, 성형 불량품 등이 포함되어 있어, 소비 후 폐기물에 비해 선별 및 오염 관리 부담이 적습니다. 이러한 깨끗한 투입물의 특성 덕분에 서비스 제공업체는 미국의 플라스틱 폐기물 관리 서비스 시장에서 더 높은 이익률과 예측하기 쉬운 처리량을 확보할 수 있습니다.
이러한 이점은 현재의 투자 동향에서도 명확하게 드러나고 있습니다. 미국 Plastics Recovery사는 2026년 1월 조지아주 로렌스빌 사업장에서 분쇄 및 펠릿화 처리 능력을 두 배로 늘려, 연간 약 5,000만 파운드의 산업용 폴리머를 처리할 수 있게 되었습니다. 상업 부문은 가장 빠르게 성장하는 부문으로, 소매업체, 외식 체인, 사무실 및 전용 수거 경로 계획에 적합한 기타 집적형 발생원을 바탕으로 2031년까지 연평균 성장률(CAGR) 4.7%를 나타낼 것으로 예측됩니다. 주거 부문에서 발생하는 양은 여전히 상당하지만, 수거 경로가 세분화되어 있고 가구별 분리 수거 행동에 큰 편차가 있어 수거 비용 및 혼입물 처리 비용이 높아지는 경향이 있습니다. ‘기타’ 부문(기관, 의료, 농업 등)은 규모는 작지만, 중서부 주에서 농업용 필름의 축적이 주 당국 및 전문 수거 업체의 주목을 받으면서 관심이 높아지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.01According to Mordor Intelligence, the United States plastic waste management services market size is projected to expand from USD 6.55 billion in 2025 and USD 6.80 billion in 2026 to USD 8.23 billion by 2031, registering a CAGR of 3.89% between 2026 to 2031.
This report is Segmented by Source (Residential, Commercial, Industrial, and Others), by Service Provider (Public/Municipal, Private Waste Management Companies, and Others), and by Service Type (Collection, Transportation, Sorting & Segregation, Disposal / Treatment, and Others). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Tons).
United States Plastic Waste Management Services Market Trends and Insights
Mandatory Recycled Content Requirements for Plastic Packaging
State recycled-content laws are creating a firmer demand floor for recovered resin in the United States plastic waste management services market, as they move demand beyond voluntary packaging pledges. By August 2025, 5 states had enacted minimum post-consumer recycled content laws for plastic packaging, and Maine moved to a 25% requirement for plastic beverage containers effective January 1, 2026. California is also pushing a broad packaging shift under SB 54, which requires all single-use packaging to be recyclable or compostable by 2032 and is already influencing brand redesigns and supplier choices. A 2024 UC Berkeley study cited by APR found that a 40% national recycled content requirement by 2050 could cut United States plastic waste by 50%, lower virgin plastic production by 44%, and reduce greenhouse gas emissions by 17%, which helps explain why long-range infrastructure planning is now leaning more heavily toward recovery capacity. Compliance systems are also becoming more formal as states use verification tools such as APR certification approaches and CalRecycle rulemaking structures, which support more bankable demand conditions for sorting and reprocessing projects.
Escalating Landfill Tipping Fees Improving Recycling Economics
The United States plastic waste management services market is benefiting from rising disposal costs, which improve the relative economics of diversion even when recycled commodity prices are weak. In states with waste-to-energy capacity, the average fee reached USD 71.3 per ton, compared with USD 55.6 per ton in states without that infrastructure, indicating that disposal pressure is strongest in denser coastal systems. That pressure is helping the United States plastic waste management services market move toward fee-for-service pricing, as operators can more directly justify processing charges against avoided disposal costs. Waste Connections stated in its annual filing that it increased recycling collection and processing fees to reflect actual costs better.
Capital-Intensive Modernization of Material Recovery Facilities
The United States plastic waste management services market still faces a significant capital barrier, as many facilities require major upgrades before policy targets can be met. Project examples clearly show the scale, with Lane County's facility estimated at USD 150 million, Rumpke's Columbus center at USD 100 million, and Atlantic Coast Recycling's Passaic redevelopment at USD 47 million. For smaller public systems and rural municipalities, those investment levels are difficult to absorb without deep grant support or a stable producer responsibility funding stream. Higher financing costs and uncertainty over long-term feedstock volumes further delay investment decisions, particularly for independent recyclers and local government-owned facilities. The problem is also recurring because accepted material lists are changing, so sites upgraded for current streams may need more equipment again within 3 to 5 years as packaging rules expand.
Other drivers and restraints analyzed in the detailed report include:
- Growing Investments by Integrated Waste Companies in Recycling Capacity
- Growth in Public-Private Partnerships for Municipal Recycling Operations
- Low Recovery Rates for Flexible Films and Multi-Layer Packaging
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial sources accounted for 41.2% of the United States plastic waste management services market share in 2025, which made them the largest revenue base among source categories. That position reflects the steady flow of post-industrial scrap from automotive, electronics, chemical, and logistics operations, where plastics are generated in concentrated volumes. These streams usually contain cleaner purges, off-spec pellets, film trim, and molded rejects, so they need less sorting and contamination control than post-consumer loads. The cleaner input profile gives service providers better margins and more predictable throughput in the United States plastic waste management services market.
This advantage is evident in current investment patterns: United States Plastics Recovery doubled shredding and granulating capacity at its Lawrenceville, Georgia, site in January 2026 to handle nearly 50 million pounds of post-industrial polymer a year. Commercial sources are the fastest-growing category and are projected to grow at a 4.7% CAGR through 2031, supported by retailers, food service chains, offices, and other clustered generators that lend themselves well to dedicated route planning. Residential volumes remain important, but they bring higher collection and contamination costs because routes are fragmented and sorting behavior varies widely across households. The others segment, which includes institutions, healthcare, and agriculture, remains smaller but is gaining attention as agricultural film accumulation in Midwestern states draws more notice from state agencies and specialist collectors.
Complete Report Scope:
- By Source
- Residential
- Commercial (Retail, Office, etc.)
- Industrial
- Others (institutional, Agricultural, etc)
- By Service Provider
- Public/Municipal
- Private Waste Management Companies
- Others - Producer Responsibility Organizations (PROs), etc.
- By Service Type
- Collection, Transportation, Sorting & Segregation
- Disposal / Treatment
- Landfill
- Recycling & Resource Recovery
- Incineration & Waste-to-Energy
- Others (Chemical Treatment, etc.)
- Others (Consulting, Audit & Training, etc.)
List of Companies Covered in this Report:
- WM (Waste Management, Inc.)
- Republic Services
- Waste Connections
- Veolia North America
- GFL Environmental
- Clean Harbors
- Reworld
- Recology Inc.
- Casella Waste Systems
- Rumpke Waste & Recycling
- Sims Municipal Recycling
- PreZero US
- FCC Environmental Services
- Remondis Americas
- LRS (Lakeshore Recycling Systems)
- TerraCycle
- KW Plastics
- Balcones Resources
- Nexus Circular
- Circular Services (Closed Loop Partners)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Mandatory Recycled Content Requirements for Plastic Packaging
- 4.2.2 Escalating Landfill Tipping Fees Improving Recycling Economics
- 4.2.3 Growing Investments by Integrated Waste Companies in Recycling Capacity
- 4.2.4 Growth in Public-Private Partnerships for Municipal Recycling Operations
- 4.2.5 Increasing Industrial Plastic Scrap Recovery from Manufacturing
- 4.2.6 Increasing Demand for Closed-Loop Packaging Supply Chains
- 4.3 Market Restraints
- 4.3.1 Capital-Intensive Modernization of Material Recovery Facilities
- 4.3.2 Low Recovery Rates for Flexible Films and Multi-Layer Packaging
- 4.3.3 Insufficient Standardization of Accepted Recyclable Plastics
- 4.3.4 High Transportation Costs for Low-Density Plastic Waste
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Startup Ecosystem Analysis
- 4.8 Analysis of Recycled Plastics on Virgin Plastics
- 4.9 Analysis of Plastic Bale & Recycled Resin
- 4.10 Global Trade Flows & Import Restrictions (Waste Plastics)
5 Market Size and Growth Forecasts
- 5.1 By Source
- 5.1.1 Residential
- 5.1.2 Commercial (Retail, Office, etc.)
- 5.1.3 Industrial
- 5.1.4 Others (institutional, Agricultural, etc)
- 5.2 By Service Provider
- 5.2.1 Public/Municipal
- 5.2.2 Private Waste Management Companies
- 5.2.3 Others - Producer Responsibility Organizations (PROs), etc.
- 5.3 By Service Type
- 5.3.1 Collection, Transportation, Sorting & Segregation
- 5.3.2 Disposal / Treatment
- 5.3.2.1 Landfill
- 5.3.2.2 Recycling & Resource Recovery
- 5.3.2.3 Incineration & Waste-to-Energy
- 5.3.2.4 Others (Chemical Treatment, etc.)
- 5.3.3 Others (Consulting, Audit & Training, etc.)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Products & Services, and Recent Developments)}
- 6.4.1 WM (Waste Management, Inc.)
- 6.4.2 Republic Services
- 6.4.3 Waste Connections
- 6.4.4 Veolia North America
- 6.4.5 GFL Environmental
- 6.4.6 Clean Harbors
- 6.4.7 Reworld
- 6.4.8 Recology Inc.
- 6.4.9 Casella Waste Systems
- 6.4.10 Rumpke Waste & Recycling
- 6.4.11 Sims Municipal Recycling
- 6.4.12 PreZero US
- 6.4.13 FCC Environmental Services
- 6.4.14 Remondis Americas
- 6.4.15 LRS (Lakeshore Recycling Systems)
- 6.4.16 TerraCycle
- 6.4.17 KW Plastics
- 6.4.18 Balcones Resources
- 6.4.19 Nexus Circular
- 6.4.20 Circular Services (Closed Loop Partners)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


