

|
시장보고서
상품코드
2118228
OTT 이탈 분석 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)OTT Churn Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, OTT 이탈 분석 시장 규모는 2025년에 1억 9,686만 달러로 평가되었고, 2031년까지 5억 1,873만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 17.24%를 기록하는 전망입니다.
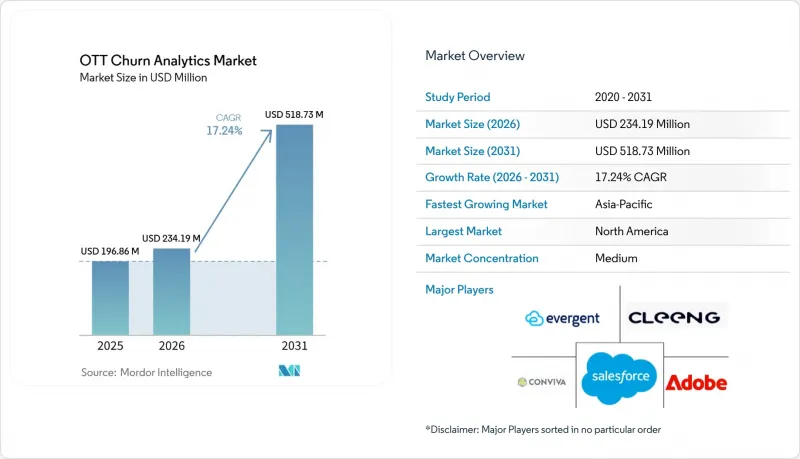
본 보고서는 구성 요소별(소프트웨어 및 서비스), 용도별(자발적 해지 예측 및 방지, 비자발적 해지 및 미납금 회수, 고객 유지 제안 및 해지 방지 최적화, 고객 재유치 및 재계약 분석), 최종 사용자별(구독형 및 하이브리드형 OTT, 스포츠 및 라이브 이벤트, 기타), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 OTT 해지 분석 시장 동향 및 인사이트
치열해지는 OTT 구독 경쟁이 분석에 대한 투자 촉진
미국의 프리미엄 SVOD 가입자 수 증가율은 2025년에 7%로 하락하여, 통계 집계 이래 처음으로 한 자릿수를 기록했습니다. 월간 해지율은 Tier 1 사업자의 경우 2-3%인 반면, 소규모 틈새 서비스에서는 7-30%에 달할 전망입니다. 이러한 차이로 인해 고객 유지의 경제성이 상대적으로 취약한 중견 서비스 사업자에 대한 압박이 더욱 가중되고 있습니다. 2025년, 전 세계 주요 스트리밍 사업자들은 해지로 인해 63억 달러의 손실을 입었으며, 이로 인해 더욱 강력한 고객 유지 시스템의 필요성이 다시 한번 부각되었습니다. 2025년 4분기에는 프리미엄 SVOD의 연간 총 가입자 수의 31%, 순증 가입자 수의 57%를 차지했습니다. 이에 따라 사업자들이 집중적인 고객 유치 기간 이후 가입자 유지에 주력함에 따라 OTT 해지 분석 시장이 수혜를 보고 있습니다.
실시간 AI와 머신러닝의 발전이 플랫폼의 기능을 확장
AI를 활용한 해지 예측을 통해 사업자는 가입자가 공식적으로 해지 절차를 완료하기 전에 선제적으로 대응할 수 있게 됩니다. Evergent사의 보고서에 따르면, 공식 해지 2-3주 전까지 94%의 예측 정확도를 달성하고 있습니다. 이를 통해 광범위한 할인 캠페인 대신 타겟팅된 제안을 전개할 수 있게 됩니다. Cleeng사는 2026년 4월, 신규 고객 유치, 고객 유지 및 고객 재유치 활동을 포괄하는 크로스 플랫폼 AI 에이전트를 출시했습니다. 이 플랫폼은 5,400만 명 이상의 가입자와 2억 5,000만 건의 구독 라이프사이클 이벤트에서 얻은 행동 데이터를 활용하고 있습니다. OTT 데이터셋에 대한 조사에서도, 그라디언트 부스팅, 딥러닝, 특징량 선택 기법을 결합한 하이브리드 모델을 통해 최대 98%의 정확도가 보고되었습니다.
데이터의 파편화와 구식 통합 아키텍처가 구조적인 장벽을 야기하고 있습니다.
가입자 데이터는 대개 Apple App Store, Google Play, Roku, 통신사의 결제 파트너 및 자체 웹 채널을 통해 수집됩니다. 이러한 정보 출처는 형식, 업데이트 주기 및 구독 라이프사이클의 정의가 각각 다릅니다. 월간 보고서에서는 시청 빈도 감소, 완료율 하락, 결제 재시도 실패 등이 간과될 가능성이 있습니다. 중견 사업자는 이러한 신호를 통합하는 데 비용이 들기 때문에 도입을 미룰 가능성이 있습니다. 또한, 다중 브랜드 사업자는 오퍼를 적절하게 타겟팅하기 전에 서비스 전반에 걸친 사용자 식별 정보를 해결해야 합니다. 2026년 2월 캘리포니아주 법무장관이 디즈니와 체결한 합의안은 서비스 전반에 걸친 식별 시스템에는 이에 상응하는 소비자의 옵트아웃 제어 기능이 필요함을 보여주었습니다.
부문 분석
2025년 OTT 해지율 분석 시장 규모 중 소프트웨어가 65.75%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 17.84%를 나타낼 것으로 예측됩니다. 사업자가 스코어링, 세분화 및 고객 유지 전략을 실행하기 위해 지속적인 시스템이 필요하기 때문에 소프트웨어는 계속해서 가장 큰 구성 요소를 차지하고 있습니다. 조기 도입 기업들은 기존 해지 스코어링 시스템에 에이전트 기반 기능을 추가하고 있는 반면, 후발 도입 기업들은 구독 분석을 처음으로 도입하고 있습니다. 이러한 조합이 소프트웨어 수요의 지속을 뒷받침하고 있으며, 도입과 확장이 동시에 진행되고 있는 카테고리임을 반영합니다.
서비스 부문은 2025년 매출의 나머지 34.25%를 차지했으며, 사내에 대규모 데이터 사이언스 팀을 보유하지 않은 통신 사업자에게 중요합니다. 도입, 통합 및 관리형 애널리틱스를 통해 도입 시 실무상의 장벽이 낮아집니다. Databricks는 2026년 1월 CustomerLake를 출시하여 Snowflake, Google BigQuery, 마케팅 플랫폼 및 리버스 ETL 파이프라인과의 통합을 실현했습니다. 이러한 제품은 수동 설정 작업을 줄이는 동시에 자문 업무의 가치를 높일 수 있습니다. 자동화가 진행됨에 따라 서비스는 사라지는 것이 아니라, 전략적 지원이나 모델 검증으로 전환될 가능성이 높습니다.
지역별 분석
2025년, 북미는 OTT 해지율 분석 시장의 35.40%를 차지했습니다. 이 지역에는 Tier 1 SVOD 기업의 본사가 집중되어 있으며, 분석 중심의 가입자 관리에 있어 오랜 실적을 보유하고 있습니다. 미국 프리미엄 SVOD의 월간 해지율은 2024년 4분기에 연율 환산 44%라는 정점을 기록한 후, 2025년에는 가중 평균 4.6%로 안정화되었습니다. 2026년, 미국 가구는 평균 4개의 유료 스트리밍 동영상 서비스에 매달 69달러를 지출했습니다. 이러한 수준의 서비스 이용은 고객 재유치 프로그램과 타겟팅된 재가입 촉진 제안의 가치를 높이고 있습니다.
아시아태평양은 2026-2031년 연평균 성장률(CAGR) 17.91%를 나타낼 것으로 예측됩니다. 이 지역에서는 2025년에 SVOD 가입자 수가 10억 건을 넘어섰으며, AVOD의 월간 활성 사용자 수는 27억 6,000만 명에 달했습니다. 일본의 프리미엄 VOD 시장은 2025년에 72억 달러에 달했으며, 가입자 수는 400만 명 증가해 6,790만 명을 기록했습니다. 인도의 경우 시장 규모 확대와 ARPU의 저조함이 예상에 따라, 미납금 회수 및 특정 사건을 계기로 한 고객 재유치 도구의 필요성이 높아지고 있습니다. 한국에서는 Disney+의 월간 활성 사용자 수가 400만 명 이상에서 312만 명으로 감소했으나, 2026년에 해당 기업이 오리지널 컨텐츠 제공을 가속화하면서 상황이 호전되었습니다.
유럽은 여전히 중요한 수요원이며, 독일은 이 지역의 시청 습관 변화를 여실히 보여주고 있습니다. 2026년에는 독일 가구의 54%가 IPTV 또는 스트리밍 서비스를 이용하고 있으며, 이는 2025년의 45%에서 증가한 수치입니다. GDPR(EU 개인정보보호규정) 요건은 비용 증가를 초래하는 한편, 개인정보를 보호하는 퍼스트파티 분석에 대한 수요도 창출하고 있습니다. 남미, 중동 및 아프리카에서는 플랫폼 이용과 분석의 성숙도가 높아짐에 따라 성장 과정이 장기화될 전망입니다. 브라질에서는 2026년에 7,030만 명의 스트리밍 가입자가 있었으며, OTT가 해당국의 동영상 컨텐츠 시장의 90.8%를 차지했습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.01According to Mordor Intelligence, the OTT churn analytics market size was USD 196.86 million in 2025 and is projected to reach USD 518.73 million by 2031, registering a CAGR of 17.24% from 2026 to 2031.
This report is Segmented by Component (Software, and Services), Application (Voluntary Churn Prediction and Prevention, Involuntary Churn and Payment Recovery, Retention Offer and Cancellation-Save Optimization, and Win-Back and Re-Subscription Analytics), End User (Subscription and Hybrid OTT, Sports and Live-Event, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global OTT Churn Analytics Market Trends and Insights
Intensifying OTT Subscription Competition Drives Analytics Investment
U.S. premium SVOD subscription growth fell to 7% in 2025, the first single-digit year in the reported series. Monthly churn ranged from 2-3% for tier-1 operators to 7-30% for smaller niche services. The difference places more pressure on mid-tier services, where retention economics are less resilient. Major global streamers lost USD 6.3 billion to churn in 2025, reinforcing the case for stronger retention systems. Q4 2025 produced 31% of annual gross additions and 57% of net additions for premium SVOD. The OTT churn analytics market therefore benefits as operators focus on retaining subscribers after concentrated acquisition periods.
Advancements in Real-Time AI and Machine Learning Expand Platform Capabilities
AI-based churn prediction allows operators to act before a subscriber completes a cancellation. Evergent reported 94% prediction accuracy up to 2-3 weeks before formal cancellation. This supports targeted offers instead of broad discount campaigns. Cleeng launched cross-platform AI agents in April 2026 that cover acquisition, retention, and win-back activity. The platform used behavioral data from more than 54 million subscribers and 250 million subscription lifecycle events. Research on OTT datasets also reported accuracy of up to 98% from hybrid models that combine gradient boosting, deep learning, and feature-selection methods.
Fragmented Data and Legacy Integration Architecture Creates Structural Barriers
Subscriber data often comes from Apple App Store, Google Play, Roku, telecom billing partners, and proprietary web channels. These sources use different formats, update intervals, and definitions of a subscription lifecycle. Monthly reporting can miss falling viewing frequency, lower completion rates, and unsuccessful payment retries. Mid-tier operators may delay deployment because unifying these signals is costly. Multi-brand operators must also resolve identities across services before they can target an offer properly. The California Attorney General's February 2026 Disney settlement showed that cross-service identity systems require corresponding consumer opt-out controls.
Other drivers and restraints analyzed in the detailed report include:
- Rising Cost of Subscriber Acquisition and Retention Raises the ROI Bar for Analytics
- Expansion of Ad-Supported and Hybrid Streaming Tiers Creates New Churn Typologies
- Privacy, Consent, and Data Residency Constraints Limit Behavioral Signal Depth
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software accounted for 65.75% of the OTT churn analytics market size in 2025 and is projected to grow at a 17.84% CAGR through 2031. It remains the largest component because operators need a persistent system for scoring, segmentation, and retention actions. Early adopters are adding agent-based functions to existing churn-scoring systems, while later adopters are implementing subscription analytics for the first time. This combination supports continued software demand and reflects a category where adoption and expansion are occurring at the same time.
Services represented the remaining 34.25% of revenue in 2025 and are important for operators without large internal data science teams. Implementation, integration, and managed analytics reduce the practical barrier to adoption. Databricks launched CustomerLake in January 2026 with integrations across Snowflake, Google BigQuery, marketing platforms, and reverse ETL pipelines. Such products can reduce manual configuration while increasing the value of advisory work. Services are likely to shift toward strategic support and model validation rather than disappear as automation expands.
Complete Report Scope:
- By Component
- Software
- Services
- By Application
- Voluntary Churn Prediction and Prevention
- Involuntary Churn and Payment Recovery
- Retention Offer and Cancellation-Save Optimization
- Win-Back and Re-Subscription Analytics
- By End User
- Subscription and Hybrid OTT
- Broadcasters/Pay-TV/Telecom OTT
- Sports and Live-Event
- Audio and Other Subscription
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 35.40% of the OTT churn analytics market share in 2025. The region has a high concentration of tier-1 SVOD headquarters and a long record of analytics-led subscriber management. U.S. premium SVOD monthly churn stabilized at a weighted average of 4.6% during 2025 after an annualized peak of 44% in Q4 2024. U.S. households spent USD 69 each month on an average of 4 paid streaming video services in 2026. This level of service use increases the value of win-back programs and targeted retention offers.
Asia-Pacific is projected to grow at a 17.91% CAGR from 2026 to 2031. The region had more than 1 billion SVOD subscriptions and 2.76 billion AVOD monthly active users in 2025. Japan's premium VOD sector reached USD 7.2 billion in 2025 and added 4 million subscribers to reach 67.9 million. India's projected scale and lower ARPU increase the need for payment recovery and event-triggered win-back tools. In South Korea, Disney+ monthly active users fell from more than 4 million to 3.12 million before the company accelerated original-content releases in 2026.
Europe remains an important source of demand, and Germany illustrates the region's changing viewing habits. IPTV or streaming services were used by 54% of German households in 2026, compared with 45% in 2025. GDPR requirements add cost but also create demand for privacy-safe first-party analytics. South America, the Middle East, and Africa offer a longer path for growth as platform use and analytics maturity develop. Brazil had 70.3 million streaming subscribers, while OTT represented 90.8% of its video-content market in 2026.
- Salesforce, Inc.
- Adobe Inc.
- Google LLC
- Microsoft Corporation
- Amazon Web Services, Inc.
- IBM Corporation
- Oracle Corporation
- Confluent, Inc.
- Databricks, Inc.
- Snowflake Inc.
- Conviva, Inc.
- Nielsen Holdings plc
- Comscore, Inc.
- Antenna Analytics, Inc.
- Cleeng B.V.
- Evergent Technologies, Inc.
- ThinkAnalytics Limited
- Brightcove Inc.
- Kaltura, Inc.
- Amplitude, Inc.
- Zuora, Inc.
- Recurly, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Intensifying OTT Subscription Competition
- 4.3.2 Expansion of Ad-Supported and Hybrid Streaming Tiers
- 4.3.3 Rising Cost of Subscriber Acquisition and Retention
- 4.3.4 Advancements in Real-Time AI and Machine Learning
- 4.3.5 Event-Level Viewing and Payment Telemetry
- 4.3.6 Privacy-Safe First-Party Data Activation
- 4.4 Market Restraints
- 4.4.1 Fragmented Data and Legacy Integration Architecture
- 4.4.2 Privacy, Consent, and Data Residency Constraints
- 4.4.3 Limited Analytics Maturity Among Regional and Mid-Market Platforms
- 4.4.4 Intervention Fatigue and Retention-Offer Margin Dilution
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Application
- 5.2.1 Voluntary Churn Prediction and Prevention
- 5.2.2 Involuntary Churn and Payment Recovery
- 5.2.3 Retention Offer and Cancellation-Save Optimization
- 5.2.4 Win-Back and Re-Subscription Analytics
- 5.3 By End User
- 5.3.1 Subscription and Hybrid OTT
- 5.3.2 Broadcasters/Pay-TV/Telecom OTT
- 5.3.3 Sports and Live-Event
- 5.3.4 Audio and Other Subscription
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Nigeria
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Positioning Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Salesforce, Inc.
- 6.4.2 Adobe Inc.
- 6.4.3 Google LLC
- 6.4.4 Microsoft Corporation
- 6.4.5 Amazon Web Services, Inc.
- 6.4.6 IBM Corporation
- 6.4.7 Oracle Corporation
- 6.4.8 Confluent, Inc.
- 6.4.9 Databricks, Inc.
- 6.4.10 Snowflake Inc.
- 6.4.11 Conviva, Inc.
- 6.4.12 Nielsen Holdings plc
- 6.4.13 Comscore, Inc.
- 6.4.14 Antenna Analytics, Inc.
- 6.4.15 Cleeng B.V.
- 6.4.16 Evergent Technologies, Inc.
- 6.4.17 ThinkAnalytics Limited
- 6.4.18 Brightcove Inc.
- 6.4.19 Kaltura, Inc.
- 6.4.20 Amplitude, Inc.
- 6.4.21 Zuora, Inc.
- 6.4.22 Recurly, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


