

|
시장보고서
상품코드
2118258
OTT용 생성형 AI 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Generative AI For OTT - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
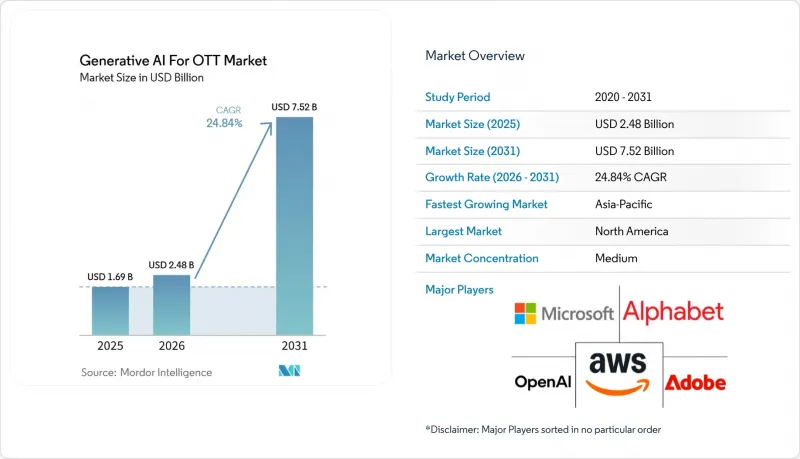
에 의하면, OTT용 생성형 AI 시장 규모는 2025년에 16억 9,000만 달러로 평가되었고, 2026년 24억 8,000만 달러에서 2031년까지 75억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 24.84%를 나타낼 전망입니다.
본 보고서는 컨텐츠 유형별(영화·영상 작품, TV 프로그램·에피소드 형식 컨텐츠, 다큐멘터리 등), 용도별(AI를 활용한 시나리오·컨텐츠 생성, AI 현지화(자막, 번역, 더빙, 보이스 클로닝) 등), 최종 사용자별(방송국·TV 네트워크, 디지털 미디어·컨텐츠 제작사 등), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 OTT용 생성형 AI 시장 동향 및 인사이트
AI를 활용한 컨텐츠 현지화에 대한 수요 증가
OTT용 생성형 AI 시장은 국가별로 순차적으로 출시하는 방식에서 동시 다국어 배포로 전환되는 추세의 혜택을 받고 있습니다. AI 현지화를 통해 플랫폼은 제작 주기를 단축하면서, 언어 시장을 넘나들며 컨텐츠 카탈로그의 도달 범위를 확대할 수 있게 됩니다. ElevenLabs는 2026년 5월, Dubbing v2를 도입했습니다. 이는 원본 연기를 활용하여 90개 이상의 언어에 걸쳐 어조, 템포, 말투를 충실하게 재현하는 기술입니다. 이러한 접근 방식을 통해 원본 연기와 현지화된 음성 간의 일관성이 더욱 높아집니다. 현지화 비용을 절감함으로써, 새로운 언어 시장에 진출하는 데 필요한 컨텐츠 라이브러리의 규모를 줄일 수 있습니다. 이러한 변화로 인해 지역 제작사가 자국 시장 외의 시청자에게도 쉽게 다가갈 수 있게 되므로, 세계 플랫폼에 대한 경쟁 압력이 높아질 가능성이 있습니다.
개인화된 스트리밍 경험으로의 전환
OTT용 생성형 AI는 순위 형식의 추천 목록을 넘어선 개인화를 통해 점차 발전하고 있습니다. 넷플릭스의 GenPage에 대한 연구에서는 미리 순위가 매겨진 타이틀 목록에서 선택하는 대신, 시청자의 시청 이력이나 요청의 맥락을 활용하여 홈페이지를 구성하는 시스템이 소개되었습니다. 이 연구에서는 프롬프트의 맥락이 풍부할수록 대규모 모델을 사용할 때보다 더 큰 개선 효과를 얻을 수 있는 것으로 밝혀졌습니다. 이에 따라 정확한 행동 데이터와 명확한 시청자 맥락이 더욱 중요시될 것입니다. AWS는 Bedrock AgentCore와 Nova Sonic 2.0을 사용하여 기분에 기반한 요청에 응답하는 대화형 디스커버리 어시스턴트에 대해 설명했습니다. 또한 Canal+는 2026년 3월, 유럽 및 아프리카 전역의 사업에서 AI 기반 컨텐츠 탐색 및 자연어 검색을 지원하기 위해 Google Cloud 및 OpenAI와 계약을 체결했습니다.
합성 자산에 대한 지적 재산권의 불확실성
AI 생성 컨텐츠 및 훈련 데이터에 대한 불확실성은 여전히 OTT 시장에서 생성형 AI의 보급을 저해하는 요인으로 작용하고 있습니다. 미국에는 구속력 있는 연방 수준의 퍼블리시티권이 존재하지 않기 때문에 각 스튜디오는 목소리나 초상 복제에 관한 주 차원의 규정을 준수할 수밖에 없는 상황입니다. SAG-AFTRA 조합원들은 2026년부터 실존 배우에 비해 현저한 부가가치를 제공하는 경우에 한해 합성 연기자의 사용을 허용하는 4년짜리 스튜디오 계약을 승인했습니다. 더 많은 판례를 통해 선례가 확립되기 전까지는 스튜디오와 노동조합 간에 이 조항의 해석에 차이가 발생할 가능성이 있습니다. 소규모 사업자는 전담 법무 인력이 없는 경우, 방대한 라이브러리 전체에 걸친 권리 체인의 유효성을 평가하는 데 어려움을 겪을 수 있습니다. 이러한 검토에 드는 비용이 실질적인 비용 절감을 실현하기 위해 필요한 규모의 도입을 제한하는 요인이 될 수 있습니다.
부문 분석
2025년에는 영화가 35.40%의 점유율을 차지했습니다. 장편 작품 제작에 있어서는 시각 효과 강화, 역사적 장면 재현, 군중 장면 확충을 통해 막대한 가치를 창출할 수 있습니다. 넷플릭스는 다큐멘터리 분야에서 AI를 활용한 작업을 통해 제작 시간과 비용 모두를 절감했다고 보고했습니다. 또한 재현 기술을 통해 실사 재현이나 라이선스를 취득한 아카이브 영상에 대한 의존도를 낮출 수 있기 때문에 다큐멘터리도 중요한 활용 사례가 되고 있습니다. Gennie Studio는 Sphere Abacus가 전 세계에 배포한 Sky HISTORY의 다큐멘터리 시리즈 《Killer Kings》에서 AI를 활용한 재구성을 통해 재현 장면을 도입했습니다.
TV 프로그램 및 에피소드 형식의 컨텐츠는 2031년까지 연평균 성장률(CAGR) 25.53%를 나타낼 것으로 예측됩니다. 연속 드라마 형식의 경우, 메타데이터 태깅, 예고편 제작, 더빙 업데이트, 자막 생성 등의 작업이 반복적으로 발생합니다. 동일한 워크플로를 여러 에피소드나 제작 주기에 걸쳐 적용할 수 있습니다. 그 밖의 카테고리에는 세로형 단편 드라마와 마이크로 컨텐츠가 포함됩니다. 2026년 3월, ByteDance가 Douyin에서 AI로 생성된 단편 드라마에 투자한 일일 광고비는 7,000만 위안(960만 달러 상당)을 넘어섰습니다.
지역별 분석
2025년, 북미는 OTT용 생성형 AI 시장 규모의 40.44%를 차지했습니다. 이 지역에는 대규모 스트리밍 플랫폼, 포스트 프로덕션 기술 공급업체, 모델 개발자들이 집결해 있어 활발한 상용화가 진행되고 있습니다. Runway는 2026년 2월, 기업 가치 53억 달러로 3억 1,500만 달러의 자금 조달을 완료했습니다. 이번 라운드는 General Atlantic이 주도했으며, NVIDIA, Adobe Ventures, AMD Ventures가 참여했습니다. 캐나다는 시각 효과(VFX) 분야의 강점을 활용하고 있는 반면, 멕시코는 스페인어 현지화 분야의 성장 시장으로 주목받고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 25.18%를 나타낼 것으로 예측됩니다. 언어의 다양성, 확대되는 구독 기반, 그리고 제작 비용 절감 추구가 이 지역 전체의 AI 도입을 뒷받침하고 있습니다. 2026년 해당 지역의 컨텐츠 지출 예상액 221억 달러 중 인도가 12%를 차지했습니다. JioStar는 2026년, 엔드투엔드 AI 네이티브 제작 파이프라인인 JioStar GenAI Media Studio를 발표했습니다. 중국에서는 Douyin 마케팅 플랫폼의 데이터에 따르면, 2026년 1분기에 AI 생성 드라마의 조회수가 7,500억 회에 달했습니다.
유럽, 남미, 중동 및 아프리카에서는 현지 규제와 시장의 성숙도에 따라 AI 도입 양상이 다릅니다. EU AI법 제50조는 2026년 8월 2일에 발효되어, 유럽연합(EU) 역내에서 배포되는 합성 컨텐츠에 대해 기계가 읽을 수 있는 출처 표시를 의무화하고 있습니다. Canal+는 2026년 6월부터 유럽 및 아프리카 시장에서 제작 워크플로우 도구와 자연어 기반 컨텐츠 검색 기능을 모두 활용했습니다. 브라질과 아르헨티나에서는 포르투갈어 및 스페인어 컨텐츠의 현지화 기회가 생겨나고 있습니다. MBC Shahid를 비롯한 중동 플랫폼에서는 아랍어 AI 더빙의 시범 운영이 진행되고 있으며, 아프리카에서는 모바일 스트리밍의 확대와 현지화 비용 절감이 진행됨에 따라 그 혜택을 누릴 수 있을 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the generative AI for OTT market size was valued at USD 1.69 billion in 2025 and estimated to grow from USD 2.48 billion in 2026 to reach USD 7.52 billion by 2031, at a CAGR of 24.84% during the forecast period (2026-2031).
This report is Segmented by Content Type (Movies and Films, TV Shows and Episodic Content, Documentaries, and More), Application (AI Script and Content Generation, AI Localization (Translation, Dubbing and Voice Cloning), and More), End User (Broadcasters and Television Networks, Digital Media and Content Agencies, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Generative AI For OTT Market Trends and Insights
Increasing Demand for AI-Accelerated Content Localization
The Generative AI for OTT market benefits from a shift toward simultaneous multilingual distribution instead of sequential releases by country. AI localization gives platforms a way to extend catalog reach across language markets with shorter production cycles. ElevenLabs introduced Dubbing v2 in May 2026, which uses the original performance to preserve tone, pacing, and delivery across more than 90 languages. This approach supports a closer match between the original performance and localized audio. Lower localization costs can reduce the library scale needed to enter a new language market. That change can increase competitive pressure on global platforms because regional producers may be able to reach audiences outside their home markets more easily.
Shift Toward Personalized Streaming Experiences
The Generative AI for OTT market is also being shaped by personalization that goes beyond ranked recommendation lists. Netflix's GenPage research described a system that uses viewer history and request context to generate homepage layouts rather than select from pre-ranked title lists. The research found that richer prompt context produced greater improvements than a larger model. This places more value on accurate behavioral data and clear viewer context. AWS described a conversational discovery assistant that responds to mood-based requests using Bedrock AgentCore and Nova Sonic 2.0. Canal+ also signed agreements with Google Cloud and OpenAI in March 2026 to support AI-driven discovery and natural-language search across European and African operations.
IP Ownership Uncertainty for Synthetic Assets
Uncertainty over AI-generated content and training data remains a restraint on the Generative AI for OTT market. The United States has no binding federal right of publicity, leaving studios to navigate state-level rules for replicated voices and likenesses. SAG-AFTRA members ratified a 4-year studio contract in 2026 that permits synthetic performers when they provide significant additional value compared with a live actor. Studios and unions may interpret this language differently until more cases establish precedent. Smaller operators may struggle to assess rights-chain validity across a large library without dedicated legal resources. The cost of this review can limit deployment at the scale required to achieve meaningful savings.
Other drivers and restraints analyzed in the detailed report include:
- Broad Adoption of Generative Video and Voice Tools in Post-Production Workflows
- Pressure to Reduce Content Operations Costs and Turnaround Time
- Talent and Guild Pushback on Automated Creative Substitution
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Movies and films held 35.40% share in 2025. Feature-length productions can generate substantial value from visual effects enhancement, historical scene recreation, and crowd augmentation. Netflix reported that AI-supported work on a documentary segment reduced both production time and cost. Documentaries are also becoming a relevant use case because reconstruction can reduce reliance on live-action recreation or licensed archive footage. Gennie Studio used AI-reconstructed reenactments for the Killer Kings documentary series on Sky HISTORY, which Sphere Abacus distributed globally.
TV shows and episodic content is projected to record a 25.53% CAGR through 2031. Serialized formats create repeated opportunities for metadata tagging, trailer creation, dubbing updates, and subtitle generation. The same workflow can be applied through several episodes and multiple production cycles. The Others category includes short-form vertical drama and micro-content. ByteDance's daily advertising spend on AI-generated short dramas on Douyin exceeded CNY 70 million, equivalent to USD 9.6 million, in March 2026.
Complete Report Scope:
- By Content Type
- Movies and Films
- TV Shows and Episodic Content
- Documentaries
- Other Content Types
- By Application
- AI Script and Content Generation
- AI Localization (Subtitles, Translation, Dubbing and Voice Cloning)
- AI Customer Engagement (Virtual Assistants and Chatbots)
- Other Applications
- By End User
- Streaming Platforms
- Broadcasters and Television Networks
- Digital Media and Content Agencies
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 40.44% of the Generative AI for OTT market size in 2025. The region combines large streaming platforms, post-production technology vendors, and model developers with active commercial deployments. Runway raised USD 315 million in February 2026 at a USD 5.3 billion valuation, with General Atlantic leading the round and NVIDIA, Adobe Ventures, and AMD Ventures participating. Canada benefits from its visual-effects sector, while Mexico is a growing target for Spanish-language localization.
Asia-Pacific is projected to grow at a 25.18% CAGR through 2031. Linguistic diversity, expanding subscription bases, and the pursuit of lower production costs support adoption across the region. India accounted for 12% of the region's projected USD 22.1 billion content spend in 2026. JioStar announced JioStar GenAI Media Studio as an end-to-end AI-native production pipeline in 2026. In China, AI-generated drama viewership reached 750 billion views in Q1 2026, according to data from Douyin's marketing platform.
Europe, South America, the Middle East, and Africa have different adoption patterns because of local regulation and market maturity. The EU AI Act Article 50 takes effect on August 2, 2026, and requires machine-readable provenance marks for synthetic content distributed in the European Union. Canal+ used both production workflow tools and natural-language content discovery across European and African markets from June 2026. Brazil and Argentina provide localization opportunities for Portuguese and Spanish content. Middle East platforms, including MBC Shahid, have conducted AI dubbing trials in Arabic, while Africa can benefit as mobile streaming expands and localization becomes more economical.
- Adobe Inc.
- Amazon Web Services, Inc.
- Alphabet Inc.
- Apple Inc.
- Baidu, Inc.
- ByteDance Ltd.
- Comcast Corporation
- Digital Domain Holdings Limited
- ElevenLabs Inc.
- International Business Machines Corporation
- Microsoft Corporation
- Meta Platforms, Inc.
- Netflix, Inc.
- NVIDIA Corporation
- OpenAI OpCo, LLC
- Oracle Corporation
- Runway AI, Inc.
- Snap Inc.
- Stability AI Ltd.
- Tencent Holdings Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand for AI-Accelerated Content Localization
- 4.2.2 Rising Need for Faster Trailer, Thumbnail, and Metadata Production
- 4.2.3 Shift Toward Personalized Streaming Experiences
- 4.2.4 Broad Adoption of Generative Video and Voice Tools in Post-Production Workflows
- 4.2.5 Expansion of Cloud-Native Creative Pipelines Across OTT Platforms
- 4.2.6 Pressure to Reduce Content Operations Costs and Turnaround Time
- 4.3 Market Restraints
- 4.3.1 IP Ownership Uncertainty for Synthetic Assets
- 4.3.2 Talent and Guild Pushback on Automated Creative Substitution
- 4.3.3 Model Hallucination and Brand-Safety Risks in Consumer-Facing Outputs
- 4.3.4 Content Authenticity, Watermarking, and Provenance Compliance Burden
- 4.4 Industry Value Chain Analysis
- 4.5 Technology and Workflow Landscape
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Suppliers
- 4.9.3 Bargaining Power of Buyers
- 4.9.4 Threat of Substitutes
- 4.9.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Content Type
- 5.1.1 Movies and Films
- 5.1.2 TV Shows and Episodic Content
- 5.1.3 Documentaries
- 5.1.4 Other Content Types
- 5.2 By Application
- 5.2.1 AI Script and Content Generation
- 5.2.2 AI Localization (Subtitles, Translation, Dubbing and Voice Cloning)
- 5.2.3 AI Customer Engagement (Virtual Assistants and Chatbots)
- 5.2.4 Other Applications
- 5.3 By End User
- 5.3.1 Streaming Platforms
- 5.3.2 Broadcasters and Television Networks
- 5.3.3 Digital Media and Content Agencies
- 5.3.4 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Nigeria
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Vendor Positioning Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 Amazon Web Services, Inc.
- 6.4.3 Alphabet Inc.
- 6.4.4 Apple Inc.
- 6.4.5 Baidu, Inc.
- 6.4.6 ByteDance Ltd.
- 6.4.7 Comcast Corporation
- 6.4.8 Digital Domain Holdings Limited
- 6.4.9 ElevenLabs Inc.
- 6.4.10 International Business Machines Corporation
- 6.4.11 Microsoft Corporation
- 6.4.12 Meta Platforms, Inc.
- 6.4.13 Netflix, Inc.
- 6.4.14 NVIDIA Corporation
- 6.4.15 OpenAI OpCo, LLC
- 6.4.16 Oracle Corporation
- 6.4.17 Runway AI, Inc.
- 6.4.18 Snap Inc.
- 6.4.19 Stability AI Ltd.
- 6.4.20 Tencent Holdings Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


