|
시장보고서
상품코드
2119812
체중 감량용 당뇨병 치료제 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Weight Loss Diabetes Drug - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 체중 감량용 당뇨병 치료제 시장 규모는 2025년 356억 2,000만 달러로 평가되었습니다. 2026년에는 374억 8,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 5.21%로 성장을 지속하여, 2031년에는 482억 7,000만 달러에 이를 것으로 예측됩니다.
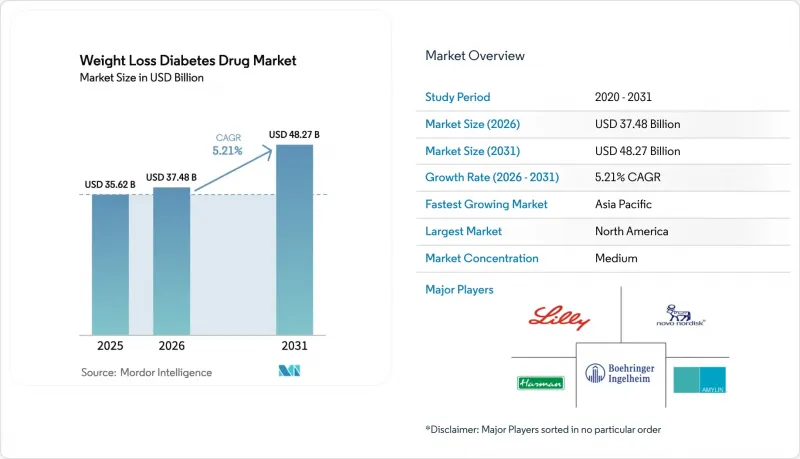
본 보고서는 제제별(Trulicity, Victoza, Ozempic, 기타), 작용기전별(GLP-1 수용체 작용제, 이중 GIP/GLP-1 작용제, 기타), 투여 경로별(주사제, 경구제),유통 채널(병원 약국, 기타), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 체중 감량용 당뇨병 치료제 시장 동향 및 인사이트
비만과 당뇨병의 동반 유병률 증가
현재 미국의 성인 비만율은 40%를 초과하며, 이는 약 8,800만 명의 당뇨병 전단계 환자와 겹칩니다. GLP-1 요법은 이 두 가지 상태를 모두 독립적으로 치료하며, 주요 임상시험에서 틸제파티드는 20.2%, 세마글루티드는 13.7%의 체중 감소가 확인되었습니다. 보험사들은 조기 대사 중재가 가져오는 장기적인 비용 절감 효과를 인식하고 있으며, 이에 따라 고용주 및 민간 보험 플랜에서 보장 범위가 확대되고 있습니다. 임상의들은 대사증후군의 1차 치료제로 GLP-1 제제를 처방하는 사례가 증가하고 있으며, 처방량은 기존 당뇨병 치료의 범위를 넘어 확대되고 있습니다. 이러한 수요 증가는 가격 압박이 가중되는 상황 속에서도 GLP-1 당뇨병 치료제 시장의 단기적인 성장을 뒷받침하고 있습니다.
획기적인 GLP-1 및 듀얼 작용제의 유효성
틸제파티드 등의 듀얼 작용제가 보여주는 우수한 치료 성과는 다중 표적형 혁신으로의 전환을 뒷받침하고 있습니다. 직접 비교 데이터에 따르면, HbA1c 감소 폭은 듀얼 아고니스트의 경우 2.0-2.3%인 반면, 단일 수용체 작용제인 비교 대상은 1.6-1.9%에 그쳤습니다. 중국의 개발 기업들도 더욱 탄력을 받고 있습니다. Gan & Lee의 GZR18은 오젬픽을 능가하는 체중 감소 효과에 더해, 최대 2.32포인트의 HbA1c 감소를 가져왔습니다. GLP-1, GIP, 글루카곤을 표적으로 하는 파이프라인의 트리플 작용제는 2027년 이후 치료의 기준을 바꿀 가능성이 있는 초기 대사 개선 효과를 보이고 있습니다. 이러한 유효성의 우위는 프리미엄 가격 책정을 뒷받침하고, 의사의 신뢰를 높이며, GLP-1 당뇨병 치료제 시장을 더욱 복잡한 경쟁 환경으로 이끌고 있습니다.
고액의 치료비와 불균등한 보험 환급
월 1,000-1,600달러에 달하는 치료비는 부유한 국가 이외의 지역에서 접근성을 제한하고 있습니다. 메디케어에서는 체중 감량 적응증이 제외되어 있으며, 미국 내 메디케이드의 적용 범위는 주마다 다르기 때문에 도입 상황에 현저한 격차가 발생하고 있습니다. 신흥 시장에서는 유병률이 상승하고 있음에도 불구하고, 보험 급여 격차가 초기 처방량을 억제하고 있어 단기적인 판매량 상한선으로 작용하고 있습니다. 고용주에 의한 비용 관리도 강화되고 있어, 이미 78%가 사전 승인이나 단계적 치료를 의무화하고 있습니다. 광범위한 재정 개혁이 이루어지지 않는 한, 가격 민감도가 본래라면 견조했을 GLP-1 당뇨병 치료제 시장의 성장 궤도를 둔화시킬 것입니다.
부문 분석
브랜드별 경쟁 측면에서 GLP-1 당뇨병 치료제 시장 규모를 살펴보면, 2025년 ‘Ozempic’의 매출액은 113억 6,000만 달러에 달했고, GLP-1 당뇨병 치료제 시장 점유율의 31.88%를 차지할 것으로 전망됩니다. 그 뒤를 잇는 ‘Mounjaro’는 절대 매출액은 낮지만, 이중 수용체에 대한 효능을 강점으로 삼아 2031년 연평균 성장률(CAGR)이 5.86%로 업계 1위를 기록할 전망입니다. 의사들은 익숙하다는 이유로 계속해서 ‘Trulicity’를 처방하고 있지만, 치료 성과 데이터가 축적됨에 따라 보험 적용 목록은 점차 ‘Mounjaro’로 전환되고 있습니다. ‘Victoza’의 경우, 2024년에 첫 제네릭 의약품이 등장함에 따라 브랜드 제품의 판매량은 감소하겠지만, 신약에 내약성이 없는 환자들 사이에서는 여전히 중요한 위치를 차지하고 있습니다. ‘Saxenda’의 성장은 임상적 이점이 있음에도 불구하고, 체중 감량 치료에 대한 보험 적용 범위의 미비로 인해 여전히 제약을 받고 있습니다. GZR18과 같은 중국산 신흥 분자들은 높은 효능과 공격적인 가격 책정을 결합하여 기존 제품에 타격을 줄 것으로 기대되며, 이로 인해 전 세계적인 경쟁이 격화되고 더 광범위한 접근성이 촉진될 것으로 보입니다.
2020년부터 2024년까지의 초기 도입 곡선은 ‘오젠픽(Ozempic)’의 급속한 부상을 여실히 보여주었지만, 향후 동향은 듀얼 작용제 및 트리플 작용제에 유리하게 작용할 것으로 예측됩니다. 그 결과, GLP-1 당뇨병 치료제 시장은 성숙한 블록버스터 제품의 지속가능성과 차세대 혁신 주기의 균형을 맞추게 될 것입니다. ‘Mounjaro’의 안전성 데이터와 실세계 데이터가 축적됨에 따라 보험 적용 상황에 변화가 생겨, 오젬픽 시장 점유율을 잠식하는 형태로 해당 제품의 점유율 확대가 가속화될 가능성이 있습니다. 또한, 릴라글루티드의 제네릭 의약품도 고령 환자층에서 가격을 낮추고 있어, 시장 진입 장벽을 낮추는 한편, 오리지널 제품의 이익률에 압박을 가하고 있습니다.
단일 표적 GLP-1 수용체 작용제는 2025년에 290억 7,000만 달러의 매출을 창출하며, GLP-1 당뇨병 치료제 시장 규모의 81.62% 점유율을 유지했습니다. 반면, 이중 GIP/GLP-1 작용제는 매출액 기준으로는 여전히 규모가 작지만, 연평균 성장률(CAGR) 6.02%를 기록하며 후기 개발 단계에 있는 파이프라인의 대부분을 뒷받침하고 있습니다. 임상 현장에서 기대감이 높아지는 것은 HbA1c 수치와 체중을 탁월하게 감소시키는 효과에 기인하며, 이를 통해 복약 순응도가 향상되고 투여 간격을 연장할 수 있게 됩니다. 트리플 작용제는 중기 임상시험 단계에 진입했으며, 지질 저하 및 에너지 소비량 증가 등 대사 측면에서의 효과를 확대할 가능성이 있습니다. SGLT-2 억제제는 보조적인 역할을 유지하고 있으며, 심신 보호를 목적으로 병용되는 경우가 많은 반면, 아밀린 유사체는 식후 혈당 조절에 특화되어 있어 여전히 틈새 시장으로 자리 잡고 있습니다.
시장의 변천은 사소한 제제 개선에서 수용체의 시너지 효과를 가져오는 획기적인 진보로의 전략 전환을 여실히 보여주고 있습니다. 멀티아고니스트가 승인을 획득함에 따라, 보험 급여 당국은 위험 감소 효과가 뛰어난 프로파일을 높이 평가할 가능성이 있으며, 이는 2020년대 후반 GLP-1 당뇨병 치료제 시장의 지속적인 확장을 뒷받침했습니다.
지역별 분석
북미는 2025년에 153억 3,000만 달러의 매출을 기록했으며, 이는 GLP-1 계열 당뇨병 치료제 시장의 43.02%에 해당합니다. 고용주 주도의 커브아웃(보험 적용 제외)으로 도입이 가속화되는 한편, FDA는 새로운 적응증 승인을 신속히 처리하고 있어, 지불 주체의 규제가 있음에도 불구하고 높은 가격대가 유지되고 있습니다. 캐나다에서는 미국과 유사한 조합 추세가 나타나고 있지만, 보험 환급은 보다 보수적입니다. 반면 멕시코에서는 공공 자금 공급이 여전히 분산된 가운데 민간 부문이 성장을 주도하고 있습니다. 원격 의료를 통한 처방전 발급이 확대되고 있으며, 특히 미국에서는 LillyDirect 및 Teladoc과의 제휴를 통해 오프라인 매장 이외의 환경으로의 접근성이 확대되고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 7.52%로 가장 빠르게 성장하는 지역입니다. 중국은 GZR18과 같은 국내 후보 의약품을 뒷받침하는 규제 현대화를 통해 발전을 주도하고 있으며, 경쟁적인 가격 책정을 촉진하고 있습니다. 인도에서는 당뇨병 부담이 병행 성장을 주도하고 있으며, 정부 데이터에 따르면 제조 인프라 확충에 힘입어 2034년 연평균 성장률(CAGR)은 24.7%로 예상됩니다. 일본이나 한국과 같은 성숙한 시장에서는 국민건강보험제도로 인해 신약이 신속하게 도입되는 반면, 호주에서는 고도의 의약품 급여 제도(Pharmaceutical Benefits Scheme)를 활용하여 획기적인 치료법을 승인 후 즉시 목록에 추가하고 있습니다.
유럽은 꾸준한 점진적 성장에 기여하고 있습니다. 독일, 영국, 프랑스는 탄탄한 당뇨병 관리 프로그램을 활용하여 시장의 대부분을 차지하고 있습니다. 유럽의약품청(EMA)의 심사 신속화로 인해 FDA와의 기존 격차가 좁혀지며, 출시 시기의 동기화가 촉진되고 있습니다. 이탈리아와 스페인을 포함한 남유럽 국가들에서는 공적 의료 제도에 따른 비만 치료 적용 범위 확대에 따라 수요가 증가하고 있습니다. 기타 유럽 시장에서는 콜드체인 역량을 강화하는 구조 기금의 혜택을 받고 있어, 치료법의 접근성이 확대되면서 GLP-1 계열 당뇨병 치료제 시장이 지역 전체적으로 성장하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측(금액, 10억 달러)
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the weight loss diabetes drug market size is expected to grow from USD 35.62 billion in 2025 to USD 37.48 billion in 2026 and is forecast to reach USD 48.27 billion by 2031 at 5.21% CAGR over 2026-2031.
This report is Segmented by Drug (Trulicity, Victoza, Ozempic, and More), Mechanism of Action (GLP-1 Receptor Agonists, Dual GIP/GLP-1 Agonists, and More), Route of Administration (Injectable, Oral), Distribution Channel (Hospital Pharmacies, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Weight Loss Diabetes Drug Market Trends and Insights
Rising Obesity-Diabetes Comorbidity
Escalating obesity rates now exceed 40% among U.S. adults and intersect with an estimated 88 million individuals living with prediabetes . GLP-1 therapies uniquely tackle both conditions, delivering the 20.2% weight loss observed with tirzepatide compared with 13.7% for semaglutide in pivotal trials. Payers recognize the long-term cost offsets of early metabolic intervention, prompting broader benefit coverage across employer and commercial plans. Clinicians increasingly prescribe GLP-1 agents as first-line therapy for metabolic syndrome, driving prescription growth beyond traditional diabetes confines. The resulting demand underpins the near-term expansion of the GLP-1 diabetes drugs market even as pricing pressure intensifies.
Breakthrough GLP-1 & Dual Agonist Efficacy
Superior outcomes from dual agonists such as tirzepatide reinforce a shift toward multi-target innovation. Head-to-head data show HbA1c reductions of 2.0-2.3 percentage points versus 1.6-1.9 points for single-receptor comparators . Chinese developers add further momentum; Gan & Lee's GZR18 produced up to 2.32 point HbA1c declines alongside greater weight loss than Ozempic. Pipeline triple agonists targeting GLP-1, GIP, and glucagon reveal early metabolic gains that could reset therapeutic benchmarks after 2027. These efficacy advantages support premium pricing, fortify physician confidence, and propel the GLP-1 diabetes drugs market toward higher competitive complexity.
High Therapy Cost & Patchy Reimbursement
Monthly therapy costs ranging from USD 1,000 to USD 1,600 restrict access outside affluent economies. Medicare excludes weight loss indications, while U.S. Medicaid coverage variegates by state, causing marked uptake disparity. In emerging markets reimbursement gaps curb initial prescriptions despite rising prevalence, capping near-term volumes. Employer cost controls intensify: 78% already impose prior authorizations or step therapy. Without broad financing reforms, price sensitivity will temper the otherwise strong GLP-1 diabetes drugs market growth trajectory.
Other drivers and restraints analyzed in the detailed report include:
- Faster Regulatory Approvals & Label Expansions
- Employer-Driven GLP-1 Coverage Carve-Outs
- Ongoing GLP-1 Supply Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The GLP-1 diabetes drugs market size for brand-level competition shows Ozempic at USD 11.36 billion revenue in 2025, translating to a 31.88% GLP-1 diabetes drugs market share. Mounjaro follows with lower absolute sales but a leading 5.86% CAGR outlook to 2031 on the strength of dual-receptor efficacy. Physicians continue prescribing Trulicity due to familiarity, yet payer formularies increasingly pivot to Mounjaro as outcomes data accumulate. Victoza's first generic entry in 2024 depresses branded volume though maintains relevance among patients intolerant to newer agents. Saxenda's growth remains constrained by weight-loss coverage gaps despite clinical benefits. Emerging Chinese molecules such as GZR18 promise to disrupt incumbents by pairing high efficacy with aggressive pricing, reinforcing global competition and fostering broader access.
Early adoption curves from 2020-2024 highlight Ozempic's rapid climb, but forecast dynamics favor dual and triple agonists. The GLP-1 diabetes drugs market consequently balances mature blockbuster sustainability against next-wave innovation cycles. As Mounjaro collects longer safety datasets and real-world evidence, formulary positions may shift, accelerating its share gain at Ozempic's expense. Generic liraglutide also nudges pricing downward in older patient cohorts, broadening entry points but pressuring originator margins.
Single-target GLP-1 receptor agonists generated USD 29.07 billion in 2025, preserving 81.62% share of the GLP-1 diabetes drugs market size. However, dual GIP/GLP-1 agonists, though still small by value, deliver 6.02% CAGR and anchor most late-stage pipelines. Clinical enthusiasm stems from superior HbA1c and weight reductions that boost adherence and extend dosing intervals. Triple agonists enter mid-stage trials with potential to broaden metabolic benefits, including lipid lowering and energy expenditure increases. SGLT-2 inhibitors retain adjunctive roles, often combined for cardiorenal protection, while amylin analogues remain niche given specificity to postprandial control.
Market evolution underscores the strategy shift from marginal formulation tweaks to receptor-synergistic breakthroughs. As multi-agonists secure approvals, reimbursement authorities may reward stronger risk-reduction profiles, underpinning sustained GLP-1 diabetes drugs market expansion in the latter half of the decade.
Complete Report Scope:
- By Drug
- Trulicity
- Victoza
- Ozempic
- Saxenda
- Mounjaro
- Others
- By Mechanism of Action
- GLP-1 Receptor Agonists
- Dual GIP/GLP-1 Agonists
- SGLT-2 Inhibitors
- Amylin Analogues
- By Route of Administration
- Injectable
- Oral
- By Distribution Channel
- Hospital Pharmacies
- Retail & Community Pharmacies
- Online/Tele-pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America produced USD 15.33 billion sales in 2025, equal to 43.02% of the GLP-1 diabetes drugs market. Employer-led carve-outs accelerate uptake, while the FDA fast-tracks new indications, sustaining premium prices despite payer controls. Canada mirrors U.S. prescription momentum though reimburses more conservatively, whereas Mexico's private sector drives growth as public funding remains fragmented. Telehealth prescribing proliferates, particularly within the United States, where LillyDirect and Teladoc alliances expand reach beyond brick-and-mortar settings.
Asia-Pacific represents the fastest-growing territory with 7.52% CAGR. China spearheads progress through regulatory modernization that backs domestic candidates like GZR18, amplifying competitive pricing. India's diabetes burden sparks parallel growth with expected CAGR of 24.7% to 2034 per government data, supported by expanding manufacturing infrastructure. Mature markets such as Japan and South Korea adopt newer molecules quickly due to universal coverage systems, while Australia leverages a progressive Pharmaceutical Benefits Scheme to list breakthrough therapies soon after approval.
Europe contributes steady incremental gains. Germany, United Kingdom, and France comprise the lion's share, leveraging robust diabetes management programs. The European Medicines Agency's speedier reviews narrow the historical gap with the FDA, encouraging synchronized launches. Southern European countries, including Italy and Spain, amplify demand as public systems widen obesity coverage. The rest of Europe market benefits from structural funds bolstering cold-chain capacity, facilitating broader therapy availability and propelling the GLP-1 diabetes drugs market regionwide.
- Novo Nordisk
- Eli Lilly and Company
- Boehringer Ingelheim
- AstraZeneca
- Sanofi
- Pfizer
- Amgen
- Viking Therapeutics
- Innovent Biologics
- Zealand Pharma
- Roche
- Merck
- GlaxoSmithKline
- Hanmi Pharm
- LG Chem
- Jiangsu Hansoh
- Bayer
- Novartis
- Harman Finochem
- Amylin Pharmaceuticals
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Obesity-Diabetes Comorbidity
- 4.2.2 Breakthrough Glp-1 & Dual Agonist Efficacy
- 4.2.3 Faster Regulatory Approvals & Label Expansions
- 4.2.4 Employer-Driven Glp-1 Coverage Carve-Outs
- 4.2.5 Telehealth-Enabled D2C Prescribing Surge
- 4.2.6 Chinese Long-Acting Innovation Driving Price Resets
- 4.3 Market Restraints
- 4.3.1 High Therapy Cost & Patchy Reimbursement
- 4.3.2 Ongoing Glp-1 Supply Constraints
- 4.3.3 Intensified Safety-Signal Surveillance (E.G., Sarcopenia)
- 4.3.4 Proliferation Of Compounded Generics Eroding Asps
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 Market Size & Growth Forecasts (Value, USD Bn)
- 5.1 By Drug
- 5.1.1 Trulicity
- 5.1.2 Victoza
- 5.1.3 Ozempic
- 5.1.4 Saxenda
- 5.1.5 Mounjaro
- 5.1.6 Others
- 5.2 By Mechanism of Action
- 5.2.1 GLP-1 Receptor Agonists
- 5.2.2 Dual GIP/GLP-1 Agonists
- 5.2.3 SGLT-2 Inhibitors
- 5.2.4 Amylin Analogues
- 5.3 By Route of Administration
- 5.3.1 Injectable
- 5.3.2 Oral
- 5.4 By Distribution Channel
- 5.4.1 Hospital Pharmacies
- 5.4.2 Retail & Community Pharmacies
- 5.4.3 Online/Tele-pharmacies
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Novo Nordisk
- 6.3.2 Eli Lilly
- 6.3.3 Boehringer Ingelheim
- 6.3.4 AstraZeneca
- 6.3.5 Sanofi
- 6.3.6 Pfizer
- 6.3.7 Amgen
- 6.3.8 Viking Therapeutics
- 6.3.9 Innovent Biologics
- 6.3.10 Zealand Pharma
- 6.3.11 Roche
- 6.3.12 Merck KGaA
- 6.3.13 GSK
- 6.3.14 Hanmi Pharm
- 6.3.15 LG Chem
- 6.3.16 Jiangsu Hansoh
- 6.3.17 Bayer
- 6.3.18 Novartis
- 6.3.19 Harman Finochem
- 6.3.20 Amylin Pharmaceuticals
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment