

|
시장보고서
상품코드
2154845
남미의 경구 항당뇨병약 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America Oral Anti-Diabetic Drugs - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
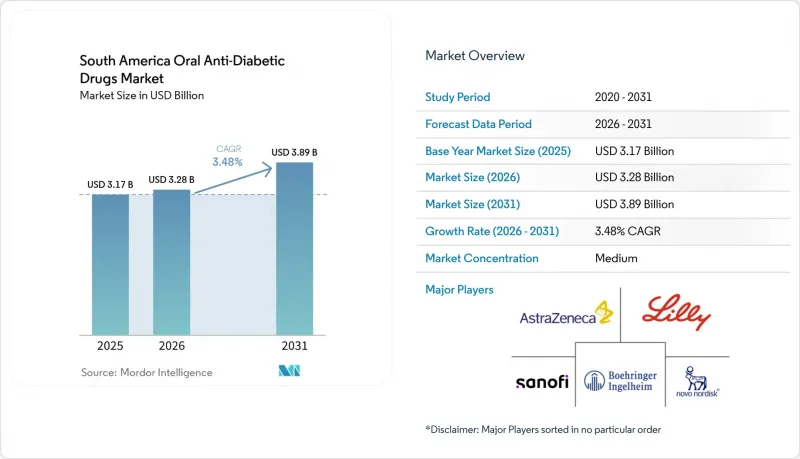
에 따르면 남미의 경구 당뇨병 치료제 시장 규모는 2025년 31억 7,000만 달러에서 2026년에는 32억 8,000만 달러로 확대하며, 2026-2031년에 CAGR 3.48%로 추이하며, 2031년에는 38억 9,000만 달러에 달할 것으로 예측됩니다.
남미 경구용 당뇨병 치료제 시장의 동향 및 인사이트
제2형 당뇨병 치료 대상자의 확대
남미 전역에서 제2형 당뇨병으로 진단받은 환자 수가 증가하고 있으며, 이는 공공 및 민간 의료 현장에서 일상적인 경구 치료에 대한 수요를 지원하고 있습니다. 국제당뇨병연맹(IDF)의 추산에 따르면 2024년 기준 남미 및 중남미 성인 3,540만 명이 당뇨병을 앓고 있으며, 이 중 30.4%에 해당하는 1,070만 명은 미진단 상태였습니다. 브라질, 페루, 파나마, 볼리비아에서는 지난 5년 동안 전국 규모의 당뇨병 조사가 실시되어, 선별 검사 프로그램, 지역 환자 등록 제도 및 조기 치료 의뢰에 관한 근거 기반이 강화되었습니다. IDF는 2050년까지 이 지역의 당뇨병 환자 수가 46% 증가하여 5,200만 명에 달할 것으로 예측하고 있으며, 이는 향후 치료 대상 인구가 단기적인 진단 구상의 범위를 넘어선다는 사실을 지원합니다. 이미 당뇨병을 앓고 있는 사람들을 보다 정확하게 파악함으로써, 기초 질환 발생률에 변화가 생기기 전부터 남미의 경구용 당뇨병 치료제 시장에서 미충족 의료 수요를 처방으로 연결하는 것이 가능해집니다.
SGLT2 억제제의 심혈관 및 신장에 대한 유익성
SGLT2 억제제는 혈당 조절 이외의 용도로도 사용되고 있습니다. 이는 심혈관 및 신장에 대한 그 역할이 임상 지침과 전문의의 진료 현장에서 확대되고 있기 때문입니다. 2억 300만 명을 대상으로 한 브라질의 연구에 따르면 2021년에 도입된 다파글리플로진의 공적 보험 적용은 2017년 기준치와 비교하여 2024년까지 심혈관 사망률을 19.1% 감소시키는 것과 관련이 있는 것으로 밝혀졌습니다. KDIGO 2024 지침에서는 만성 신장병 관리의 일환으로 SGLT2 억제제가 권장되고 있으며, 이로 인해 신장 의료 분야에서 그 중요성이 확대되고, 동반 질환이 있는 환자에서의 역할이 더욱 강화되고 있습니다. 심장내과 및 신장내과 의료진은 제2형 당뇨병을 동반한 많은 환자를 진료하고 있으므로, 이 지침에 따라 처방 가능한 의사의 범위가 내분비과나 일반 당뇨병 클리닉 이외의 분야로 확대될 것입니다. 이러한 임상적 역할의 확대는 남미의 경구 당뇨병 치료제 시장, 특히 브라질, 아르헨티나, 콜롬비아의 도시 지역 전문 의료 현장에서 이러한 치료제에 대한 수요를 지원할 것입니다.
높은 본인 부담금으로 인한 약제비 부담
메트포르민보다 비싼 2차 및 3차 경구용 치료제의 경우, 특히 보험 적용 범위가 불충분한 지역에서 여전히 경제적 부담이 장벽으로 작용하고 있습니다. 콜롬비아의 연구에 따르면 제2형 당뇨병 환자의 23%가 질환 관리 프로그램에서 막대한 본인 부담 약값을 지불하고 있는 것으로 나타났습니다. 동 조사에 따르면 이 지역 전체 의료비 총액의 39.5%를 본인부담금이 차지하고 있으며, 의약품에 대한 경제적 부담이 가계 의료비 부담 전체에서 큰 비중을 차지하고 있음을 보여줍니다. 아르헨티나에서는 제2형 당뇨병 환자 1인당 직접 치료비 중 의약품비가 80-81%를 차지하고 있으며, 보험 적용이 전액을 커버하지 못하는 경우 환자는 가격 차이의 영향을 받기 쉽습니다. 제네릭 의약품을 통해 가격 차이를 줄일 수는 있지만, 남미의 경구용 당뇨병 치료제 시장에서 저소득층이 많은 지역에서는 경제적 부담이 SGLT2 억제제나 DPP-4 억제제의 보급에 계속해서 영향을 미칠 것으로 보입니다.
부문 분석
2025년, 남미의 경구용 당뇨병 치료제 시장에서 비구아나이드 계열 약물은 43.31%의 점유율을 차지했습니다. 이는 메트포르민이 공공 의약품 리스트에 등재되어 있고, 제네릭 의약품을 구할 수 있다는 점이 배경으로 작용했습니다. 메트포르민은 주요 국가의 시장에서 SUS(브라질 국민건강제도), Farmacia Popular 및 이에 상응하는 공공 지원 프로그램을 통해 제공되고 있습니다. 설포닐우레아 계열 약물 및 DPP-4 억제제는 메트포르민 단독 요법을 넘어 치료가 진행되는 환자를 대상으로 합니다. 시타글립틴, 빌다글립틴, 리나글립틴의 경우, 특허 만료에 따라 제네릭 의약품의 존재감이 높아지고 있습니다. 고정 용량 복합제 또한 처방 의사가 단일 요법을 넘어 치료를 단계적으로 강화할 때 유용하게 활용되고 있습니다. 이 제형을 통해 환자의 치료 계획에 사용되고 있는 확립된 약물 군을 유지하면서 개별 조제 횟수를 줄일 수 있습니다.
SGLT2 억제제는 2026-2031년에 연평균 성장률(CAGR) 6.58%로 성장할 것으로 예측됩니다. 이에 비해 남미의 경구용 당뇨병 치료제 시장 전체의 연평균 성장률(CAGR)은 3.48%입니다. 다파글리플로진과 엠파글리플로진은 당뇨병 전문 의료의 범위를 넘어 사용되므로 순환기학 및 신장학 분야에서도 중요한 역할을 하고 있습니다. α-글루코시다아제 억제제, 도파민 D2 수용체 작용제 및 메글리티니드 계열 약물은 전문의 주도의 제한적인 역할에 그치고 있습니다. 경구용 GLP-1 수용체 작용제(주로 리베르사스)는 공적 보험에 의한 환급이 제한적이기 때문에 여전히 고가의 민간 의료 채널에 집중되어 있습니다.
제2형 당뇨병은 2025년 매출의 89.24%를 차지하며, 2031년까지 연평균 성장률(CAGR) 4.22%로 확대될 것으로 예측됩니다. 이 환자 집단의 규모는 2024년 기준 3,500만 명의 성인이 당뇨병을 앓고 있다는 지역적 당뇨병 부담을 반영합니다. 선별 검사 및 환자 등록이 개선됨에 따라 치료 시작률은 상승할 가능성이 있습니다. 또한 치료 진행 단계에서 초기 메트포르민 요법에 SGLT2 억제제나 복합제를 추가하는 것도 가능합니다.
전당뇨 및 인슐린 저항성은 여전히 미충족 의료 수요가 있는 분야이며, 2024년에는 남미 및 중남미에서 3,220만 명이 공복 혈당 이상을 보일 것으로 추정됩니다. 브라질의 ‘SBD 2026’ 조제 지침에서는 당뇨병 전단계 관리가 공공 투자의 우선순위로 자리 잡고 있습니다. ‘파르마시아 포풀라르(Farmacia Popular)’를 통한 메트포르민의 무료 제공으로 조기 개입에 따른 비용적 장벽이 낮아지고 있습니다. 전당뇨에 특히 적응증이 있는 경구용 치료제에 대한 보험 급여는 대부분의 국가에서 여전히 제한적입니다. 제1형 당뇨병의 보조 경구 요법은 이 지역의 치료 구성에서 여전히 작은 비중을 차지하고 있습니다. SGLT2 억제제는 대학병원에서 인슐린 요법에 대한 적응증 외 병용으로 신중하게 사용되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 약제 클래스별
- 당뇨병 유형별
- 제제별
- 유통 채널별
- 국가별
- 브라질
- 아르헨티나
- 콜롬비아
- 칠레
- 페루
- 기타 남미 국가
제6장 경쟁 구도
- 시장 집중도
- 시장 점유율 분석
- 기업 개요
- AstraZeneca PLC
- Biomm S.A.
- Boehringer Ingelheim International GmbH
- Eli Lilly and Company
- EMS S.A.
- Eurofarma Laboratorios S.A.
- Grupo Farmaceutico Somar
- Hypera S.A.
- Johnson & Johnson
- Laboratorios Bago S.A.
- Laboratorios Roemmers S.A.
- Merck & Co., Inc.
- Novartis AG
- Novo Nordisk A/S
- Pfizer Inc.
- Sanofi S.A.
- Takeda Pharmaceutical Company Limited
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the South America oral Anti-Diabetic drugs market size is expected to grow from USD 3.17 billion in 2025 to USD 3.28 billion in 2026 and is forecast to reach USD 3.89 billion by 2031 at 3.48% CAGR over 2026-2031.
South America Oral Anti-Diabetic Drugs Market Trends and Insights
Expanding Type 2 Diabetes Treatment Pool
The diagnosed Type 2 Diabetes population is expanding across South America, supporting demand for routine oral treatment in public and private care settings. The International Diabetes Federation estimated that 35.4 million adults in South and Central America had diabetes in 2024, and 30.4%, or 10.7 million people, were undiagnosed. Brazil, Peru, Panama, and Bolivia have conducted national diabetes studies during the past 5 years, strengthening the evidence base for screening programs, local patient registries, and earlier treatment referrals. The IDF projects that the regional diabetes population will increase by 46% to 52 million by 2050, confirming that the prospective treatment population extends beyond a short-term diagnosis initiative. Better identification of people already living with diabetes can translate unmet clinical need into prescriptions within the South America oral anti-diabetic drugs market, even before changes in the underlying rate of disease occurrence.
Cardiovascular and Renal Benefits of SGLT2 Inhibitors
SGLT2 inhibitors are being used beyond glycemic control because their cardiovascular and renal roles have expanded across clinical guidelines and specialist practice. A Brazilian study of 203 million people found that public dapagliflozin access, introduced in 2021, was associated with a 19.1% reduction in cardiovascular mortality rates by 2024 relative to the 2017 baseline. The KDIGO 2024 guideline recommended SGLT2 inhibitors as part of chronic kidney disease management, which broadens their relevance in renal care and reinforces their role in patients with comorbid conditions. Cardiology and nephrology providers manage many patients with coexisting Type 2 Diabetes, so this guidance expands the potential prescriber base beyond endocrinology and general diabetes clinics. This wider clinical role supports demand for these therapies in the South America oral anti-diabetic drugs market, particularly in urban specialty care settings in Brazil, Argentina, and Colombia.
High Out-of-Pocket Medication Burden
Affordability remains a constraint for second-line and third-line oral treatments that cost more than metformin, particularly where insurance coverage is incomplete. A Colombian study found that 23% of people with Type 2 Diabetes incurred significant out-of-pocket medicine costs within a disease management program. The same source reported that out-of-pocket payments represented 39.5% of total health expenditure across the region, placing medicine affordability within a wider household healthcare burden. In Argentina, medicines accounted for 80-81% of direct Type 2 Diabetes treatment costs per patient, leaving patients sensitive to price differences when coverage does not meet the full cost. Generic medicines can narrow price gaps, but affordability will continue to affect the adoption of SGLT2 inhibitors and DPP-4 inhibitors in lower-income parts of the South America oral anti-diabetic drugs market.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Fixed-Dose Combination Tablets
- Growth of Digital Refills and Online Pharmacy Access
- Substitution by Injectable and Weight-Management Therapies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Biguanides held 43.31% of the South America oral anti-diabetic drugs market share in 2025, supported by metformin's presence in public formularies and generic availability. Metformin is provided through SUS, Farmacia Popular, and comparable public subsidy programs in the main country markets. Sulfonylureas and DPP-4 inhibitors serve patients whose treatment progresses beyond metformin monotherapy. Sitagliptin, vildagliptin, and linagliptin have a growing generic presence after patent expirations. Fixed-dose combinations also support treatment escalation when prescribers move beyond monotherapy. The format reduces separate dispensing while retaining the established medicine classes used in a patient's regimen.
SGLT2 inhibitors are forecast to grow at a 6.58% CAGR from 2026 to 2031, compared with the overall 3.48% CAGR for the South America oral anti-diabetic drugs market size. Dapagliflozin and empagliflozin have relevance in cardiology and nephrology because their use extends beyond diabetes specialty care. Alpha-glucosidase inhibitors, dopamine D2 receptor agonists, and meglitinides retain smaller specialist-led roles. Oral GLP-1 receptor agonists, primarily Rybelsus, remain concentrated in premium private channels because public reimbursement is limited.
Type 2 Diabetes represented 89.24% of revenue in 2025 and is forecast to expand at a 4.22% CAGR through 2031. The size of this patient group reflects a regional diabetes burden of 35 million adults in 2024. Treatment initiation rates can rise as screening and patient registration improve. Later treatment stages can also add SGLT2 inhibitors and combination tablets to initial metformin therapy.
Prediabetes and insulin resistance remain areas of unmet need, with 32.2 million people in South and Central America estimated to have impaired fasting glucose in 2024. The Brazilian SBD 2026 dispensing guideline identifies prediabetes management as a priority for public investment. Free metformin access through Farmacia Popular lowers the cost barrier for early intervention. Reimbursement for oral treatment specifically indicated for prediabetes remains limited in most countries. Type 1 Diabetes adjunctive oral therapy remains a small segment within the regional treatment mix. SGLT2 inhibitors are used cautiously as off-label additions to insulin in academic medical centers.
Complete Report Scope:
- By Drug Class
- Biguanides
- Sulfonylureas
- Dipeptidyl Peptidase-4 Inhibitors
- Sodium-Glucose Cotransport-2 Inhibitors
- Alpha-Glucosidase Inhibitors
- Dopamine D2 Receptor Agonists
- Meglitinides
- Oral GLP-1 Receptor Agonists
- Fixed-Dose Combination Oral Therapies
- By Diabetes Type
- Type 2 Diabetes
- Type 1 Diabetes Adjunctive Oral Therapy
- Prediabetes and Insulin Resistance
- By Formulation
- Immediate-Release Tablets
- Extended-Release Tablets
- Film-Coated Tablets
- Other Formulations
- By Distribution Channel
- Retail Pharmacies
- Hospital Pharmacies
- Online Pharmacies
- Other Distribution Channels
- By Country
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
List of Companies Covered in this Report:
- AstraZeneca
- Biomm S.A.
- Boehringer Ingelheim
- Eli Lilly and Company
- EMS S.A.
- Eurofarma Laboratorios S.A.
- Grupo Farmaceutico Somar
- Hypera S.A.
- Johnson & Johnson
- Laboratorios Bago S.A.
- Laboratorios Roemmers S.A.
- Merck
- Novartis
- Novo Nordisk
- Pfizer
- Sanofi
- Takeda Pharmaceuticals
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding Type 2 Diabetes Treatment Pool
- 4.2.2 Metformin-Led Public-Sector Treatment Access
- 4.2.3 Cardiovascular and Renal Benefits of SGLT2 Inhibitors
- 4.2.4 Shift Toward Fixed-Dose Combination Tablets
- 4.2.5 Growth of Digital Refills and Online Pharmacy Access
- 4.2.6 Local Generic and Technology-Transfer Capacity
- 4.3 Market Restraints
- 4.3.1 High Out-of-Pocket Medication Burden
- 4.3.2 Unequal Rural Diagnosis and Treatment Access
- 4.3.3 Regulatory and Reimbursement Fragmentation
- 4.3.4 Substitution by Injectable and Weight-Management Therapies
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Drug Class
- 5.1.1 Biguanides
- 5.1.2 Sulfonylureas
- 5.1.3 Dipeptidyl Peptidase-4 Inhibitors
- 5.1.4 Sodium-Glucose Cotransport-2 Inhibitors
- 5.1.5 Alpha-Glucosidase Inhibitors
- 5.1.6 Dopamine D2 Receptor Agonists
- 5.1.7 Meglitinides
- 5.1.8 Oral GLP-1 Receptor Agonists
- 5.1.9 Fixed-Dose Combination Oral Therapies
- 5.2 By Diabetes Type
- 5.2.1 Type 2 Diabetes
- 5.2.2 Type 1 Diabetes Adjunctive Oral Therapy
- 5.2.3 Prediabetes and Insulin Resistance
- 5.3 By Formulation
- 5.3.1 Immediate-Release Tablets
- 5.3.2 Extended-Release Tablets
- 5.3.3 Film-Coated Tablets
- 5.3.4 Other Formulations
- 5.4 By Distribution Channel
- 5.4.1 Retail Pharmacies
- 5.4.2 Hospital Pharmacies
- 5.4.3 Online Pharmacies
- 5.4.4 Other Distribution Channels
- 5.5 By Country
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Colombia
- 5.5.4 Chile
- 5.5.5 Peru
- 5.5.6 Rest of South America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 AstraZeneca PLC
- 6.3.2 Biomm S.A.
- 6.3.3 Boehringer Ingelheim International GmbH
- 6.3.4 Eli Lilly and Company
- 6.3.5 EMS S.A.
- 6.3.6 Eurofarma Laboratorios S.A.
- 6.3.7 Grupo Farmaceutico Somar
- 6.3.8 Hypera S.A.
- 6.3.9 Johnson & Johnson
- 6.3.10 Laboratorios Bago S.A.
- 6.3.11 Laboratorios Roemmers S.A.
- 6.3.12 Merck & Co., Inc.
- 6.3.13 Novartis AG
- 6.3.14 Novo Nordisk A/S
- 6.3.15 Pfizer Inc.
- 6.3.16 Sanofi S.A.
- 6.3.17 Takeda Pharmaceutical Company Limited
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


