|
시장보고서
상품코드
2121503
유럽의 농업용 트랙터 및 기계 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Agricultural Tractor Machinery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
유럽의 농업용 트랙터 및 기계 시장 규모는 2025년에 132억 달러로 평가되며, 2026년 139억 6,000만 달러에서 2031년까지 184억 5,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 5.74%가 될 전망입니다.
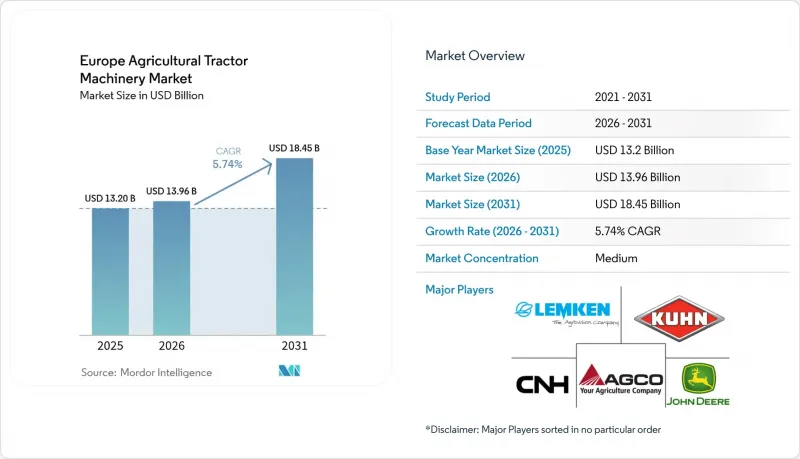
본 보고서는 기계 종류(경운·경작 기계, 파종 기계 등) 및 지역(독일, 프랑스, 이탈리아 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
유럽 농업용 트랙터 및 기계 시장 동향 및 인사이트
EU 공동농업정책(CAP)에 기반한 정밀 농업에 대한 보조금(2025-2027년 기간)
의무화된 친환경 제도에 따라 직접 지급액의 25%가 투입 효율이 입증된 프로젝트에 배정되게 되어, 농가들은 가변 시비율 파종기, ISOBUS 호환 분무기, 수확량 매핑용 센서의 구매를 강요받고 있습니다. 프랑스, 독일, 폴란드에서는 이러한 설비의 업그레이드가 진행되고 있습니다. 이러한 도입 확대에 따라 데이터 공유도 촉진되고 있습니다. 협동조합 ‘Terrena’에서는 2024년에 회원의 38%가 농기계의 원격 측정 시스템을 도입하여 장비의 수명을 15% 연장했습니다. 인증 요건에 따라 ISO 11783을 준수하는 브랜드가 우대받고, 소규모 공급업체는 보조금 수혜 자격에서 배제되기 때문에 수요는 소수의 대규모 텔레매틱스 생태계에 집중되고 있습니다.
서유럽 및 북유럽의 노동력 부족이 자동화 수요를 가속화
2024년, 독일 농업 분야의 정규직 고용자 수는 전년 대비 12% 감소했습니다. 네덜란드 원예 업계도 유사한 노동력 부족에 직면해 있어, 로봇식 식재기 및 비전 가이드식 살포기의 도입이 가속화되고 있습니다. Deere and Company사는 2024년 한 해 동안 유럽으로 수출된 ‘See and Spray’ 시스템 출하대수가 47% 증가했다고 보고했습니다. Danish Agro사는 15대의 자율형 수확기 및 컨디셔너를 도입해 밤낮으로 가동함으로써 건초 수확 인건비를 30% 절감했습니다. 따라서 유럽의 농업용 트랙터 및 기계 시장은 자율 기능을 탑재한 동력 작업기로 기울고 있으며, 기존의 수동형 작업기와의 격차가 확대되고 있습니다.
2023년 이후 누적된 딜러의 과잉 재고가 2026년까지 신규 주문을 억제
2024년 초, 유럽 딜러가 보유한 작업기 재고는 통상 5.5개월 분량에 비해 9.2개월 분량에 달했습니다. BayWa사는 미판매 경운·파종용 재고로 3억 4,000만 유로(3억 6,000만 달러)를 계상하고, 2025년 구매 계획을 22% 축소했습니다. 프랑스의 판매 대리점 InVivo 역시 신규 주문을 18% 줄이고, 중고 장비의 재생 판매로 사업 방향을 전환했습니다. 제조사는 지급 기한을 180일로 연장하고 위탁 판매도 제안했으나, 이익률 압박으로 인해 딜러들은 신형 모델 재고 확보를 주저하고 있어, 유럽 농업용 트랙터 및 기계 시장의 단기적 성장을 둔화시키고 있습니다.
부문 분석
유럽 농업용 트랙터 및 기계 시장에서 2025년 매출의 45.30%를 경운 및 중경용 기계가 차지했습니다. 파종기는 교통량 규제와 실시간 가변 시비 알고리즘의 보급에 힘입어 2031년까지 연평균 성장률(CAGR) 7.66%로 성장할 전망입니다. 프랑스의 협동조합 Axereal은 85,000헥타르에 GPS 섹션 제어를 도입한 결과, 헥타르당 종자 비용이 12% 절감되었다고 보고했습니다.
파종 기계가 가장 빠르게 성장하고 있는 이유는 환경 지원 제도의 보조금이 특히 종자 낭비 감축에 대해 인센티브를 지급하고 있기 때문입니다. 렘켄(Remken)사의 전동 미터식 ‘아즐리트(Azurit)’ 파종기는 28% 더 비싼 가격에 판매되고 있지만, 500헥타르 이상의 농장에서는 3시즌 이내에 투자 비용을 회수할 수 있습니다. 건초·사료용 기계는 계속해서 유럽의 목초지에서 활용되고 있지만, 그 수요는 낙농 및 육우 사육 두수가 안정적인지에 따라 좌우됩니다. 기타 특수 작업용 기계 시장은 여전히 세분화되어 있습니다. 이 부문은 더 광범위한 유럽의 농업용 트랙터 및 기계 시장에서, 보조금 제도와 데이터 활용 능력이 동력 구동형이며 소프트웨어로 정의된 기계로 이익을 이동시키고 있는 실태를 보여줍니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.07According to Mordor Intelligence, the Europe agricultural tractor machinery market size was valued at USD 13.2 billion in 2025 and estimated to grow from USD 13.96 billion in 2026 to reach USD 18.45 billion by 2031, at a CAGR of 5.74% during the forecast period (2026-2031).
This report is Segmented by Machinery Type (Plowing and Cultivating Machinery, Planting Machinery, and More) and by Geography (Germany, France, Italy, and More). Market Forecasts are Provided in Terms of Value (USD).
Europe Agricultural Tractor Machinery Market Trends and Insights
Precision-Farming Subsidies Under the EU Common Agricultural Policy (2025-2027 Tranche)
Mandatory eco-schemes now channel 25% of direct payments into proven input-efficiency projects, pushing farms to buy variable-rate planters, ISOBUS sprayers, and yield-mapping sensors. France, Germany, and Poland are moving toward such upgrades. Adoption lifts data-sharing, cooperative Terrena saw 38% of members stream implement telemetry in 2024, extending equipment life by 15%. Certification requirements favor ISO 11783-compliant brands and squeeze fringe suppliers out of subsidy eligibility, consolidating demand around a few large telematics ecosystems.
Labor Shortages Accelerating Automation Demand in Western and Northern Europe
Full-time farm employment in Germany fell 12% year on year in 2024. Horticulture in the Netherlands faces similar gaps, spurring take-up of robotic planters and vision-guided sprayers. Deere and Company reported a 47% jump in European shipments of its See and Spray system during 2024. Danish Agro deployed 15 autonomous mower-conditioner units that cut hay harvest labor costs by 30% while running day and night. The Europe agricultural tractor machinery market, therefore, tilts toward powered implements with embedded autonomy, widening the gap with legacy passive tools.
Dealer Over-Inventory Amassed Since 2023 Suppressing Fresh Orders through 2026
European dealers carried 9.2 months of implement supply at the start of 2024 versus a normal 5.5 months. BayWa posted EUR 340 million (USD 360 million) in unsold tillage and seeding stock, then cut 2025 purchase plans by 22%. French distributor InVivo similarly trimmed new orders 18% and pivoted to refurbishing used assets. Manufacturers extended payment terms to 180 days and offered consignment, but the margin squeeze still discourages dealers from stocking incremental models, slowing near-term growth in the Europe agricultural tractor machinery market.
Other drivers and restraints analyzed in the detailed report include:
- Stage V Emissions Rules Propelling Retrofit and Replacement of PTO-Efficient Implements
- Growth of Controlled-Traffic Farming Boosting Demand for Lightweight, Wide-Working-Width Tillage Tools
- High Capital Cost for Smart Implements on Fragmented Small Holdings in Eastern Europe
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plowing and cultivating machinery tools secured 45.30% of 2025 revenue in the Europe agricultural tractor machinery market. Planting machinery, aided by controlled-traffic mandates and real-time variable-rate algorithms, will grow at a 7.66% CAGR through 2031. French cooperative Axereal documented a 12% reduction in seed cost per hectare after rolling out GPS section control across 85,000 hectares.
Planting machinery capture the fastest expansion because eco-scheme payments specifically reward reductions in seed waste. Lemken's electric-meter Azurit planter sells at a 28% premium yet pays back within three seasons on farms above 500 hectares. Haying and forage machinery continue to serve the continent's grassland but hinge on stable dairy and beef herds. Other specialty implements remain fragmented. The segment illustrates how subsidy rules and data capability shift profits toward powered, software-defined machines within the wider Europe agricultural tractor machinery market size.
Complete Report Scope:
- By Machinery Type
- Plowing and Cultivating Machinery
- Plows
- Harrows
- Rotovators and Cultivators
- Other Plowing and Cultivating Machinery
- Planting Machinery
- Seed Drills
- Planters
- Spreaders
- Other Planting Machinery
- Haying and Forage Machinery
- Mowers and Conditioners
- Balers
- Other Haying and Forage Machinery
- Sprayers
- Other Types
- Plowing and Cultivating Machinery
- By Country
- Germany
- France
- Italy
- United Kingdom
- Spain
- Netherlands
- Poland
- Rest of Europe
List of Companies Covered in this Report:
- Deere & Company
- CNH Industrial N.V.
- AGCO Corporation
- Kubota Corporation (Kubota Corporation)
- CLAAS KGaA mbH
- Kuhn Group (Bucher Industries AG)
- Lemken GmbH & Co. KG
- SDF Group
- Mahindra & Mahindra Ltd
- Tractors and Farm Equipment Ltd
- Amazonen-Werke H. Dreyer SE
- Pottinger Landtechnik GmbH
- Vaderstad AB
- Maschio Gaspardo S.p.A.
- Salford Group (Linamar Corporation)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Precision-farming subsidies under the EU Common Agricultural Policy (CAP) (2025-2027 tranche)
- 4.2.2 Labor shortages accelerating automation demand in Western and Northern Europe
- 4.2.3 Stage V emissions rules driving retrofit and replacement of PTO-efficient implements
- 4.2.4 Growth of controlled-traffic farming boosting demand for lightweight, wide-working-width tillage tools
- 4.2.5 Surge in vineyard/orchard mechanization in Mediterranean countries
- 4.2.6 Emerging electric-tractor ecosystem requiring low-draw, ISOBUS-ready implements
- 4.3 Market Restraints
- 4.3.1 Dealer over-inventory since 2023 suppressing fresh orders through 2026
- 4.3.2 High capital cost for smart implements on fragmented small holdings in Eastern Europe
- 4.3.3 Complex interoperability standards (ISOBUS, TIM) delaying adoption among mid-size farms
- 4.3.4 Volatile commodity prices lowering farmers cash flow for discretionary equipment
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Threat of Substitutes
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Bargaining Power of Suppliers
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Machinery Type
- 5.1.1 Plowing and Cultivating Machinery
- 5.1.1.1 Plows
- 5.1.1.2 Harrows
- 5.1.1.3 Rotovators and Cultivators
- 5.1.1.4 Other Plowing and Cultivating Machinery
- 5.1.2 Planting Machinery
- 5.1.2.1 Seed Drills
- 5.1.2.2 Planters
- 5.1.2.3 Spreaders
- 5.1.2.4 Other Planting Machinery
- 5.1.3 Haying and Forage Machinery
- 5.1.3.1 Mowers and Conditioners
- 5.1.3.2 Balers
- 5.1.3.3 Other Haying and Forage Machinery
- 5.1.4 Sprayers
- 5.1.5 Other Types
- 5.1.1 Plowing and Cultivating Machinery
- 5.2 By Country
- 5.2.1 Germany
- 5.2.2 France
- 5.2.3 Italy
- 5.2.4 United Kingdom
- 5.2.5 Spain
- 5.2.6 Netherlands
- 5.2.7 Poland
- 5.2.8 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Deere & Company
- 6.4.2 CNH Industrial N.V.
- 6.4.3 AGCO Corporation
- 6.4.4 Kubota Corporation (Kubota Corporation)
- 6.4.5 CLAAS KGaA mbH
- 6.4.6 Kuhn Group (Bucher Industries AG)
- 6.4.7 Lemken GmbH & Co. KG
- 6.4.8 SDF Group
- 6.4.9 Mahindra & Mahindra Ltd
- 6.4.10 Tractors and Farm Equipment Ltd
- 6.4.11 Amazonen-Werke H. Dreyer SE
- 6.4.12 Pottinger Landtechnik GmbH
- 6.4.13 Vaderstad AB
- 6.4.14 Maschio Gaspardo S.p.A.
- 6.4.15 Salford Group (Linamar Corporation)