

|
시장보고서
상품코드
2121909
상처 관리 기기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Wound Care Management Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
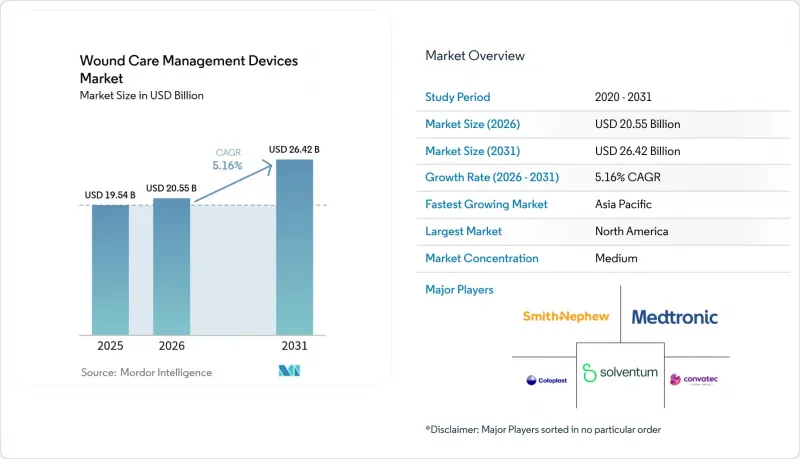
에 의하면, 상처 관리 기기 시장 규모는 2025년에 195억 4,000만 달러로 평가되었고, 2026년 205억 5,000만 달러에서 2031년까지 264억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.16%를 기록할 전망입니다.
본 보고서는 제품별(상처 관리(드레싱, 상처 관리 기기 등) 및 상처 봉합), 상처 유형별(만성 상처 및 급성 상처), 최종 사용자별(병원·전문 상처 클리닉 등), 구매 형태별(기관 조달 및 소매/OTC 채널),지역별(북미 등)로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 상처 관리 기기 시장 동향 및 인사이트
만성 상처 및 당뇨병성 상처 발생률 증가
현재 당뇨병성 족부 궤양은 당뇨병 환자의 15%에게 영향을 미치고 있으며, 병원들은 첨단 드레싱과 연속 혈당 모니터링을 결합한 다학제적 협력 프로그램 도입을 추진하고 있습니다. 시간 제어형 중적외선 광음향 센서를 통해 특정 깊이의 혈당 수치를 측정할 수 있게 되어, 임상의는 합병증이 발생하기 전에 치료법을 조정할 수 있게 되었습니다. 조기 개입 전략으로 인해 입원 일수가 단축되고 절단 위험도 감소하고 있습니다. 보험사는 드레싱, 센서, 원격 의료를 통한 사후 관리를 보장하는 종합적 지급 제도를 통해 이러한 성과를 높이 평가했습니다. 이에 따라 각 제조업체는 습도, pH, 온도 데이터를 전송하기 위해 전자 장치를 드레싱에 내장하고, 기기 설계를 만성 질환 관리 프로토콜에 부합하도록 조정하고 있습니다.
전 세계 수술 건수 증가
2025년, 전 세계적으로 선택적 수술 및 외상 수술 건수가 회복되면서, 첨단 봉합 스트립, 조직 실런트, NPWT(음압상처치료)용 캐니스터에 대한 수요가 증가했습니다. 두피에 대한 모스 현미경 수술 임상시험에서 핀치 이식술이 2차 치유 프로토콜에 비해 치유 기간을 단축시키는 것으로 확인되었습니다. 외래수술센터(ASC)의 처리 능력이 확대됨에 따라, 당일 퇴원 모델에 적합한 소형 NPWT 펌프가 도입되고 있습니다. 초음파 유도 하의 데브리드먼트는 감염 위험을 사전에 방지했으며, 실시간 영상 진단은 미국의 수술 건수가 많은 병원에서 재입원으로 인한 벌금 비용 절감에 기여했습니다. 이러한 성과로 인해 조달 담당 팀은 예산 제약 속에서도 봉합 제품 포트폴리오를 개편하도록 장려받고 있습니다.
신흥 시장의 제한된 보험 급여
동남아시아와 라틴아메리카의 많은 공적 보험 기관은 여전히 기본적인 거즈만 급여 대상으로 하고 있어, NPWT 및 생체공학 기반 피부 대체재의 보급이 더딘 실정입니다. 지방 진료소에서는 공급망 단절에 직면하는 경우가 많아, 이로 인해 접근성이 더욱 제한되고 있습니다. 각국 정부는 1차 드레싱이 효과를 보이지 않는 당뇨병성 족부 궤양에 대해 고급 드레싱에 대한 보험 급여를 제공하는 단계적 급여 패키지를 시범적으로 도입하고 있지만, 예산 상한선은 여전히 엄격한 상황입니다. 폴리우레탄 폼을 국내에서 조달하여 현지에서 용기에 충전하는 현지 조립 업체들은 가격 장벽을 낮추고 있지만, 임상의에 대한 교육은 뒤처지고 있습니다. 민관 협력(PPP)을 통해 합리적인 가격을 실현하기 위해 의료기기와 성과 연동형 자금 조달을 결합하는 노력이 시작되고 있습니다.
부문별 분석
상처 치료 부문은 2025년 매출의 61.88%를 차지했습니다. 이는 임상의들이 복잡한 증례에 대해 항균 폼, 하이드로파이버, 휴대용 음압상처치료(NPWT) 시스템을 선호하여 채택했기 때문입니다. 이러한 압도적인 점유율은 상처 관리 기기 시장이 감염 위험을 줄이고 육아 조직 형성을 촉진하는 제품으로 지속적으로 전환되고 있음을 여실히 보여줍니다. 스테이플, 접착제, 흡수성 바브 봉합사를 포함한 상처 폐쇄용 제품은 정형외과 및 순환기 분야 수요 증가에 힘입어 2031년까지 연평균 성장률(CAGR)이 5.62%를 나타낼 것으로 예측됩니다. 기존의 거즈는 경증 사례에서 여전히 중요하지만, 수술 후 상처용 은이나 PHMB가 함유된 드레싱에 시장 점유율을 빼앗기고 있습니다.
드레싱에 AI 칩을 탑재한 제조업체들은 습윤 상태에 대한 자동 알림 및 내장된 항균제의 자동 투여를 가능하게 하여, 욕창 예방에 관한 병원의 프로토콜을 충족시키고 있습니다. 한편, 외용 바이오의약품은 병원 약국에서 외래 정맥주사 센터로 이동하며 그 이용 범위를 확대되고 있습니다. 상처 관리 기기 시장에서는 스마트 센서 층과 하이드로겔 제제 저장소를 결합한 복합 제품이 등장하여, 새로 발행된 번들형 CPT 코드에 따른 보험 환급을 지원하고 있습니다. 재료 과학과 디지털 모니터링을 융합한 공급업체들은 그룹 구매 조직(GPO)이 설정하는 입찰에서 협상력을 높이고 있습니다.
2025년 매출액 중 만성 상처가 57.92%를 차지하고 있으며, 이는 당뇨병성 족부 궤양, 욕창, 정맥성 하지 궤양이 자원을 대량으로 소비하는 질환임을 반영합니다. 이러한 적응증은 장기간의 치료가 필요하며, 감사를 통해 재입원 감소가 확인될 경우 보험사는 고가 드레싱의 승인을 내리고 있습니다. 외상 및 수술 후 상처를 포함한 급성 상처는 전 세계 수술 건수 증가에 따라 연평균 성장률(CAGR) 5.74%로 확대되고 있습니다. 화상 치료 센터에서는 이식의 필요성을 줄이기 위해 효소성 지혈제와 생체합성 피부 대체재를 병용하고 있습니다.
전자의무기록에 통합된 예측 알고리즘이 궤양 위험이 있는 환자를 식별하여, 체중 분산용 신발이나 습기 관리용 폼의 조기 사용을 촉진하고 있습니다. 욕창 치료 프로토콜에서는 현재 매트리스의 에어셀을 조절하여 체중을 재분배하는 표면 센서가 채택되고 있습니다. 당뇨병성 궤양 관리에서는 관류 장애를 감지하는 휴대용 이미징 분광계가 활용되고 있으며, 이를 통해 임상의는 치료 과정의 초기 단계에서 혈관 중재를 수행하도록 유도됩니다. 이러한 워크플로우의 변화가 상처 관리 기기 시장에서 프리미엄 제품에 대한 수요를 뒷받침하고 있습니다.
지역별 분석
북미는 상처 관리 기기 시장을 주도하고 있으며, 2025년에는 시장 매출의 39.86%를 차지할 것으로 전망됩니다. 이는 첨단 보험 모델이 고급 드레싱, NPWT(음압상처치료), 생체공학 조직에 자금을 지원하고 있기 때문입니다. 미국에서는 가치 기반 계약에 따른 일괄 지급 제도를 통해 조기 치유와 합병증 감소에 대한 보상이 이루어지기 때문에 병원들은 차세대 하이드로겔 및 센서 탑재 폼의 시범 도입을 촉진하고 있습니다. 미국 식품의약국(FDA)은 저위험 액체 반창고를 510(k) 승인 대상에서 제외하고 있어, 이에 따라 소비자용 제품 시장 출시 기간이 단축되고 있습니다. 캐나다의 단일 지불자 제도에서는 재택 NPWT 시범 사업에 투자하고 있으며, 2025년에는 외래 진료 비용을 18% 절감할 것으로 전망됩니다. 멕시코에서는 수술 시설의 업그레이드를 지속하고 있으며, 중저가 대의 상처 봉합용 스트립 및 폴리우레탄 필름에 대한 입찰을 시작했습니다.
유럽은 여전히 성숙한 시장이지만, 혁신을 수용할 수 있는 환경이 잘 갖춰져 있습니다. 각국의 의료 제도는 치유 기간 단축이 입증된 경우, 센서가 탑재된 드레싱을 포함한 만성 상처 치료 패키지에 자금을 지원하고 있습니다. 독일의 병원에서는 새로운 욕창 보고 의무를 준수하기 위해 AI를 활용한 영상 진단을 도입하고 있으며, 이를 통해 의료기기의 교체가 촉진되고 있습니다. 영국에서는 휴대용 영상 진단 태블릿을 활용한 지역 간호사 주도의 당뇨병성 족부 병변 프로그램이 전개되고 있습니다. 한편, 남유럽에서는 EU 의료기기 규정(MDR)의 문서 요건을 충족하면서도 비용 대비 효과가 높은 하이드로겔이 요구되고 있어, 중저가 공급업체를 위한 틈새 시장이 창출되고 있습니다.
아시아태평양은 의료 인프라 확충과 선택적 수술 건수 증가에 힘입어 상처 관리 기기 시장에서 가장 빠른 성장을 보이고 있으며, 2031년까지 연평균 성장률(CAGR)은 6.03%로 성장을 지속하고, 있습니다. 중국의 중앙집권적 일괄 조달 제도에는 현재 음압상처치료(NPWT) 펌프가 포함되어 있으며, 가격 상한선을 준수하기 위해 캐니스터와 폼 드레싱의 현지 생산이 촉진되고 있습니다. 일본에서는 재택 간호용 드레싱 및 센서 패치의 비용을 환급해 주는 ‘재택 고령화’ 정책이 우선시되고 있으며, 민감한 피부에 적합한 초박형 실리콘 접착제의 혁신이 촉진되고 있습니다. 인도의 주 보험 프로그램에서는 3차 의료기관에서 당뇨병성 족부 궤양용 첨단 드레싱에 대한 급여가 시작되었으며, 2급 도시로 확산되는 유통업체 네트워크 형성이 촉진되고 있습니다. 동남아시아 전역에서는 사립 병원이 원격 피부과 포털을 갖춘 전문 상처 클리닉을 통해 차별화를 꾀하며, 지역 시장에서의 영향력을 확대되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.10According to Mordor Intelligence, the wound care management devices market size was valued at USD 19.54 billion in 2025 and estimated to grow from USD 20.55 billion in 2026 to reach USD 26.42 billion by 2031, at a CAGR of 5.16% during the forecast period (2026-2031).
This report is Segmented by Product (Wound Care [Dressings, Wound-Care Devices, and More] and Wound Closure), Wound Type (Chronic Wounds and Acute Wounds), End User (Hospitals & Specialty Wound Clinics and More), Mode of Purchase (Institutional Procurement and Retail / OTC Channel), and Geography (North America, and More). The Market and Forecasts are Provided in Terms of Value (USD).
Global Wound Care Management Devices Market Trends and Insights
Rising Incidence of Chronic & Diabetic Wounds
Diabetic foot ulcers now affect 15% of patients living with diabetes, driving hospitals to adopt multidisciplinary programs that pair advanced dressings with continuous glucose monitoring. Time-gated mid-infrared optoacoustic sensors enable depth-selective glucose readings, allowing clinicians to adjust therapy before complications arise. Early intervention strategies are shrinking hospitalization days and lowering amputation risks. Payers reward these outcomes with bundled payments that cover dressings, sensors, and telehealth follow-ups. Manufacturers are therefore integrating electronics into dressings to transmit moisture, pH, and temperature data, aligning device design with chronic-care protocols.
Escalating Global Surgical Volumes
Worldwide elective and trauma procedures rebounded in 2025, increasing demand for advanced closure strips, tissue sealants, and NPWT canisters. Mohs micrographic surgery trials on the scalp confirmed that pinch grafting reduces healing times versus second-intention protocols . As ambulatory surgical centers scale throughput, they deploy compact NPWT pumps that fit same-day discharge models. Ultrasound-guided debridement heads off infection risk, and real-time imaging helped cut readmission penalties at high-volume hospitals in the United States. These results encourage procurement teams to refresh closure portfolios despite budget pressures.
Limited Reimbursement in Emerging Markets
Many public insurers in Southeast Asia and Latin America still cover only basic gauze, delaying uptake of NPWT or bioengineered skin substitutes. Rural clinics often face supply-chain gaps that further limit access. Governments are piloting tiered benefit packages that reimburse advanced dressings for diabetic foot ulcers when primary dressings fail, but budget ceilings remain tight. Local assemblers that source polyurethane foams domestically and fill canisters onsite lower price barriers, yet clinician training lags. Public-private partnerships are beginning to bundle devices with outcome-based financing to bridge the affordability gap.
Other drivers and restraints analyzed in the detailed report include:
- Continuous Product & Material Innovations
- Shift Toward Home-Care & Single-Use NPWT Devices
- High Total Cost of Advanced Therapies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The wound care segment held 61.88% of 2025 revenue as clinicians favored antimicrobial foams, hydrofibers, and portable NPWT systems for complex cases. This dominance underscores how the wound care management devices market continues pivoting toward products that cut infection risk and support granulation. Wound closure items-including staples, adhesives, and absorbable barbed sutures-recorded a 5.62% CAGR outlook through 2031, buoyed by growing orthopedics and cardiovascular volumes. Traditional gauze retains relevance in low-acuity settings but yields share to dressings imbued with silver or PHMB for postoperative wounds.
Manufacturers integrating AI chips into dressings enable automatic moisture alerts and dosing of embedded antimicrobials, meeting hospital protocols for pressure-injury prevention. Meanwhile, topical biologics migrate from hospital pharmacies to outpatient infusion centers, expanding reach. The wound care management devices market is seeing combination products that pair a smart sensor layer with a hydrogel drug reservoir, supporting reimbursement under newly issued bundled CPT codes. Suppliers that align material science with digital monitoring gain bargaining power in tenders set by group purchasing organizations.
Chronic wounds controlled 57.92% of 2025 revenue, reflecting the resource intensity of diabetic foot ulcers, pressure injuries, and venous leg ulcers. These indications demand prolonged therapy, and payers approve high-end dressings when audits confirm reduced readmissions. Acute wounds, including trauma and post-operative incisions, are expanding at a 5.74% CAGR thanks to rising global surgery rates. Burn centers adopt enzymatic debriders paired with biosynthetic skin substitutes to reduce grafting needs.
Predictive algorithms embedded in electronic health records flag patients at ulcer risk, prompting early application of off-loading shoes and moisture-managing foams. Pressure-injury protocols now employ surface sensors that adjust mattress air cells to redistribute load. Diabetic ulcer management benefits from handheld imaging spectrometers that detect perfusion deficits, steering clinicians toward vascular interventions earlier in the care pathway. Such workflow changes reinforce premium product demand within the wound care management devices market.
Complete Report Scope:
- By Product
- Wound Care
- Dressings
- Traditional Gauze & Tape Dressings
- Advanced Dressings
- Wound-Care Devices
- Negative Pressure Wound Therapy (NPWT)
- Oxygen & Hyperbaric Systems
- Electrical Stimulation Devices
- Other Wound Care Devices
- Topical Agents
- Other Wound Care Products
- Dressings
- Wound Closure
- Sutures
- Surgical Staplers
- Tissue Adhesives, Strips, Sealants & Glues
- Wound Care
- By Wound Type
- Chronic Wounds
- Diabetic Foot Ulcer
- Pressure Ulcer
- Venous Leg Ulcer
- Other Chronic Wounds
- Acute Wounds
- Surgical/Traumatic Wounds
- Burns
- Other Acute Wounds
- Chronic Wounds
- By End User
- Hospitals & Specialty Wound Clinics
- Long-term Care Facilities
- Home-Healthcare Settings
- By Mode of Purchase
- Institutional Procurement
- Retail / OTC Channel
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America leads the wound care management devices market, generating 39.86% of the market revenue in 2025. As sophisticated insurance models fund high-end dressings, NPWT, and bioengineered tissues. In the United States, bundled payments under value-based contracts reward quicker closure and fewer complications, encouraging hospitals to trial next-generation hydrogels and sensor-enabled foams. The Food and Drug Administration exempts low-risk liquid bandages from 510(k) clearance, shortening launch times for consumer-oriented products. Canada's single-payer system invests in home-care NPWT pilots that cut outpatient clinic load by 18% in 2025. Mexico continues upgrading surgical facilities, opening bids for mid-priced closure strips and polyurethane films.
Europe remains a mature yet innovation-receptive arena. National health systems fund chronic wound bundles that cover sensor-enabled dressings when evidence shows shorter healing cycles. Germany's hospitals adopt AI-guided imaging to comply with new pressure-injury reporting mandates, stimulating device replacement. The United Kingdom rolls out community nurse-led diabetic foot programs supported by portable imaging tablets. Meanwhile, Southern Europe pursues cost-effective hydrogels that still meet EU Medical Device Regulation (MDR) documentation, creating niches for mid-range suppliers.
Asia-Pacific registers the fastest momentum for the wound care management devices market, registering a CAGR of 6.03% through 2031, fueled by healthcare infrastructure expansion and growing elective surgery capacity. China's centralized bulk-procurement schemes now include NPWT pumps, driving local manufacture of canisters and foam dressings to meet price caps. Japan prioritizes aging-in-place policies that reimburse home-care dressings and sensor patches, fostering innovation in ultra-thin silicone adhesives suited to fragile skin. India's state insurance programs begin covering advanced dressings for diabetic foot ulcers in tertiary centers, catalyzing distributor networks that penetrate tier-2 cities. Throughout Southeast Asia, private hospitals differentiate through specialty wound clinics equipped with tele-dermatology portals, widening regional market reach.
- Solventum
- Smiths Group
- Convatec
- Molnlycke Health Care
- Cardinal Health
- Coloplast
- Hartmann Group
- Medtronic
- B. Braun
- Integra LifeSciences
- Essity Medical
- Johnson & Johnson
- Baxter
- Organogenesis
- Kinetic Concepts
- Medela
- Medline Industries
- Lohmann & Rauscher
- Teleflex Medical
- Devon Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising incidence of chronic & diabetic wounds
- 4.2.2 Escalating global surgical volumes
- 4.2.3 Continuous product & material innovations
- 4.2.4 Shift toward home-care & single-use NPWT devices
- 4.2.5 AI-enabled wound imaging & decision support
- 4.2.6 Outcome-based reimbursement reforms
- 4.3 Market Restraints
- 4.3.1 Limited reimbursement in emerging markets
- 4.3.2 High total cost of advanced therapies
- 4.3.3 Environmental burden of single-use disposables
- 4.3.4 Shortage of skilled wound-care nurses
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porters Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Wound Care
- 5.1.1.1 Dressings
- 5.1.1.1.1 Traditional Gauze & Tape Dressings
- 5.1.1.1.2 Advanced Dressings
- 5.1.1.2 Wound-Care Devices
- 5.1.1.2.1 Negative Pressure Wound Therapy (NPWT)
- 5.1.1.2.2 Oxygen & Hyperbaric Systems
- 5.1.1.2.3 Electrical Stimulation Devices
- 5.1.1.2.4 Other Wound Care Devices
- 5.1.1.3 Topical Agents
- 5.1.1.4 Other Wound Care Products
- 5.1.1.1 Dressings
- 5.1.2 Wound Closure
- 5.1.2.1 Sutures
- 5.1.2.2 Surgical Staplers
- 5.1.2.3 Tissue Adhesives, Strips, Sealants & Glues
- 5.1.1 Wound Care
- 5.2 By Wound Type
- 5.2.1 Chronic Wounds
- 5.2.1.1 Diabetic Foot Ulcer
- 5.2.1.2 Pressure Ulcer
- 5.2.1.3 Venous Leg Ulcer
- 5.2.1.4 Other Chronic Wounds
- 5.2.2 Acute Wounds
- 5.2.2.1 Surgical/Traumatic Wounds
- 5.2.2.2 Burns
- 5.2.2.3 Other Acute Wounds
- 5.2.1 Chronic Wounds
- 5.3 By End User
- 5.3.1 Hospitals & Specialty Wound Clinics
- 5.3.2 Long-term Care Facilities
- 5.3.3 Home-Healthcare Settings
- 5.4 By Mode of Purchase
- 5.4.1 Institutional Procurement
- 5.4.2 Retail / OTC Channel
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Solventum
- 6.3.2 Smith & Nephew
- 6.3.3 ConvaTec Group
- 6.3.4 Molnlycke Health Care
- 6.3.5 Cardinal Health
- 6.3.6 Coloplast
- 6.3.7 Paul Hartmann AG
- 6.3.8 Medtronic
- 6.3.9 B. Braun SE
- 6.3.10 Integra LifeSciences
- 6.3.11 Essity Medical
- 6.3.12 Johnson & Johnson (Ethicon)
- 6.3.13 Baxter International
- 6.3.14 Organogenesis
- 6.3.15 Kinetic Concepts
- 6.3.16 Medela AG
- 6.3.17 Medline Industries
- 6.3.18 Lohmann & Rauscher
- 6.3.19 Teleflex Medical
- 6.3.20 Devon Medical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


