

|
시장보고서
상품코드
2122945
북미의 HVAC 장비 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America HVAC Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
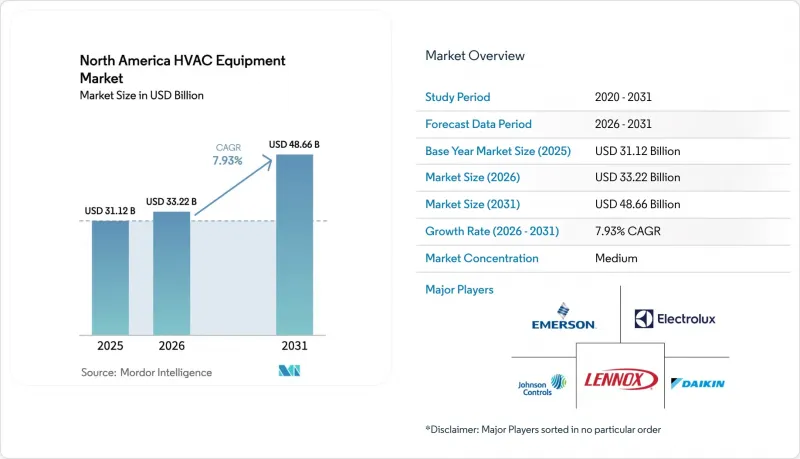
에 의하면, 북미의 HVAC 장비 시장 규모는 2025년 311억 2,000만 달러로 평가되었고, 2026년에는 332억 2,000만 달러로 추정되고, 2026-2031년 CAGR 7.93%로 성장을 지속할 전망이며, 2031년에는 486억 6,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 기기 유형별(난방 기기, 환기 기기, 공조 기기), 설치 형태별(신축, 개보수, 교체), 최종 사용자별(주거, 상업, 산업), 상업용 건물 유형별(사무실 건물, 의료시설 등), 그리고 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미의 HVAC 장비 시장 동향 및 인사이트
열펌프의 급속한 보급과 난방 전기화
대당 최대 2,000달러의 연방 세액 공제와 주 차원의 신규 천연가스 연결 금지 조치가 맞물리면서, 미국 역사상 처음으로 히트 펌프 출하 대수가 가스 보일러를 넘어섰습니다. -15°F에서도 최대 용량을 발휘할 수 있는 한랭지용 기종은 5,000 캐나다 달러(3,950 달러)에 달하는 유틸리티체의 리베이트에 힘입어 캐나다에서 점차 자리 잡고 있습니다. 가변 속도 압축기는 현재 계절 COP 3.5를 일상적으로 달성하고 있으며, 북동부 지역의 많은 시장에서 투자 회수 기간을 6년 미만으로 단축하고 있습니다. 지역 가스 사업자들이 전기화 인센티브로 무게중심을 옮기는 가운데, 히트 펌프와 백업용 저항 히터를 결합한 듀얼 연료 시스템이 개조 프로젝트에서 주목을 받고 있습니다. 이러한 구조적 변화로 인해 예측 기간 동안 북미 HVAC 장비 시장은 전기식 난방으로 비중이 이동할 것으로 예측됩니다.
저 GWP A2L 냉매의 도입 가속화가 장비 교체 붐을 일으키고 있습니다.
‘미국 혁신 및 제조법’에 따라 2024년까지 하이드로플루오로카본(HFC) 할당량이 40% 감축됨에 따라, R-410A 가격은 60% 상승하여, 각 OEM 업체들은 R-454B나 R-32 배합으로의 전환을 피할 수 없게 되었습니다. 개정된 ASHRAE 15 및 NFPA 1 규격에서는 누출 감지 기능의 통합과 환기 성능 향상이 의무화되어, 현장에서의 냉매 취급을 최소화하는 공장 사전 충전 기기의 도입이 촉진되고 있습니다. 건물 소유주들은 추가 할당량 감축에 앞서, 도입 후 10-12년이 경과한 시스템을 선제적으로 폐기하고 있으며, 이로 인해 광범위한 유통업체 네트워크를 보유한 브랜드에 유리한 장비 교체 흐름이 가속화되고 있습니다. 제품 수명 주기가 단축됨에 따라 애프터마켓 부품의 수익이 증가하여, 설계 플랫폼을 신속하게 전환할 수 있는 제조업체에 유리하게 작용합니다.
A2L 냉매로의 전환으로 인해 배상 책임 보험료 상승
2025년에는 보험사가 누출로 인한 화재 위험을 보험료에 반영한 결과, 도급업체의 보험료가 15-25% 상승했으며, 규정 준수 대응 강화로 인해 기계실 1실당 500-1,500달러의 추가 비용이 발생했습니다. 교육 및 감지 장비 도입 자금을 확보하지 못하는 소규모 설치 업체들은 시장에서 철수하고 있으며, 이로 인해 유통 경로가 통합되고 인건비가 상승하고 있습니다. 다세대 주택의 부동산 관리 회사는 보험사의 엄격한 심사에 직면해 있어, 기존 난방로를 대체하는 히트펌프 개조 공사의 승인이 지연되고 있습니다. 단기적으로는 배상 책임 비용의 급등으로 인해 가격에 민감한 주택 구매자층에서 A2L 시스템의 보급이 억제될 전망입니다.
부문 분석
2025년, 공조 기기는 북미 HVAC 장비 시장 전체의 46.43%를 차지했으며, 냉방 일수 증가와 R-410A 시스템의 폐지를 배경으로 연평균 성장률(CAGR) 8.64%로 확대되고 있습니다. 북미 HVAC 장비 시장에서 이 하위 부문의 매출액은 주거용 및 소규모 상업시설 모두에서 확고한 입지를 반영하고 있습니다. 덕트리스 미니 스플릿은 덕트 설치가 현실적으로 어려운 장소에서의 리모델링 수요를 흡수함으로써 두각을 나타내고 있는 반면, 가변 냉매 유량(VRF) 플랫폼은 광대한 상업시설에서 냉난방을 동시에 수행할 수 있게 해줍니다.
난방 기기로 분류되는 히트 펌프는 그 격차를 빠르게 좁혀가고 있습니다. 전기화 의무화 및 다양한 보조금 제도에 따라 가스식 난방로와의 설치 비용 차이가 줄어들고 있으며, 북미 HVAC 장비 시장에서의 점유율은 전기 구동형 솔루션으로 이동하고 있습니다. 에너지 회수형 환기 장치나 가습기 등의 환기 기기는 실내 공기질(IAQ) 규제 준수를 위한 흐름에 편승하고 있는 반면, 패키지형 터미널 유닛은 청구 처리의 간소화와 공간 절약으로 인해 공동 주택의 설계 사양에 다시 채택되고 있습니다.
2025년에는 북미 HVAC 장비 시장 점유율의 60.84%를 개보수 및 교체 설치가 차지한 것으로 평가되었으며, 냉매 규제 강화에 앞서 소유주들이 시스템 업데이트를 가속화하고 있어 계속해서 단기 매출을 견인하고 있습니다. 금융 프로모션 및 계절별 교체 캠페인을 통해 주택 소유자들은 한여름에 고액의 수리 비용이 드는 고장이 발생하기 전에 조기에 대응하도록 권장받고 있습니다. 한편, 신축 공사에 따른 북미 HVAC 장비 시장 규모는 멕시코의 산업 플랜트와 미국 선벨트 지역의 공동 주택 프로젝트에 힘입어 연평균 성장률(CAGR) 8.29%로 확대되고 있습니다.
건설업체들은 배선과 냉매 충전이 완전히 완료된 상태로 납품되는 프리패키지형 기계실을 사양으로 지정하는 사례가 늘어나고 있으며, 이를 통해 현장 작업 공수를 최대 50%까지 줄이고 있습니다. 전기화로 인해 가스 배관이 불필요해져 평면도가 단순화되지만, 한편으로는 배전반 업그레이드가 필요해져 세대당 2,000-4,000달러의 추가 비용이 발생합니다. 2031년까지는 개보수와 신축의 비율 차이가 소폭 축소되는 데 그칠 것이며, 전반적인 성장의 주요 원동력으로서 기기 교체에 따른 지출이 계속해서 중요한 역할을 할 것으로 보입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the North America HVAC equipment market size is expected to grow from USD 31.12 billion in 2025 to USD 33.22 billion in 2026 and is forecast to reach USD 48.66 billion by 2031 at 7.93% CAGR over 2026-2031.
This report is Segmented by Equipment Type (Heating Equipment, Ventilation Equipment, and Air-Conditioning Equipment), Installation Type (New Construction, Retrofit, and Replacement), End User (Residential, Commercial, and Industrial), Building Type for Commercial (Office Buildings, Healthcare Facilities, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
North America HVAC Equipment Market Trends and Insights
Rapid Adoption of Heat Pumps and Electrification of Heating
Federal tax credits of up to USD 2,000 per unit, combined with state bans on new natural-gas hookups, have propelled heat-pump shipments beyond gas furnaces for the first time in U.S. history. Cold-climate units capable of delivering full capacity at -15 °F, backed by CAD 5,000 (USD 3,950) in utility rebates, are taking hold in Canada. Variable-speed compressors now routinely achieve seasonal COPs of 3.5, reducing payback periods to fewer than 6 years in many Northeast markets. As regional gas utilities pivot toward electrification incentives, dual-fuel systems pairing heat pumps with backup resistance heaters are gaining traction in retrofit projects. This structural shift is expected to re-weight the North America HVAC equipment market toward electrically driven heating across the forecast horizon.
Accelerating Adoption of Low-GWP A2L Refrigerants Creating Replacement Wave
The American Innovation and Manufacturing Act triggered a 40% cut in hydrofluorocarbon quotas by 2024, lifting R-410A prices 60% and pushing OEMs to R-454B and R-32 formulations. Revised ASHRAE 15 and NFPA 1 codes now require integrated leak detection and enhanced ventilation, encouraging factory-charged equipment that minimizes field refrigerant handling. Building owners are pre-emptively retiring 10- to 12-year-old systems ahead of further quota cuts, accelerating a replacement wave that benefits brands with deep distributor networks. Shorter product life cycles increase aftermarket parts revenue and favor manufacturers able to quickly pivot design platforms.
Transition to A2L Refrigerants Increasing Liability Insurance Costs
Contractor insurance premiums rose 15-25% in 2025 as underwriters priced in leak-related fire risk, with compliance upgrades adding USD 500-1,500 per mechanical room. Smaller installers unable to fund training and detection equipment are exiting, consolidating channels, and raising labor costs. Multifamily property managers face insurer scrutiny, slowing approvals for heat-pump retrofits that would displace legacy furnaces. In the near term, elevated liability costs suppress penetration of A2L systems among price-sensitive residential buyers.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Smart and Connected HVAC Systems
- Stringent Energy-Efficiency Regulations and Incentives
- Supply-Chain Vulnerability Due to Critical Electronics and Sensor Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Air-conditioning equipment represented 46.43% of the overall North America HVAC equipment market share in 2025 and is scaling at an 8.64% CAGR, supported by rising cooling-degree days and the retirement of R-410A systems. The subsegment's revenue of the North America HVAC equipment market reflects its entrenched role in both residential and light-commercial buildings. Ductless mini-splits stand out by capturing retrofit demand where duct installation is impractical, while variable refrigerant flow platforms enable simultaneous heating and cooling across large commercial footprints.
Heat pumps, classified within heating equipment, are closing the gap fast. Electrification mandates and rebate stacks narrow the installed-cost delta versus gas furnaces, redirecting share within the North America HVAC equipment market toward electrically driven solutions. Ventilation gear such as energy-recovery ventilators and humidifiers rides the wave of IAQ compliance, while packaged terminal units return to multifamily design specs due to simplified billing and space savings.
Retrofit and replacement installations accounted for 60.84% of the North America HVAC equipment market share in 2025 and continue to drive near-term sales as owners accelerate system retirements ahead of tighter refrigerant caps. Financing promotions and seasonal replacement campaigns encourage homeowners to act before costly midsummer failures. Meanwhile, the North America HVAC equipment market size attached to new construction grows at an 8.29% CAGR, propelled by industrial plants in Mexico and multifamily projects across the U.S. Sunbelt.
Builders increasingly specify pre-packaged mechanical rooms that arrive fully wired and charged, trimming onsite labor by up to 50%. Electrification simplifies floor plans by eliminating gas piping but pushes panel upgrades that add USD 2,000-4,000 per dwelling. The balance between retrofit and new construction will narrow only modestly through 2031, keeping replacement spend a dominant thread in the overall growth story.
Complete Report Scope:
- By Equipment Type
- Heating Equipment
- Boilers and Furnaces
- Heat Pumps
- Unitary Heaters
- Ventilation Equipment
- Air Handling Units (AHUs)
- Air Filters
- Fan Coil Units
- Humidifiers and Dehumidifiers
- Air-Conditioning Equipment
- Unitary Air Conditioners
- Ducted Splits
- Ductless Mini-Splits
- Packaged Rooftops
- Variable Refrigerant Flow (VRF) Systems
- Room Air Conditioners
- Packaged Terminal Air Conditioners
- Chillers
- Unitary Air Conditioners
- Heating Equipment
- By Installation Type
- New Construction
- Retrofit / Replacement
- By End User
- Residential
- Commercial
- Industrial
- By Building Type (Commercial)
- Office Buildings
- Healthcare Facilities
- Hospitality and Leisure
- Retail Stores and Malls
- Educational Institutions
- Data Centers
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Carrier Global Corporation
- Daikin Industries Ltd.
- Johnson Controls International PLC
- Trane Technologies PLC
- Lennox International Inc.
- Rheem Manufacturing Company, Inc.
- Goodman Manufacturing Company, L.P.
- Nortek Global HVAC LLC
- Emerson Electric Co.
- Honeywell International Inc.
- LG Electronics Inc.
- Mitsubishi Electric Corporation
- Panasonic Corporation
- Bosch Thermotechnology Corp.
- Danfoss A/S
- Electrolux AB
- Uponor Corporation
- Gree Electric Appliances Inc.
- AAON Inc.
- Fujitsu General Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Residential and Non-residential Construction Activity
- 4.2.2 Stringent Energy-Efficiency Regulations and Incentives
- 4.2.3 Rapid Adoption of Heat Pumps and Electrification of Heating
- 4.2.4 Growing Demand for Smart and Connected HVAC Systems
- 4.2.5 Accelerating Adoption of Low-GWP A2L Refrigerants Creating Replacement Wave
- 4.2.6 Emergence of Prefabricated Modular HVAC Units for Quick Retrofits
- 4.3 Market Restraints
- 4.3.1 High Initial Capital Cost of High-Efficiency Systems
- 4.3.2 Skilled Labor Shortage for Installation and Maintenance
- 4.3.3 Supply-Chain Vulnerability Due to Critical Electronics and Sensor Shortages
- 4.3.4 Transition to A2L Refrigerants Increasing Liability Insurance Costs
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Key Performance Indicators
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Equipment Type
- 5.1.1 Heating Equipment
- 5.1.1.1 Boilers and Furnaces
- 5.1.1.2 Heat Pumps
- 5.1.1.3 Unitary Heaters
- 5.1.2 Ventilation Equipment
- 5.1.2.1 Air Handling Units (AHUs)
- 5.1.2.2 Air Filters
- 5.1.2.3 Fan Coil Units
- 5.1.2.4 Humidifiers and Dehumidifiers
- 5.1.3 Air-Conditioning Equipment
- 5.1.3.1 Unitary Air Conditioners
- 5.1.3.1.1 Ducted Splits
- 5.1.3.1.2 Ductless Mini-Splits
- 5.1.3.1.3 Packaged Rooftops
- 5.1.3.1.4 Variable Refrigerant Flow (VRF) Systems
- 5.1.3.2 Room Air Conditioners
- 5.1.3.3 Packaged Terminal Air Conditioners
- 5.1.3.4 Chillers
- 5.1.3.1 Unitary Air Conditioners
- 5.1.1 Heating Equipment
- 5.2 By Installation Type
- 5.2.1 New Construction
- 5.2.2 Retrofit / Replacement
- 5.3 By End User
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Industrial
- 5.4 By Building Type (Commercial)
- 5.4.1 Office Buildings
- 5.4.2 Healthcare Facilities
- 5.4.3 Hospitality and Leisure
- 5.4.4 Retail Stores and Malls
- 5.4.5 Educational Institutions
- 5.4.6 Data Centers
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Carrier Global Corporation
- 6.4.2 Daikin Industries Ltd.
- 6.4.3 Johnson Controls International PLC
- 6.4.4 Trane Technologies PLC
- 6.4.5 Lennox International Inc.
- 6.4.6 Rheem Manufacturing Company, Inc.
- 6.4.7 Goodman Manufacturing Company, L.P.
- 6.4.8 Nortek Global HVAC LLC
- 6.4.9 Emerson Electric Co.
- 6.4.10 Honeywell International Inc.
- 6.4.11 LG Electronics Inc.
- 6.4.12 Mitsubishi Electric Corporation
- 6.4.13 Panasonic Corporation
- 6.4.14 Bosch Thermotechnology Corp.
- 6.4.15 Danfoss A/S
- 6.4.16 Electrolux AB
- 6.4.17 Uponor Corporation
- 6.4.18 Gree Electric Appliances Inc.
- 6.4.19 AAON Inc.
- 6.4.20 Fujitsu General Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


