|
시장보고서
상품코드
2123150
미국의 화물 중개 시장 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)United States Freight Brokerage - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 미국 화물 중개 시장 규모는 2025년 196억 8,000만 달러에서 2026년에는 212억 8,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 7.23%로 성장을 지속하여, 2031년에는 301억 7,000만 달러에 이를 것으로 예측됩니다.
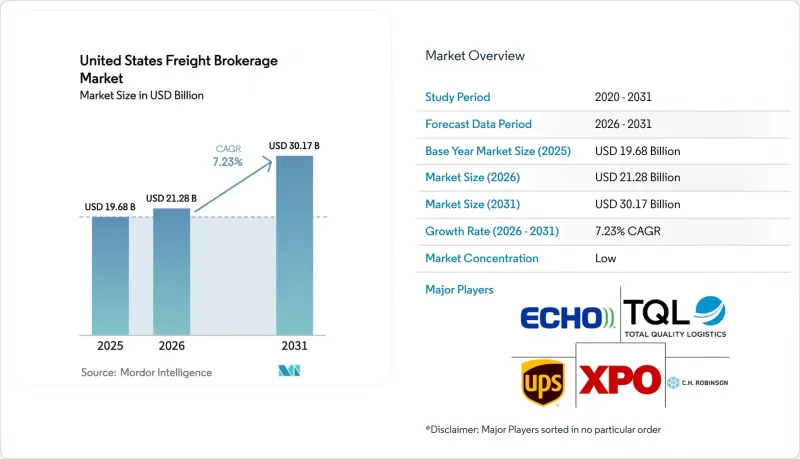
본 보고서는 서비스별(FTL 등), 장비 유형별(드라이 밴, 탱커 등), 운송 거리별(장거리, 지역 내, 단거리),비즈니스 모델별(기존 화물 중개 등), 최종 사용자 산업별(제조·자동차 등), 고객 규모별(소기업 등), 지역별(북동부 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
미국 화물 중개 시장 동향 및 인사이트
전자상거래 거래량의 급증과 익일 배송에 대한 기대
2024년, 미국의 전자상거래 매출액은 1조 1,000억 달러를 넘어섰으며, 현재 인구의 90%가 풀필먼트 센터에서 50마일 반경 내에 위치하고 있습니다. 이러한 고밀도 네트워크 덕분에 배송 시간이 1일 이내로 단축됨에 따라, 화주들은 지역별 운송업체를 통합하고 실시간으로 운송 능력을 보장할 수 있는 브로커를 이용해야 할 필요성이 대두되고 있습니다. 아마존은 라스트 마일 배송 스테이션을 1,000곳 추가 설치했으며, 브로커가 백홀 운송 능력과 매칭시키는 단거리 셔틀 서비스가 등장하고 있습니다. 월마트 등 기존 소매업체들은 라스트 마일 기술 도입을 가속화하여, 여러 구간에 걸쳐 시간 엄수가 요구되는 물류 흐름을 조정할 수 있는 중개업체에 대한 수요를 확대했습니다. 주문 주기는 주간 보충에서 일일 보충으로 전환되었으며, 전화에 의한 배차 대신 트럭의 위치 정보를 실시간으로 파악할 수 있는 데이터와 모바일 연동이 요구되게 되었습니다. 30초 이내에 운임 견적을 제시할 수 있는 플랫폼은 이러한 신속한 대응이 요구되는 환경에서 계속해서 입찰을 따내고 있습니다.
운송 사업자의 기반이 극도로 세분화되어 있다는 점이 브로커의 중요성을 높이고 있습니다.
미국에는 120만 개 이상의 활성 운송 사업자가 영업 중이며, 그중 97%는 20대 미만의 트럭을 보유한 소규모 사업자입니다. 이러한 소규모 사업자로 구성된 ‘롱테일’ 계층은 대량 화물 입찰에 필요한 재무 기반이나 백오피스 시스템을 갖추지 못하고 있으며, 그 결과 발생하는 정보의 비대칭성을 브로커는 화물 집약 및 신속한 지급 주기를 통해 수익화하고 있습니다. 2024년에는 소규모 운송업체의 운전기사 이직률이 90%를 넘어섰으며, 많은 개인 사업자는 연료비 선지급이나 즉시 지급을 중개업체에 의존하고 있습니다. 이러한 분산화를 통해 중개업체는 몇 시간 이내에 화물 경로를 변경할 수 있으므로, 화주는 단일 운송업체의 파산으로부터 보호받습니다. 또한, 운송업체의 빈번한 철수에도 불구하고 중개업체를 채무 불이행 위험으로부터 보호하고, 서비스 수준을 안정시키는 데에도 기여하고 있습니다.
현물 운임 변동이 중개업체의 이익률을 압박
2024년, 드라이밴(일반 화물용 컨테이너)의 현물 운임은 1마일당 1.45달러에서 2.10달러 사이에서 변동했습니다. 이는 45%의 변동 폭에 해당하며, 계약 가격 책정이 몇 달 늦어질 경우 중개업체의 마진은 급속히 잠식됩니다. 화주가 계약 기간 중 운임 재조정에 저항하는 가운데, 브로커는 손실을 흡수하거나 수익성이 없는 노선에서 철수할 수밖에 없습니다. 이는 C.H. 로빈슨이 2024년 2분기에 보고한 280 베이시스 포인트의 이익률 하락에서도 분명히 드러납니다. 에코 세계 로지스틱스는 매월 재견적을 실시하는 동적 가격 책정으로 대응하여 이익률 변동을 억제했으나, 한편으로는 조달 팀 입장에서는 예측이 어려워진다는 과제가 발생하고 있습니다. 자산을 많이 보유한 브로커는 자사 설비를 통해 변동을 완화할 수 있지만, 순수한 중개업체는 여전히 그 영향을 전적으로 받고 있습니다.
부문별 분석
2025년, 전체 트럭 적재(FTL)는 미국 화물 중개 시장의 63.63%를 차지하며, 대량 운송이 특징인 자동차 및 소매 화물 분야에서 그 우위를 반영하고 있습니다. 한편, 소매업체들이 재고 보유 비용을 절감하기 위해 화물을 소분하여 매일 소량 운송으로 전환하는 추세에 따라, 2026년부터 2031년까지 소량 트럭 운송(LTL)은 연평균 성장률(CAGR) 8.79%로 성장할 전망입니다. 각 중개업체가 멀티스톱(다중 정차지) 경로 설정 알고리즘을 도입하여 화주 간의 부분 화물을 통합해 나감에 따라, 미국 LTL 화물 중개 시장 규모는 꾸준히 확대될 것으로 예측됩니다. 페덱스 프레이트는 2024년 3분기 LTL 운송량이 12% 증가했으며, 수요가 세분화되는 상황에서 부두 일정을 효율적으로 조정할 수 있는 브로커가 유리하다는 점이 부각되고 있습니다. 한편, FTL 중개업체는 디지털 게시판을 활용해 귀로 화물을 매칭함으로써 빈 주행 거리를 줄이고 있습니다. 옐로우 코퍼레이션의 철수로 인해 전미 LTL 운송 능력의 12%가 상실되어 브로커들은 비싼 운임을 지불할 수밖에 없었지만, 그로 인해 발생한 서비스 공백을 기술에 정통한 중개업체들이 메우기 시작했습니다.
LTL의 성장은 재고를 소비자와 가까운 곳에 배치하는 지역 유통 전략에 의해서도 뒷받침되고 있습니다. FTL과 LTL을 결합한 하이브리드 집하 서비스를 제공하는 브로커는 거래 양측에서 추가적인 이익률을 확보하고 있습니다. 여러 거점을 경유하는 운송에서는 손해배상 청구 위험이 높기 때문에 자동화된 클레임 처리 체계와 충실한 화물 보험 정책을 갖춘 브로커가 경쟁 우위를 높이고 있습니다. FTL은 장거리 보충 운송에서 여전히 필수적이지만, 시장은 성숙 단계로 접어들고 있습니다. 반면, 전자상거래 주문 규모가 축소되는 가운데 LTL은 큰 성장 잠재력을 지니고 있습니다.
2025년 차량 관련 수익에서 드라이밴이 차지하는 비중은 44.57%였으나, 2026년부터 2031년까지 냉장 밴의 운송량은 연평균 성장률(CAGR) 9.89%를 기록하며 다른 모든 트레일러 유형을 능가하는 성장이 예상됩니다. 의약품 적정 유통 기준(GDP) 및 식료품 전자상거래의 성장에 따라 지속적인 온도 관리와 센서를 통한 모니터링이 요구되고 있으며, 이러한 서비스에는 20-30%의 운임 프리미엄이 적용되고 있습니다. 따라서 중개업자가 규정 준수 관련 추가 요금을 전가함에 따라, 미국의 냉장 화물 중개 시장 규모는 기초 운송량보다 빠른 속도로 확대되고 있습니다. 플랫베드 및 스텝 데크 차량의 경우, 1,100억 달러 규모의 도로·교량 정비 프로그램을 통해 자금이 지원되는 인프라 프로젝트로부터 안정적인 수요가 발생하고 있습니다. 탱크 트레일러는 화학 물질 및 벌크 액체 운송이라는 틈새 시장을 유지하고 있지만, EPA(미국 환경보호청)의 감독이 강화되면서 중개업자의 진입이 제한되고 있습니다.
드라이 밴(일반 화물용)의 이용률은 2024년에 92%까지 하락했습니다. 이는 공급 능력이 수요를 초과하여 이익률을 압박했기 때문입니다. 대조적으로, 냉장 트레일러의 차량 수는 수요가 연평균 6-8% 증가하는 반면, 연평균 2%에 그치는 성장세에 그쳐 공급이 부족합니다. 온도 추적 텔레매틱스에 투자하는 중개업체는 타사와의 차별화를 꾀할 수 있으며, 특히 고부가가치 의약품 운송 노선에서 화물의 품질 저하 위험을 경감시킬 수 있습니다. 특수 트레일러(자동차 운반차, 가축 운반차, 공압식 탱크차 등)는 규모는 작지만 수익성이 높은 분야로, 운송업체와의 견고한 관계를 통해 안정적인 수익을 기대할 수 있습니다.
기타 혜택:
- Excel 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the United States freight brokerage market size is expected to grow from USD 19.68 billion in 2025 to USD 21.28 billion in 2026 and is forecast to reach USD 30.17 billion by 2031 at 7.23% CAGR over 2026-2031.
This report is Segmented by Service (FTL and More), Equipment Type (Dry Van, Tanker, and More), Haul Length (Long-Haul, Regional, and Local), Business Model (Traditional Freight Brokerage and More), End-User Industry (Manufacturing & Automotive and More), Customer Size (Small Businesses and More), and Geography (Northeast and More). The Market Forecasts are Provided in Terms of Value (USD).
United States Freight Brokerage Market Trends and Insights
E-Commerce Volume Surge and Next-Day Delivery Expectations
United States e-commerce sales exceeded USD 1.1 trillion in 2024, and fulfillment centers now sit within 50 miles of 90% of the population. These dense networks compress delivery windows to a single day, prompting shippers to engage brokers that aggregate regional carriers and can guarantee capacity in real time. Amazon added 1,000 last-mile delivery stations, spawning short shuttle runs that brokers match against backhaul capacity. Traditional retailers such as Walmart accelerated last-mile technology adoption, broadening demand for brokers able to orchestrate multi-leg, time-sensitive flows. Order cycles have shifted from weekly to daily replenishment, requiring live truck-location data and mobile integrations rather than phone-based dispatch. Platforms delivering rate quotes in under 30 seconds continue to win bids in this fast-turn environment.
Highly Fragmented Carrier Base Increases Broker Relevance
More than 1.2 million active motor carriers operate in the United States, and 97% run fleets smaller than 20 trucks. The long tail of micro-fleets lacks the balance sheets and back-office systems to bid on enterprise freight, creating an information asymmetry that brokers monetize through load aggregation and faster payment cycles. Driver turnover at small carriers exceeded 90% in 2024, and many owner-operators rely on brokers for fuel advances and same-day pay. This fragmentation protects shippers from single-carrier failure because brokers can reroute cargo within hours. It also shields brokers from default risk and stabilizes service levels despite frequent carrier exits.
Spot-Rate Volatility Compresses Brokerage Margins
Dry-van spot rates fluctuated between USD 1.45 and USD 2.10 per mile during 2024, a 45% swing that quickly erodes broker margins when contract pricing lags by several months. As shippers resist mid-cycle rate resets, brokers either absorb losses or exit unprofitable lanes, as evidenced by a 280-basis-point margin decline reported by C.H. Robinson in Q2 2024. Echo Global Logistics responded with dynamic pricing that re-quotes monthly, lowering margin volatility but creating forecasting challenges for procurement teams. Asset-heavy brokers can cushion swings with their own equipment, but pure intermediaries remain fully exposed.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Digitization of TMS And API Integrations
- Shipper Demand for Carbon-Optimized Routing
- Driver Shortage and Capacity Unpredictability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Full-Truckload occupied 63.63% of the United States freight brokerage market in 2025, reflecting its primacy in high-volume automotive and retail shipments. Yet Less-than-Truckload is set to grow at an 8.79% CAGR between 2026-2031 as retailers split loads into smaller, daily shipments to cut inventory carrying costs. The United States freight brokerage market size for LTL is projected to expand steadily as brokers integrate multi-stop routing algorithms and consolidate partial loads across shippers. FedEx Freight recorded 12% LTL volume growth in Q3 2024, highlighting how fragmented demand favors brokers who can orchestrate dock schedules efficiently. FTL brokers, meanwhile, rely on digital boards to match backhauls and curb empty miles. Yellow Corporation's exit removed 12% of national LTL capacity, pushing brokers to pay premium rates but also opening a service gap that tech-savvy intermediaries have begun to fill.
LTL growth is also propelled by regional distribution strategies that position stock closer to consumers. Brokers offering hybrid FTL-LTL consolidation services capture incremental margin on both sides of the transaction. Damage-claim risk is higher on multi-stop moves, so brokers with automated claims handling and enhanced cargo insurance policies gain competitive traction. FTL remains indispensable for long-haul replenishment but is maturing, whereas LTL offers outsized upside as e-commerce order sizes shrink.
Dry Van accounted for 44.57% of 2025 equipment revenue, but Refrigerated Van tonnage is projected to outpace all other trailer types at a 9.89% CAGR between 2026-2031. Pharmaceutical Good Distribution Practice rules and grocery e-commerce growth require continuous temperature control and sensor-based monitoring, services that command 20-30% rate premiums. The United States freight brokerage market size for reefer freight is therefore rising faster than underlying volume as brokers pass through compliance-related surcharges. Flatbed and step-deck equipment enjoy steady demand from infrastructure projects funded under the USD 110 billion roads-and-bridges program. Tanker trailers retain a niche around chemicals and bulk liquids but face stricter EPA oversight, limiting brokerage participation.
Dry Van utilization slipped to 92% in 2024 as capacity outstripped demand, suppressing margins. Conversely, the reefer fleet grew only 2% annually versus 6-8% demand, tightening supply. Brokers that invest in temperature-tracking telematics differentiate themselves and can mitigate spoilage risk, especially in high-value pharmaceutical lanes. Specialized trailers - car carriers, livestock haulers, pneumatic tanks - remain small but profitable sectors where deep carrier relationships provide defensible earnings.
Complete Report Scope:
- By Service
- Full-Truckload (FTL)
- Less-than-Truckload (LTL)
- Others
- By Equipment / Trailer Type
- Dry Van
- Refrigerated Van
- Flatbed / Step-Deck
- Tanker (Bulk Liquid and Chemical)
- Others
- By Haul Length
- Long-Haul (More than 500 miles)
- Regional (100-500 miles)
- Local (Lesser than 100 miles)
- By Business Model
- Traditional Freight Brokerage
- Asset-Based Freight Brokerage
- Agent Model Freight Brokerage
- Digital Freight Brokerage
- By End-User Industry
- Manufacturing and Automotive
- Construction and Infrastructure Projects
- Oil, Gas, Mining and Chemicals
- Agriculture and Food / Beverage
- Retail, FMCG and Wholesale Distribution
- Healthcare and Pharmaceuticals
- E-commerce and 3PL Fulfilment
- Other End-User Industry
- By Customer Size
- Large Enterprise Shippers (Greater than USD 100 M)
- Mid-Market Shippers (USD 10-100 M)
- Small Businesses (Lesser than USD 10 M)
- By Geography
- Northeast
- Midwest
- Southeast
- Southwest
- West
List of Companies Covered in this Report:
- Allen Lund Company
- ArcBest Corporation
- Arrive Logistics
- BlueGrace Logistics
- BNSF Logistics
- C.H. Robinson
- Convoy Inc.
- Echo Global Logistics
- GlobalTranz (WWEX)
- Hub Group
- J.B. Hunt Transportation
- Landstar System, Inc.
- Mode Global
- Nolan Transportation Group
- Red Technologies
- Redwood Logistics
- Schneider FreightPlus
- SunteckTTS
- Total Quality Logistics (TQL)
- Trinity Logistics
- Uber Freight
- United Parcel Service of America, Inc. (UPS)
- Worldwide Express
- XPO, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-Commerce Volume Surge and Next-Day Delivery Expectations
- 4.2.2 Highly Fragmented Carrier Base Boosts Broker Relevance
- 4.2.3 Rapid Digitisation of TMS / API Integrations
- 4.2.4 Shipper Demand for Carbon-Footprint-Optimised Routing
- 4.2.5 PE-Backed Shipper Consolidation Outsourcing to Brokers
- 4.2.6 Nearshoring and US-Mexico Cross-Border Expansion
- 4.3 Market Restraints
- 4.3.1 Spot-Rate Volatility Compressing Brokerage Margins
- 4.3.2 Driver Shortage and Capacity Unpredictability
- 4.3.3 Compliance Costs from AB5, Speed-Limiter Proposals
- 4.3.4 Shipper Direct Contracting via Digital Load Boards
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts
- 5.1 By Service
- 5.1.1 Full-Truckload (FTL)
- 5.1.2 Less-than-Truckload (LTL)
- 5.1.3 Others
- 5.2 By Equipment / Trailer Type
- 5.2.1 Dry Van
- 5.2.2 Refrigerated Van
- 5.2.3 Flatbed / Step-Deck
- 5.2.4 Tanker (Bulk Liquid and Chemical)
- 5.2.5 Others
- 5.3 By Haul Length
- 5.3.1 Long-Haul (More than 500 miles)
- 5.3.2 Regional (100-500 miles)
- 5.3.3 Local (Lesser than 100 miles)
- 5.4 By Business Model
- 5.4.1 Traditional Freight Brokerage
- 5.4.2 Asset-Based Freight Brokerage
- 5.4.3 Agent Model Freight Brokerage
- 5.4.4 Digital Freight Brokerage
- 5.5 By End-User Industry
- 5.5.1 Manufacturing and Automotive
- 5.5.2 Construction and Infrastructure Projects
- 5.5.3 Oil, Gas, Mining and Chemicals
- 5.5.4 Agriculture and Food / Beverage
- 5.5.5 Retail, FMCG and Wholesale Distribution
- 5.5.6 Healthcare and Pharmaceuticals
- 5.5.7 E-commerce and 3PL Fulfilment
- 5.5.8 Other End-User Industry
- 5.6 By Customer Size
- 5.6.1 Large Enterprise Shippers (Greater than USD 100 M)
- 5.6.2 Mid-Market Shippers (USD 10-100 M)
- 5.6.3 Small Businesses (Lesser than USD 10 M)
- 5.7 By Geography
- 5.7.1 Northeast
- 5.7.2 Midwest
- 5.7.3 Southeast
- 5.7.4 Southwest
- 5.7.5 West
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Allen Lund Company
- 6.4.2 ArcBest Corporation
- 6.4.3 Arrive Logistics
- 6.4.4 BlueGrace Logistics
- 6.4.5 BNSF Logistics
- 6.4.6 C.H. Robinson
- 6.4.7 Convoy Inc.
- 6.4.8 Echo Global Logistics
- 6.4.9 GlobalTranz (WWEX)
- 6.4.10 Hub Group
- 6.4.11 J.B. Hunt Transportation
- 6.4.12 Landstar System, Inc.
- 6.4.13 Mode Global
- 6.4.14 Nolan Transportation Group
- 6.4.15 Red Technologies
- 6.4.16 Redwood Logistics
- 6.4.17 Schneider FreightPlus
- 6.4.18 SunteckTTS
- 6.4.19 Total Quality Logistics (TQL)
- 6.4.20 Trinity Logistics
- 6.4.21 Uber Freight
- 6.4.22 United Parcel Service of America, Inc. (UPS)
- 6.4.23 Worldwide Express
- 6.4.24 XPO, Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment