|
시장보고서
상품코드
2123320
크라운 캡 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Crown Caps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
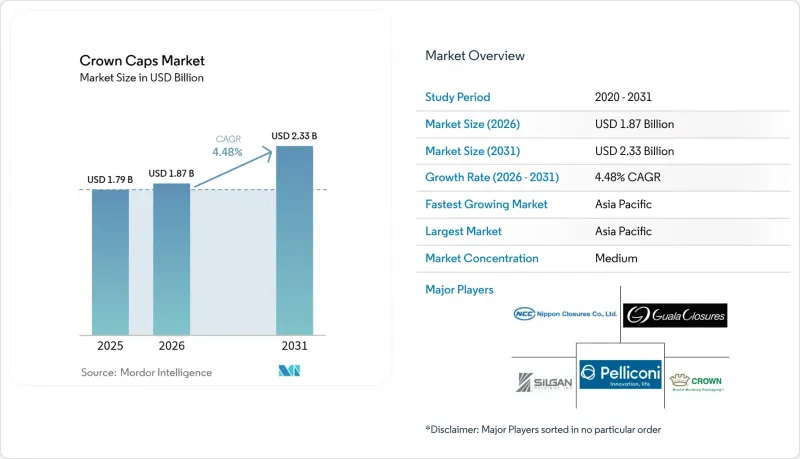
에 의하면, 크라운 캡 시장 규모는 2025년 17억 9,000만 달러에서 2026년에는 18억 7,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 4.48%로 성장을 지속하여, 2031년까지 23억 3,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 소재(알루미늄, 강철, 주석 도금 강철), 캡 유형(프라이오프식, 트위스트오프식), 라이너 유형(PVC, PVC 프리), 용도(음료, 식품, 의약품·영양보조식품 등), 지역(북미, 남미, 유럽 등)별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계 크라운 캡 시장 동향 및 인사이트
크래프트 맥주 및 소규모 양조장의 확대
2024년에는 미국에서 9,000개 이상의 양조장이 가동 중이며, 이는 2023년 대비 15% 증가한 수치입니다. 이들 양조장의 거의 모든 곳이 소량 생산 시에도 이산화탄소를 확실하게 밀봉할 수 있기 때문에 플라이오프 방식의 금속 크라운 캡을 채택하고 있습니다. 독일, 벨기에, 영국의 유럽 마이크로 양조장에서도 유사한 추세가 나타나고 있으며, 이에 따라 각 컨버터 업체들은 고유한 풍미 프로파일을 유지할 수 있는 맞춤형 인쇄 크라운 캡 개발을 추진하고 있습니다. 탭룸에서 소매점으로의 유통이 확대됨에 따라, 마이크로 양조장에서는 산소 투과율이 더 낮고 위조 방지 기능이 확실한 라이너를 요구하고 있습니다. 또한, 이 부문의 고가 제품군에서는 지속가능성 노력을 강조하고 매장 내 어필력을 높이기 위해 경량 알루미늄의 채택이 정당화되고 있습니다.
규제에 힘입은 PVC 프리 라이너로의 전환
세계 식품 접촉 재료에 관한 법규로 인해 PVC에서 EPE 및 TPE 라이너로의 전환이 가속화되고 있습니다. FDA의 지속적인 가소제 재평가와 유럽연합(EU)의 ‘포장 및 포장 폐기물 규정(PPWR)’에 따라 음료 브랜드들은 재활용 가능하고 비염소계 솔루션으로의 단계적 전환을 요구받고 있습니다. 이러한 전환에는 생산 라인 개조, 수지 검증 및 원자재 비용 증가가 수반되지만, 조기에 도입한 기업들은 규제를 준수하는 친환경 캡을 통해 프리미엄 포지셔닝을 확보하고 있습니다. 예측 기간 동안 규제 당국의 단속이 강화되고 브랜드 소유자의 수명 주기 감사가 확대됨에 따라, PVC가 포함되지 않은 생산 능력을 확대하는 공급업체들이 시장 점유율을 높일 것으로 예측됩니다.
경량 PET 병과 플라스틱 스크류 캡
병 제조업체들은 현재 동등한 유리 용기에 비해 무게가 60-70% 가벼운 PET 포장을 제공하고 있으며, EU의 ‘일회용 플라스틱 지침’을 충족하는 테더가 부착된 나사식 캡을 적용하고 있습니다. 이로 인해 기존에는 금속 크라운 캡이 주류를 이루던 비용 중심 시장이 점차 잠식되고 있습니다. PET를 통한 물류 비용 절감과 차단성 수지의 개선은 특히 운송비가 밸류체인의 상당 부분을 차지하는 신흥 경제국에서 탄산음료의 틈새 시장에 대한 위협을 점점 더 강화하고 있습니다. 크라운 캡 공급업체들은 PET로는 재현하기 어려운 전통적인 미관, 재활용성, 그리고 프리미엄 포지셔닝을 강조함으로써 대체 위험을 완화하고 있습니다.
부문 분석
2025년, 스틸 크라운 캡은 저렴한 비용과 고속 생산 라인에서의 견고함 덕분에 48.40%의 시장 점유율을 유지했습니다. 스틸 크라운 캡 시장 규모는 소폭 확대되겠지만, 시장 점유율의 일부는 알루미늄에 양보하게 될 것입니다. 알루미늄은 5.56%의 경량화 목표와 뛰어난 내식성 덕분에 연평균 성장률(CAGR)을 주도하고 있습니다. 알루미늄의 재활용성과 고급스러운 외관은 원자재 비용 차이를 상쇄하는 가격 프리미엄을 확립한 수제 증류주 제조업체들로부터 지지를 받고 있습니다. 각 공급업체들은 캡의 강성을 저해하지 않으면서 쉘의 질량을 최대 20%까지 줄일 수 있는 3104 및 5052 합금에 대한 시험을 진행하고 있습니다.
주석 도금 강철과 같은 2차 소재는 광택 마감이나 높은 차단 성능이 요구되는 틈새 시장을 대상으로 하지만, 원자재 가격 변동에 따라 가격 민감도가 높은 문제에 직면해 있습니다. 비용과 매장 내 어필력의 균형을 맞추기 위해, 스틸 재질의 내부 쉘과 알루미늄 재질의 스커트를 조합한 하이브리드 설계가 등장하고 있습니다. 예측 기간 동안 소재의 진화는 대형 음료 그룹의 ‘크래들 투 크래들(C2C)’ 감사에 좌우될 가능성이 있으며, 사용 후 제품의 스크랩 회수율이 중요한 차별화 요소가 될 것입니다.
2025년에는 트위스트 오프 방식의 캡이 61.75%의 점유율을 차지하며, 주류 맥주 시장에서 확고히 자리 잡은 사용 현황을 반영하고 있습니다. 그러나 고령화가 진행됨에 따라 개봉 편의성이 중요시되고, 프리미엄 무알코올 브랜드가 여러 번에 걸친 소비 상황에 대응하기 위해 재밀봉 기능을 채택하고 있는 점으로 미루어 볼 때, 트위스트오프식 캡은 연평균 성장률(CAGR) 5.89%로 더 높은 성장세를 보일 것으로 전망됩니다. 크라운 캡 시장에서는 반복적으로 열고 닫아도 밀봉 압력을 유지하는 나사 형성 기술이 채택되고 있습니다. 정밀 금형 세트 및 비전 검사에 대한 투자로 인해 단위 비용은 상승하지만, 각 컨버터 업체들은 제품 차별화 및 부가가치 요금을 통해 그 비용을 회수하고 있습니다.
비틀어 여는 기능과 육안으로 확인할 수 있는 위변조 방지 밴드를 결합한 하이브리드 형식은 의약품 분야의 규제 당국의 엄격한 심사에 대응하기 위한 것입니다. 또한, 아세안(ASEAN) 지역의 양조장에서는 링 풀 방식의 파생 제품이 시범 도입되고 있으며, 편의성을 새로운 성장 동력으로 삼고 있습니다. 이 분야에서 성공을 거둘 공급업체는 장시간의 가동 중단을 초래하지 않으면서, 프라이오프 방식과 트위스트오프 방식의 SKU 간을 신속하게 전환할 수 있는 금형의 유연성을 통합하게 될 것입니다.
지역별 분석
아시아태평양은 2025년에 40.10%의 점유율로 1위를 차지하며 연평균 성장률(CAGR) 7.05%로 성장을 지속하고, 있어, 크라운 캡 시장에서 가장 크고 성장 속도가 가장 빠른 지역이 되었습니다. 중국, 인도, 인도네시아, 베트남의 가처분 소득 증가가 1인당 맥주 및 청량음료 소비량을 끌어올리고 있는 한편, 양조장 건설을 위한 외국인 직접 투자가 캡 수요를 뒷받침하고 있습니다. 각 지역의 가공업체들은 병입 시설 인근에 캡 본체의 프레스 가공과 라이너의 복합 가공을 집약함으로써 공급망의 회복력을 확보하고, 운송 비용과 통관 위험을 최소화하고 있습니다. 중국 동부 각 성의 정부 장려책은 알루미늄 캡 제조를 더욱 촉진하고 수출 경쟁력을 높이고 있습니다.
북미는 9,000개가 넘는 양조장과 뿌리 깊은 수제 맥주 문화에 힘입어 견고한 입지를 유지하고 있습니다. PVC가 포함되지 않은 라이너 사용을 의무화하는 규제로 인해 조기 도입이 진행되고 있으며, 시행 기한에 앞서 규제 준수 제품의 생산 규모를 확대한 국내 공급업체들이 혜택을 보고 있습니다. 2022년에 캐나다에서 40억 8,000만 달러 상당의 알루미늄이 수입된 사실은 캡 생산을 뒷받침하는 지역의 통합된 금속 시장을 입증하고 있습니다.
유럽에서는 고급 음료와 엄격한 재활용 목표에 힘입어 수요가 안정적입니다. 보증금 반환 제도의 도입으로 분리 가능한 캡의 폐기물에 대한 관심이 높아지면서, 충전 업체들은 끈이 달린 또는 재밀봉 가능한 크라운 캡으로의 전환을 요구받고 있습니다. 제조업체들은 전통적인 디자인의 특징을 해치지 않으면서도 사용 후 제품을 회수할 수 있도록 쉘의 형태를 미세 조정하여 대응하고 있습니다. 한편, 독일과 벨기에의 양조장에서는 소비자 편의성을 높이기 위해 링 풀 방식의 시제품 개발이 진행되고 있습니다.
남미, 중동 및 아프리카는 새로운 성장의 축이 되고 있습니다. 브라질에서는 확립된 맥주 시장이 캡의 꾸준한 소비를 뒷받침하고 있는 반면, 멕시코에서는 테킬라 수출이 맞춤형 위조 방지 기능이 탑재된 크라운 캡에 대한 수요를 견인하고 있습니다. 아프리카에서는 도시화가 진행됨에 따라 병에 담긴 탄산음료의 보급이 가속화되고 있지만, 가격에 대한 민감성으로 인해 PET 병과의 경쟁이 격화되고 있습니다. 프레스 가공 라인을 현지화하거나 지역 음료 그룹과 제휴하는 제조업체들은 수입 관세를 절감하고 리드 타임을 단축함으로써 장기적인 시장 침투를 위한 기반을 다지고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the crown caps market size is expected to grow from USD 1.79 billion in 2025 to USD 1.87 billion in 2026 and is forecast to reach USD 2.33 billion by 2031 at 4.48% CAGR over 2026-2031.
This report is Segmented by Material (Aluminum, Steel, and Tin-Plated Steel), Closure Type (Pry-Off, and Twist-Off), Liner Type (PVC, and PVC-Free), Application (Beverages, Food, Pharmaceuticals and Nutraceuticals, and More), and Geography (North America, South America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Crown Caps Market Trends and Insights
Rising Craft-Beer Micro-Brewery Expansion
More than 9,000 breweries operated in the United States in 2024, up 15% from 2023, and nearly all specify pry-off metal crowns because they seal carbonation reliably at small batch scales. European microbreweries in Germany, Belgium, and the United Kingdom mirror this momentum, prompting converters to develop custom-printed crowns that preserve unique flavor profiles. As taproom-to-retail distribution widens, microbrewers demand liners with tighter oxygen transmission rates and overt tamper evidence. The segment's premium-priced offerings also justify the adoption of lightweight aluminum to reinforce sustainability claims and shelf impact.
Regulation-Driven Shift Toward PVC-Free Liners
Global food-contact legislation is accelerating the migration from PVC to EPE or TPE liners. The FDA's ongoing reassessment of plasticizers and the European Union's Packaging and Packaging Waste Regulation (PPWR) push beverage brands to phase in recyclable, non-chlorinated solutions. The transition entails production line retrofits, resin validation, and higher raw material outlays, yet early adopters secure premium positioning with compliant, eco-friendly closures. Over the forecast period, suppliers that scale PVC-free capacity are expected to gain share as regulators heighten enforcement and brand owners expand life-cycle auditing.
Lightweight PET Bottles with Plastic Screw Caps
Bottle manufacturers now deliver PET packs that weigh 60-70% less than comparable glass containers and integrate tethered screw caps that satisfy the EU Single-Use Plastics Directive, eroding cost-conscious segments traditionally served by metal crowns. PET's logistics savings and improved barrier resins increasingly threaten the carbonated soft drink niche, especially in emerging economies where freight expenses dominate value chains. Crown cap suppliers mitigate the substitution risk by emphasizing heritage aesthetics, recyclability, and premium positioning that PET struggles to replicate.
Other drivers and restraints analyzed in the detailed report include:
- Resurgence of Glass Packaging in Premium Beverages
- Interactive QR-Coded Crown Caps Boost Brand Engagement
- Volatility in Tin-Plate and Aluminum Pricing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Steel retained 48.40% share of the crown caps market in 2025 due to its low cost and robustness on high-speed lines. The crown caps market size attributed to steel will edge higher but cede mix to aluminum, whose 5.56% brand lightweighting targets and superior corrosion resistance fuel CAGR. Aluminum recyclability and premium aesthetics appeal to craft distillers that command price premiums covering the material differential. Suppliers experiment with 3104 and 5052 alloys that lower shell mass by up to 20% without compromising cap rigidity.
Second-tier materials such as tin-plated steel serve niche segments requiring glossy finishes or elevated barrier performance but face price sensitivity amid raw-material volatility. Hybrid designs that marry a steel inner shell with an aluminum skirt are emerging to balance cost with shelf appeal. Over the forecast horizon, material evolution may hinge on cradle-to-cradle audits by major beverage groups, making post-consumer scrap recovery rates a critical differentiator.
Pry-off variants commanded 61.75% share in 2025, reflecting entrenched use in mainstream beer markets. Yet twist-offs are projected to outpace at 5.89% CAGR as aging demographics value easy opening and as premium non-alcoholic brands adopt resealability to support multi-serve consumption occasions. The crown caps market embraces thread-forming technologies that maintain seal pressure across repeated openings and closings. Investment in precision die sets and vision inspection drives unit costs higher, but converters recoup through product differentiation and value-added fees.
Hybrid formats combining twistability with overt tamper bands seek to satisfy regulatory scrutiny in pharmaceuticals. Additionally, the ring-pull derivatives pilot in ASEAN breweries, positioning convenience as an alternative growth lever. Suppliers successful in this segment will integrate tooling flexibility that permits rapid changeovers between pry-off and twist-off SKUs without protracted downtime.
Complete Report Scope:
- By Material
- Aluminum
- Steel
- Tin-Plated Steel
- By Closure Type
- Pry-Off
- Twist-Off
- By Liner Type
- PVC
- PVC-Free (EPE / TPE)
- By Application
- Beverages
- Alcoholic Beverages
- Beer
- Wine
- Spirits
- Non-Alcoholic Beverages
- Carbonated Soft Drinks
- Functional and Energy Drinks
- Other Non-Alcoholic Beverages
- Alcoholic Beverages
- Food
- Pharmaceuticals and Nutraceuticals
- Other Applications
- Beverages
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Vietnam
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific led with a 40.10% share in 2025, and its 7.05% CAGR makes it the largest and fastest geography within the crown caps market. Rising disposable incomes in China, India, Indonesia, and Vietnam lift per-capita beer and soft-drink consumption, while foreign direct investment into brewery build-outs underpins closure volumes. Regional converters secure supply-chain resilience by co-locating shell stamping and liner compounding near bottling hubs, minimizing freight costs and customs exposure. Government incentives in China's eastern provinces further encourage aluminum cap manufacturing, bolstering export competitiveness.
North America retains a robust position, fueled by over 9,000 breweries and a strong craft-beer culture. Regulations pushing PVC-free liners prompt early adoption, rewarding domestic suppliers that scale compliant wads ahead of enforcement deadlines. Aluminum import volumes worth USD 4.08 billion from Canada in 2022 underscore the integrated regional metals market supporting closure production.
Europe shows stable demand, anchored by premium beverages and stringent recycling targets. Implementation of deposit-return systems sharpens focus on detachable closure waste, nudging fillers toward tethered or resealable crowns. Producers respond with shell geometry tweaks that allow post-consumer collection without compromising heritage design cues. Meanwhile, breweries in Germany and Belgium pilot ring-pull formats to enhance consumer convenience.
South America and the Middle East and Africa present emerging growth corridors. Brazil's established beer scene underpins steady closure consumption, whereas Mexico's tequila exports drive demand for customized, tamper-evident crowns. In Africa, urbanization accelerates bottled soda uptake, though price sensitivity fosters competition from PET. Manufacturers that localize stamping lines or partner with regional beverage groups reduce import duties and shorten lead times, building a platform for long-term penetration.
- Crown Holdings Inc.
- Pelliconi & C. SpA
- Nippon Closures Co., Ltd.
- Silgan Holdings Inc.
- Guala Closures Group S.p.A.
- Astir Vitogiannis Bros SA
- Finn-Korkki Oy
- Samhwa Crown & Closure Co., Ltd.
- A.M.D. Industries Limited
- Avon Crowncaps & Containers Nigeria Ltd.
- Viscose Closures Ltd.
- Closure Systems International Inc.
- Berlin Packaging LLC
- O.Berk Company LLC
- Tapi S.p.A.
- Evergreen Resources Ltd.
- Yantai Closures Co., Ltd.
- Standard Crown Caps (India) Pvt Ltd.
- SKS Bottle & Packaging Inc.
- Toyo Seikan Group Holdings, Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising craft-beer micro-brewery expansion
- 4.2.2 Regulation-driven shift toward PVC-free liners
- 4.2.3 Resurgence of glass packaging in premium beverages
- 4.2.4 Interactive QR-coded crown caps boost brand engagement
- 4.2.5 Emerging demand from kombucha and functional drinks
- 4.2.6 Advanced tamper-evident cap designs
- 4.3 Market Restraints
- 4.3.1 Lightweight PET bottles with plastic screw caps
- 4.3.2 Volatility in tin-plate and aluminum pricing
- 4.3.3 Policy push against single-use metal closures
- 4.3.4 Penetration of ring-pull crowns in ASEAN breweries
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Aluminum
- 5.1.2 Steel
- 5.1.3 Tin-Plated Steel
- 5.2 By Closure Type
- 5.2.1 Pry-Off
- 5.2.2 Twist-Off
- 5.3 By Liner Type
- 5.3.1 PVC
- 5.3.2 PVC-Free (EPE / TPE)
- 5.4 By Application
- 5.4.1 Beverages
- 5.4.1.1 Alcoholic Beverages
- 5.4.1.1.1 Beer
- 5.4.1.1.2 Wine
- 5.4.1.1.3 Spirits
- 5.4.1.2 Non-Alcoholic Beverages
- 5.4.1.2.1 Carbonated Soft Drinks
- 5.4.1.2.2 Functional and Energy Drinks
- 5.4.1.2.3 Other Non-Alcoholic Beverages
- 5.4.1.1 Alcoholic Beverages
- 5.4.2 Food
- 5.4.3 Pharmaceuticals and Nutraceuticals
- 5.4.4 Other Applications
- 5.4.1 Beverages
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Vietnam
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Crown Holdings Inc.
- 6.4.2 Pelliconi & C. SpA
- 6.4.3 Nippon Closures Co., Ltd.
- 6.4.4 Silgan Holdings Inc.
- 6.4.5 Guala Closures Group S.p.A.
- 6.4.6 Astir Vitogiannis Bros SA
- 6.4.7 Finn-Korkki Oy
- 6.4.8 Samhwa Crown & Closure Co., Ltd.
- 6.4.9 A.M.D. Industries Limited
- 6.4.10 Avon Crowncaps & Containers Nigeria Ltd.
- 6.4.11 Viscose Closures Ltd.
- 6.4.12 Closure Systems International Inc.
- 6.4.13 Berlin Packaging LLC
- 6.4.14 O.Berk Company LLC
- 6.4.15 Tapi S.p.A.
- 6.4.16 Evergreen Resources Ltd.
- 6.4.17 Yantai Closures Co., Ltd.
- 6.4.18 Standard Crown Caps (India) Pvt Ltd.
- 6.4.19 SKS Bottle & Packaging Inc.
- 6.4.20 Toyo Seikan Group Holdings, Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment