|
시장보고서
상품코드
2124689
중동 및 북아프리카의 핀테크 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)MENA Fintech - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
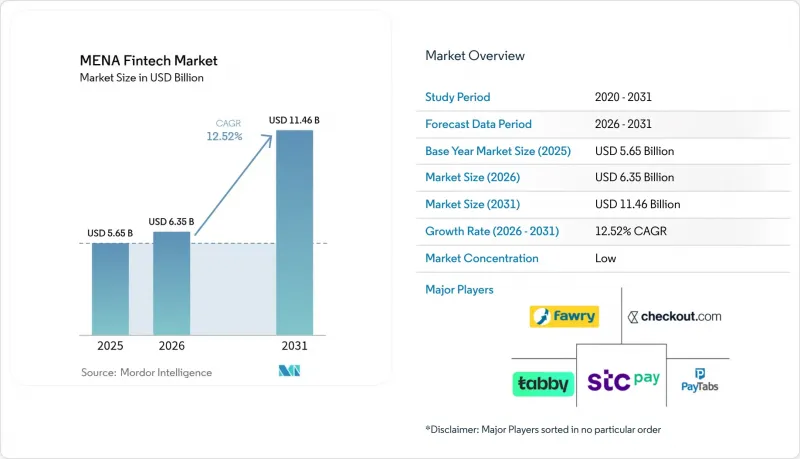
에 의하면, 2026년 중동 및 북아프리카 핀테크 시장 규모는 63억 5,000만 달러로 추정되고, 2025년 56억 5,000만 달러에서 확대해, 2031년에는 114억 6,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 12.52%로 성장할 것으로 전망됩니다.
본 보고서는 서비스 유형별(디지털 결제, 디지털 대출·자금 조달, 디지털 투자, 인슈어테크, 네오뱅킹), 최종 사용자별(개인, 기업), 사용자 인터페이스별(모바일 앱, 웹/브라우저, POS/IoT 기기), 지역별(GCC, 북아프리카, 레반트)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
중동 및 북아프리카의 핀테크 시장 동향 및 인사이트
정부의 ‘무현금화’ 및 ‘금융 포용’ 정책이 핀테크 수요를 가속화
사우디아라비아는 2030년까지 무현금 거래 비율을 70%로 높이는 것을 목표로 하고 있으며, 이집트는 2025년까지 성인의 50%가 은행 계좌를 보유하도록 하는 것을 목표로 하고 있습니다. 또한, UAE는 2024년에 라이선스 발급 절차를 간소화했습니다. 이러한 목표는 핀테크 도입의 명확한 지표가 되며, 민간 기업 시장 진입 장벽을 낮춥니다. 요르단의 샌드박스 제도는 규제 리스크를 한층 더 완화하여, 스타트업이 과도한 규정 준수 비용을 부담하지 않고도 사업을 확장할 수 있도록 지원하고 있습니다. 정부가 급여 및 복지 급여 지급을 디지털화함에 따라 소비자들의 전자 지갑에 대한 친숙도가 높아지고, 고객 확보 비용이 감소하고 있습니다. 또한 이러한 정책 추진으로 소매업체들이 비접촉식 결제를 도입하도록 유도하는 인센티브가 생겨나면서 결제 네트워크가 확대되고 있습니다. 이러한 정책들이 시너지를 발휘해 선순환을 만들어내며, 중동 및 북아프리카의 핀테크 시장을 확대시키고 있습니다.
모바일 및 인터넷 보급률의 급증으로 ‘모바일 우선’ 금융 접근이 가능해졌습니다.
GCC 국가에서는 스마트폰 보급률이 80%를 넘어, 모바일이 은행 거래의 기본 채널로 자리 잡았습니다. UAE에서는 이미 디지털 지갑을 통한 POS 지출 비중이 18%에 달하며, 2027년까지 33%에 이를 전망입니다. 이집트와 모로코에서는 통신사 기반의 에이전트 모델을 통해 서비스 범위를 확대하고 있으며, 지점 인프라를 거치지 않아 운영 비용을 절감하고 있습니다. Z세대 사용자는 디지털 지갑을 통한 지역 내 전자상거래 지출의 23%를 차지하며, 지속적인 결제 습관을 확립하고 있습니다. 북아프리카 농촌 지역의 4G/5G 커버리지 확대로 인해 원격 KYC(신원 확인)를 통한 계좌 개설이 가능해지면서 새로운 고객층 개척이 진행되고 있습니다. 이처럼 ‘모바일 퍼스트’ 모델은 모든 소비자층에서 급속한 점유율 확대를 주도하고 있습니다.
관할 구역별 규제의 불일치가 규정 준수 부담을 가중시키고 있다.
19가지의 서로 다른 라이선스 제도로 인해 핀테크 기업은 시장별로 별도의 법인을 설립해야 하며, 통일된 체계에 비해 간접비가 15-25% 증가하고 있습니다. 자본 규제 및 데이터 현지화 관련 규정의 불일치가 패스포트 제도의 활용을 방해하여, 지역적 사업 확장을 지연시키고 있습니다. 대형 기존 기업들은 이러한 비용을 흡수할 수 있지만, 스타트업 기업들은 자원 부족에 직면하여 혁신의 다양성이 제한되고 있습니다. 상호 인정의 부재 또한 국경을 초월한 오픈 API 연동을 방해하여 통합의 ‘데드존’을 만들어내고 있습니다. 투자자들은 이러한 리스크를 기업 가치에 반영하며, 다국적 진출을 위한 회피책으로서 업계 재편을 뒷받침하고 있습니다.
부문 분석
2025년, 중동 및 북아프리카 핀테크 시장 점유율의 54.12%를 디지털 결제가 차지했습니다. 이는 거의 보편화된 스마트폰 지갑과 가맹점 유치를 위한 적극적인 인센티브에 힘입은 결과입니다. 이 하위 부문에서는 QR 코드나 토큰화된 지갑을 통한 결제와 같은 새로운 결제 수단이 추가되어 사용자 충성도도 더욱 높아졌습니다. 디지털 대출은 규모는 작지만, 실시간 얼터너티브 데이터를 활용한 신용 평가 시스템을 강점으로 삼아 연평균 성장률(CAGR) 17.74%로 성장하고 있습니다. 2025년 Fawry가 10억 이집트 파운드의 대출 실행액을 급증시킨 것은 결제에서 신용으로의 인접성을 보여줍니다.
로보자문와 인슈어테크는 API 퍼스트 유통 모델을 통해 확대되고 있는 반면, STC Bank와 같은 네오뱅크는 지갑의 사용자 기반을 풀서비스 계좌로 전환하고 있습니다. 규제 샌드박스를 통해 파라메트릭형이나 이용 실적을 기반으로 한 보험 상품이 허용되면서 실험적인 시도가 촉진되고 있습니다. 결제 브랜드가 동일한 앱 내에 신용, 투자, 보험 탭을 추가함으로써 교차 판매의 시너지 효과가 발생하고, 사용자의 평생 가치(LTV)가 확대되고 있습니다. 이러한 다각화 추진은 중동 및 북아프리카 핀테크 시장 전반에서 플랫폼 융합이 가속화되고 있음을 시사합니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, MENA fintech market size in 2026 is estimated at USD 6.35 billion, growing from 2025 value of USD 5.65 billion with 2031 projections showing USD 11.46 billion, growing at 12.52% CAGR over 2026-2031.
This report is Segmented by Service Proposition (Digital Payments, Digital Lending & Financing, Digital Investments, Insurtech, Neobanking), End-User (Retail, Businesses), User Interface (Mobile Applications, Web/Browser, POS/IoT Devices), and Geography (GCC, North Africa, Levant). The Market Forecasts are Provided in Terms of Value (USD).
MENA Fintech Market Trends and Insights
Government Cash-Lite & Financial-Inclusion Mandates Accelerate Fintech Demand
Saudi Arabia targets 70% cashless transactions by 2030, Egypt aims to bank 50% of adults by 2025, and the UAE streamlined licensing in 2024. These targets provide clear metrics for adoption and reduce go-to-market friction for private players. Sandboxes in Jordan further cut regulatory risk, helping startups scale without prohibitive compliance spend. As governments digitize payroll and welfare transfers, consumer familiarity with e-wallets rises, lowering acquisition costs. The policy push also incentivizes retailers to deploy contactless acceptance, enlarging acceptance networks. Collectively, mandates create a virtuous circle that widens the MENA fintech market.
Mobile & Internet Penetration Surge Enables Mobile-First Financial Access
Smartphone penetration tops 80% in GCC states, turning mobiles into the default banking channel. The UAE already sees digital wallets covering 18% of POS spend, on track for 33% by 2027. Egypt and Morocco extend reach through telco-based agent models, bypassing branch infrastructure and shrinking operating costs. Gen Z users account for 23% of regional e-commerce spend via digital wallets, establishing lasting payment habits. Growing 4G/5G coverage in rural North Africa enables remote KYC onboarding, unlocking new customer pools. The mobile-first model thus propels rapid share gains across consumer cohorts.
Regulatory Fragmentation Across Jurisdictions Increases Compliance Burden
Nineteen different licensing regimes require fintechs to form market-specific entities, adding 15-25% to overheads versus unified frameworks. Disparate capital and data-localization rules hinder passporting and delay regional scaling. Larger incumbents absorb the cost but startups face resource strain, limiting innovation diversity. Lack of mutual recognition also hampers cross-border open-API linkage, creating integration dead-zones. Investors price the risk into valuations, nudging consolidation as a workaround for multi-country reach.
Other drivers and restraints analyzed in the detailed report include:
- VC Funding & Sandbox Momentum Fuel Startup Formation
- CBDC Pilots Enabling Cross-Border Rails Create Common API Infrastructure
- Cash-Centric Habits Inflate Customer-Acquisition Costs in North Africa
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Digital payments controlled 54.12% of MENA fintech market share in 2025, underpinned by near-ubiquitous smartphone wallets and aggressive merchant-acquiring incentives. The sub-segment added new rails such as QR and tokenized wallet checkout, further cementing stickiness. Digital lending, though smaller, is growing at an 17.74% CAGR on the strength of real-time alternative-data scoring. Fawry's EGP 1 billion disbursement surge in 2025 illustrates payments-to-credit adjacency.
Robo-advisory and insurtech expand via API-first distribution, while neobanks like STC Bank convert wallet bases into full-service accounts. Regulatory sandboxes allow parametric and usage-based policies, fostering experimentation. Cross-sell synergies emerge as payments brands add credit, investment, and insurance tabs within the same app, stretching user lifetime value. The diversification push points to escalating platform convergence across the MENA fintech market.
Complete Report Scope:
- By Service Proposition
- Digital Payments
- Digital Lending & Financing
- Digital Investments
- Insurtech
- Neobanking
- By End-User
- Retail
- Businesses
- By User Interface
- Mobile Applications
- Web / Browser
- POS / IoT Devices
- By Geography
- GCC
- Saudi Arabia
- United Arab Emirates
- Qatar
- Bahrain
- Kuwait
- Oman
- North Africa
- Egypt
- Morocco
- Algeria
- Tunisia
- Levant
- Jordan
- Lebanon
- GCC
List of Companies Covered in this Report:
- Fawry
- PayTabs
- Checkout.com
- Tabby
- Tamara
- STC Pay
- Paymob
- MNT-Halan
- Geidea
- Network International
- BenefitPay
- Careem Pay
- Lean Technologies
- HyperPay
- YAP
- Telda
- NymCard
- Sarwa
- OPay
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Govt cash-lite and financial-inclusion mandates
- 4.2.2 Mobile & internet penetration surge
- 4.2.3 VC funding & sandbox momentum
- 4.2.4 CBDC pilots enabling cross-border rails
- 4.2.5 Embedded-finance demand from e-commerce and gig platforms
- 4.2.6 Instant-payment rails unlocking alternative lending data
- 4.3 Market Restraints
- 4.3.1 Regulatory fragmentation across jurisdictions
- 4.3.2 Cash-centric habits inflating CAC in North Africa
- 4.3.3 Scarcity of Arabic AI/ML risk-scoring datasets
- 4.3.4 Legacy core-bank IT bottlenecks
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Service Proposition
- 5.1.1 Digital Payments
- 5.1.2 Digital Lending & Financing
- 5.1.3 Digital Investments
- 5.1.4 Insurtech
- 5.1.5 Neobanking
- 5.2 By End-User
- 5.2.1 Retail
- 5.2.2 Businesses
- 5.3 By User Interface
- 5.3.1 Mobile Applications
- 5.3.2 Web / Browser
- 5.3.3 POS / IoT Devices
- 5.4 By Geography
- 5.4.1 GCC
- 5.4.1.1 Saudi Arabia
- 5.4.1.2 United Arab Emirates
- 5.4.1.3 Qatar
- 5.4.1.4 Bahrain
- 5.4.1.5 Kuwait
- 5.4.1.6 Oman
- 5.4.2 North Africa
- 5.4.2.1 Egypt
- 5.4.2.2 Morocco
- 5.4.2.3 Algeria
- 5.4.2.4 Tunisia
- 5.4.3 Levant
- 5.4.3.1 Jordan
- 5.4.3.2 Lebanon
- 5.4.1 GCC
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.4.1 Fawry
- 6.4.2 PayTabs
- 6.4.3 Checkout.com
- 6.4.4 Tabby
- 6.4.5 Tamara
- 6.4.6 STC Pay
- 6.4.7 Paymob
- 6.4.8 MNT-Halan
- 6.4.9 Geidea
- 6.4.10 Network International
- 6.4.11 BenefitPay
- 6.4.12 Careem Pay
- 6.4.13 Lean Technologies
- 6.4.14 HyperPay
- 6.4.15 YAP
- 6.4.16 Telda
- 6.4.17 NymCard
- 6.4.18 Sarwa
- 6.4.19 OPay
7 Market Opportunities & Future Outlook
- 7.1 Cross-border GCC-North Africa remittance corridors via tokenized wallets
- 7.2 Green Islamic fintech products aligned with ESG & Sharia mandates