|
시장보고서
상품코드
2124691
북미의 핀테크 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America Fintech - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
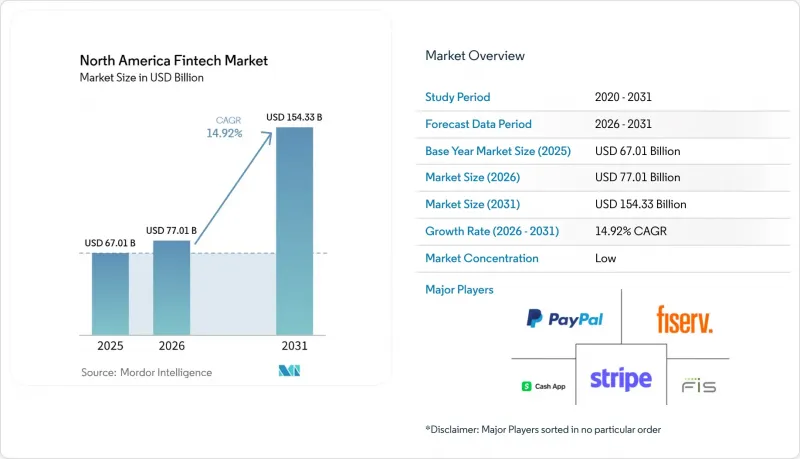
에 의하면, 북미의 핀테크 시장 규모는 2025년에 670억 1,000만 달러로 평가되었고, 2026년에 770억 1,000만 달러로 추정되고, 2031년까지 1,543억 3,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 14.92%로 성장할 전망입니다.
본 보고서는 서비스 분야별(디지털 결제, 디지털 대출·자금 조달, 디지털 투자, 인슈어테크, 네오뱅킹), 최종 사용자별(개인, 기업), 사용자 인터페이스별(모바일 앱, 웹/브라우저, POS/IoT 기기), 지역별(캐나다, 미국, 멕시코)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미의 핀테크 시장 동향 및 인사이트
P2P 및 카드 연동형 디지털 지갑의 우위
Apple Pay, PayPal, Cash App 등의 카드 연동형 지갑은 2024년에 총 1조 7,000억 달러 이상의 거래액을 처리하며, 확립된 카드 네트워크 내에 머무름으로써 얻는 규모의 우위를 보여주고 있습니다. 소비자들은 계속해서 기존 신용 한도를 유지할 수 있는 지갑을 선호하고 있으며, Venmo의 분기 거래액은 10% 증가한 756억 달러에 달하고, P2P 생태계의 높은 정착도를 입증하고 있습니다. FedNow의 ‘Request to Pay’ 기능은 부가가치 메시징 및 청구서 발행 서비스를 결합한 지갑 제공업체에게 새로운 수익원을 개척할 것으로 기대됩니다. 한편, 2025년 1월 시행될 CFPB 규정에 따라 연간 거래 건수가 5,000만 건을 초과하는 비은행계 결제 앱은 연방 정부의 직접 검사 대상이 되며, 소규모 신규 진출기업에게는 고정비 부담이 커지게 됩니다.
중소기업의 통합형 POS/ISV 제품군 도입
소규모 가맹점들은 주문, 로열티, 급여 계산, 대출을 통합한 소프트웨어 내장형 결제 서비스에 주목하고 있습니다. Toast사는 2024년 매출의 87%를 라이선스 수수료가 아닌 결제, 하드웨어 및 부수적인 금융 서비스에서 창출하며, 번들형 서비스의 수익 창출 능력을 보여주었습니다. 지역 은행들은 가맹점의 자금 관리 관계를 잃는 것이 저비용 핵심 예금을 위협한다는 점을 인식하고 있으며, 시장 점유율을 지키기 위해 일부 은행은 POS 핀테크 제품의 화이트 라벨화를 시작하고 있습니다. 시장 분석가들은 임베디드 금융의 수익 규모가 2024년 1,850억 달러에서 2028년에는 2,280억 달러로 확대될 것으로 예측하고 있으며, 이는 수직 통합형 업체에 유리한 북미 핀테크 시장의 성장 궤적을 시사합니다.
CFPB 및 주 정부의 규정 준수 비용 증가
현재 CFPB의 직접 감독 대상은 약 7개의 주요 비은행 결제 제공업체에 이르고 있으며, 검사 범위는 데이터 개인정보 보호, 부정 사용에 따른 환불 시기, 그리고 계좌 해지까지 확대되었습니다. 2024년에는 캘리포니아주 및 뉴욕주 규제 당국이 핀테크 관련 집행 조치의 37%를 발동하여, 3,000만 달러의 소비자 환급금을 징수했습니다. 2025년 4월 CFPB의 메모에서는 연방 정부의 일제 단속이 줄어들 것으로 시사되고 있지만, 비은행 등록 규정에 따라 모든 합의 명령을 공표해야 할 의무가 부과됨에 따라 규정 위반으로 인한 평판 리스크가 높아지고 있습니다.
부문별 분석
2025년, 디지털 결제는 북미 핀테크 시장 점유율의 47.86%를 차지했으며, 부문 매출은 약 321억 달러에 달했습니다. 카드 자금을 활용한 디지털 지갑은 기존 카드 네트워크 인프라를 활용함으로써 즉각적인 규모 확대와 가맹점에서의 수용을 실현하고 있습니다. PayPal 단독으로 총 결제 처리액 1조 7,000억 달러를 처리한 반면, Cash App의 월간 활성 사용자 수는 5,500만 명을 넘어섰습니다. AI를 활용한 신용 심사 모델로 승인 시간이 10초 미만으로 단축됨에 따라 디지털 렌딩이 입지를 다졌으며, 수수료를 면제하는 디지털 투자 포털은 자산 잔고를 확대했습니다.
네오뱅킹은 현재 규모는 작지만 연평균 성장률(CAGR) 21.95%로 급성장할 것으로 예상되며, 2031년까지 북미 핀테크 시장의 5분의 1 이상을 차지할 가능성이 있습니다. Chime의 800만 건이 넘는 계좌 수는 저비용의 바이럴 성장 모델을 여실히 보여주고 있습니다. 이 회사의 고객 확보 비용은 평균 20달러인 반면, 전통적인 은행에서는 925달러에 육박합니다. 텔레매틱스와 행동 데이터를 활용하는 인슈어테크 스타트업은 자동차 보험 및 주택 보험의 손해율을 낮추고 있습니다. 모든 서비스 제안에서 기존 기업들은 금융, 보험, 자산 운용 모듈을 소비자의 지갑에 직접 통합하여, 서비스 전환 장벽을 높이지 않으면서도 사용자 1인당 평균 수익을 확대되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the North America fintech market size is projected to be USD 67.01 billion in 2025, USD 77.01 billion in 2026, and reach USD 154.33 billion by 2031, growing at a CAGR of 14.92% from 2026 to 2031.
This report is Segmented by Service Proposition (Digital Payments, Digital Lending & Financing, Digital Investments, Insurtech, Neobanking), End-User (Retail, Businesses), User Interface (Mobile Applications, Web/Browser, POS/IoT Devices), and Geography (Canada, United States, Mexico). The Market Forecasts are Provided in Terms of Value (USD).
North America Fintech Market Trends and Insights
P2P and Card-Funded Digital-Wallet Dominance
Card-backed wallets such as Apple Pay, PayPal, and Cash App processed more than USD 1.7 trillion in combined volume during 2024, illustrating the scale advantage gained by remaining inside established card networks. Consumers continue to prefer wallets that keep existing credit lines intact, and Venmo's quarterly throughput climbed 10% to USD 75.6 billion, reinforcing the stickiness of P2P ecosystems. FedNow's request-to-pay functionality is expected to open complementary revenue streams for wallet providers that overlay value-added messaging and invoice services. At the same time, a January 2025 CFPB rule brings nonbank payment apps handling more than 50 million annual transactions under direct federal examination, raising the fixed-cost bar for smaller entrants.
SME Uptake of Integrated POS/ISV Suites
Small merchants are turning to software-embedded payments that consolidate ordering, loyalty, payroll, and lending. Toast derived 87% of its 2024 top line from payments, hardware, and ancillary financial services rather than license fees, revealing the monetization power of bundled offerings. Community banks acknowledge that losing the merchant cash-management relationship threatens low-cost core deposits, and several have begun white-labeling point-of-sale fintech products to defend share. Market observers expect the embedded-finance revenue pool to grow from USD 185 billion in 2024 to USD 228 billion in 2028, implying a North America fintech market expansion path that rewards vertically integrated players.
Intensifying CFPB and State Compliance Costs
Direct CFPB supervision now applies to about seven large nonbank payment providers, expanding examination scope to data privacy, fraud-refund timing, and account closures. California and New York regulators initiated 37% of fintech enforcement actions in 2024, collecting USD 30 million in consumer restitution. Although an April 2025 CFPB memo signals fewer federal sweeps, the requirement to publicly file all settlement orders under the nonbank registry rule raises reputational stakes for compliance lapses.
Other drivers and restraints analyzed in the detailed report include:
- Bank-Fintech BaaS/API Partnerships
- AI-Based Fraud-Orchestration Savings
- Rising Cyber-Insurance Premiums Post-Ransomware
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Digital payments controlled 47.86% of the North America fintech market share in 2025, translating to roughly USD 32.1 billion in segment revenue. Card-funded wallets ride the installed card-network rails, providing instant scale and merchant acceptance. PayPal alone processed USD 1.7 trillion in total payment volume, while Cash App's monthly active users surpassed 55 million. Digital lending gained ground as AI underwriting models cut approval times to under 10 seconds, and digital investment portals grew assets by waiving commissions.
Neobanking, although smaller today, is forecast to race ahead at a 21.95% CAGR and could command more than one-fifth of the North America fintech market by 2031. Chime's eight-million-plus account base illustrates the low-cost viral growth economics; its customer acquisition cost averages USD 20, versus nearly USD 925 for traditional banks. Insurtech startups using telematics and behavioral data are shaving loss ratios for auto and home policies. Across propositions, incumbents are embedding financing, insurance, and wealth modules directly inside consumer wallets, expanding average revenue per user without raising switching friction.
Complete Report Scope:
- By Service Proposition
- Digital Payments
- Digital Lending & Financing
- Digital Investments
- Insurtech
- Neobanking
- By End-User
- Retail
- Businesses
- By User Interface
- Mobile Applications
- Web / Browser
- POS / IoT Devices
- By Geography
- Canada
- United States
- Mexico
List of Companies Covered in this Report:
- PayPal
- Stripe
- Block (Square)
- Fiserv
- FIS
- Intuit
- Visa
- Mastercard
- Chime
- SoFi
- LendingClub
- Juspay Technologies (Hyperswitch)
- Brex
- Coinbase
- Robinhood
- Plaid
- Avant
- Upstart
- OnDeck
- Lemonade
- Root
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 P2P & card-funded digital-wallet dominance
- 4.2.2 SME uptake of integrated POS/ISV fintech suites
- 4.2.3 Bank-fintech BaaS/API partnerships
- 4.2.4 FedNow & Real-Time Rail monetization layers
- 4.2.5 AI-based fraud-orchestration cost reductions
- 4.2.6 Tokenized deposits & program-mable money pilots
- 4.3 Market Restraints
- 4.3.1 Intensifying CFPB & state compliance costs
- 4.3.2 Rising cyber-insurance premiums post-ransomware
- 4.3.3 Cloud-compute price inflation squeezing unit-economics
- 4.3.4 Talent gap in GenAI & zero-trust security stacks
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Service Proposition
- 5.1.1 Digital Payments
- 5.1.2 Digital Lending & Financing
- 5.1.3 Digital Investments
- 5.1.4 Insurtech
- 5.1.5 Neobanking
- 5.2 By End-User
- 5.2.1 Retail
- 5.2.2 Businesses
- 5.3 By User Interface
- 5.3.1 Mobile Applications
- 5.3.2 Web / Browser
- 5.3.3 POS / IoT Devices
- 5.4 By Geography
- 5.4.1 Canada
- 5.4.2 United States
- 5.4.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 PayPal
- 6.4.2 Stripe
- 6.4.3 Block (Square)
- 6.4.4 Fiserv
- 6.4.5 FIS
- 6.4.6 Intuit
- 6.4.7 Visa
- 6.4.8 Mastercard
- 6.4.9 Chime
- 6.4.10 SoFi
- 6.4.11 LendingClub
- 6.4.12 Juspay Technologies (Hyperswitch)
- 6.4.13 Brex
- 6.4.14 Coinbase
- 6.4.15 Robinhood
- 6.4.16 Plaid
- 6.4.17 Avant
- 6.4.18 Upstart
- 6.4.19 OnDeck
- 6.4.20 Lemonade
- 6.4.21 Root
7 Market Opportunities & Future Outlook
- 7.1 Cross-Border B2B Payment Orchestration for Mid-Market Exporters
- 7.2 GenAI-Driven Hyper-Personalized Wealth-Management Micro-Pods