|
시장보고서
상품코드
2124692
베트남의 핀테크 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Vietnam Fintech - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 베트남의 핀테크 시장 규모는 2026년에 43억 3,000만 달러로 추정되고, CAGR 15.37%로 성장을 지속할 전망이며, 2031년에는 88억 5,000만 달러에 이를 것으로 예측됩니다.
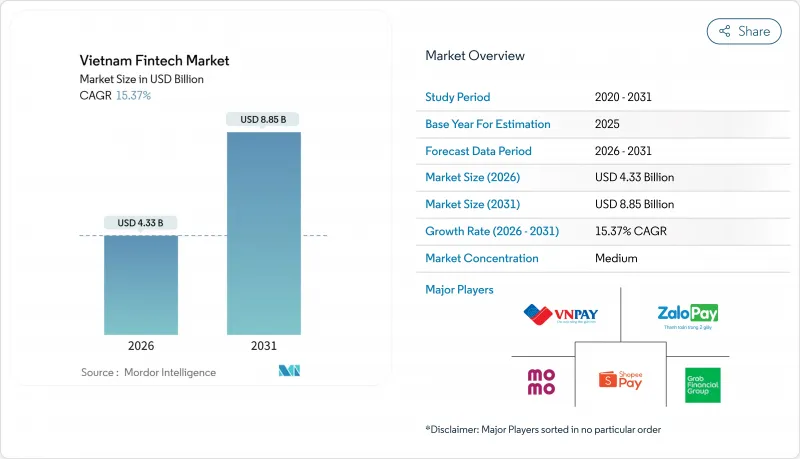
본 보고서는 서비스 분야별(디지털 결제, 디지털 대출·자금 조달, 디지털 투자, 인슈어테크, 네오뱅킹), 최종 사용자별(개인, 기업), 사용자 인터페이스별(모바일 앱, 웹/브라우저, POS/IoT 기기), 지역별(베트남 북부, 중부, 남부)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
베트남의 핀테크 시장 동향 및 인사이트
높은 스마트폰 및 인터넷 보급률
스마트폰 및 인터넷 보급률은 베트남 핀테크 시장의 구조적 강점으로 작용하고 있으며, 광범위한 연결 환경을 통해 결제, 대출, 투자, 보험 각 분야에서 ‘모바일 퍼스트’ 서비스 제공이 가능해졌습니다. 정보통신부는 가정용 광섬유 및 4G 커버리지를 높은 수준으로 끌어올렸으며, 이를 통해 실시간 거래 및 계좌 개설에 대한 접근 장벽이 낮아졌습니다. 국가 계획에서는 2030년까지 5G를 대규모로 보급하는 것을 목표로 하고 있으며, 이는 즉시 신용 심사나 동적 QR 코드 결제와 같이 낮은 지연 시간을 요구하는 차세대 핀테크 활용 사례를 뒷받침하는 것입니다. 이러한 기반의 효과는 플랫폼의 성장에서도 나타나고 있으며, 주요 전자 지갑 및 은행 앱은 디지털 인프라와 사용자의 수용성을 바탕으로 규모를 급속히 확대했습니다. 이용자가 늘어남에 따라 디지털 채널과 현지 대리점의 지원을 융합한 하이브리드 모델이 디지털 문해력이 아직 성숙 단계에 있는 지역에서도 계속해서 영향력을 확대하고 있으며, 베트남의 핀테크 시장은 포용성을 유지하면서 성장을 이어가고 있습니다.
정부의 무현금화 로드맵 및 국가 디지털 전환 프로그램
무현금화 로드맵과 국가 디지털 전환 프로그램은 디지털 결제를 상업 및 공공 서비스의 주류로 자리매김시킴으로써 베트남 핀테크 시장의 성장을 가속화해 왔습니다. 공제 및 급여를 비현금 방식의 증빙과 연계하는 요건을 포함한 재정·행정 조치는 기업들이 결제 흐름과 기록 관리를 디지털화하도록 지속적인 인센티브를 제공합니다. 정부가 우선시하는 국가 데이터베이스 통합을 통해 디지털 온보딩,신용 심사, 부정 방지 기반이 되는 본인 확인, 세무, 신용 데이터의 품질이 향상되고 있습니다. 각 은행은 생체 인증에 기반한 본인 확인을 대규모로 도입함으로써 이러한 성과를 더욱 강화하고 있습니다. 이를 통해 보안이 강화되고 부정 위험이 감소할 뿐만 아니라, 새로운 본인 확인 규정 준수 또한 실현되고 있습니다. 급여, 연금, 보조금 지급이 각지의 시범 사업을 통해 디지털 채널로 전환됨에 따라, 소비자의 전환 비용은 상승하고 플랫폼에 대한 락인 효과가 강화되고 있습니다. 이를 통해 베트남 핀테크 시장 전반에 걸친 지속적인 확산이 촉진되고 있습니다.
농촌 지역의 낮은 금융 문해력과 신뢰도
인구의 70% 이상이 주요 도시 외곽에 거주하고 있어, 이는 베트남 핀테크 시장이 신뢰, 인지도 및 상품 이해도의 격차를 해소하기 위한 아웃리치 모델에 의존하고 있음을 의미합니다. 금융 포용과 디지털 전환에 초점을 맞춘 정부 프로그램은 농촌 지역에 수용 인프라와 전자 서비스를 더욱 깊이 침투시키고 있습니다. 결제 사업자, 은행 및 대리점은 금융 문해력의 한계를 해소하고 신뢰를 구축하기 위해, 모바일 온보딩과 현장 지원을 결합한 하이브리드형 서비스 제공을 시범적으로 도입하고 있습니다. 칩식 ID 및 생체 인증을 포함한 신원 확인 서비스의 보급 확대도 부정 위험을 줄이고 디지털 채널에 대한 신뢰를 높이고 있습니다. 교육, 불만 처리, 대리점의 서비스 품질에 대한 지속적인 노력이 투자 및 보험과 같은 고도화된 상품이 베트남 핀테크 시장에서 주요 대도시권을 넘어 얼마나 빠르게 확대될지를 결정짓게 될 것입니다.
부문 분석
2025년에는 디지털 결제가 71.73%라는 압도적인 점유율을 차지한 것으로 평가되는 반면, 인슈어테크는 2031년까지 연평균 성장률(CAGR) 31.28%로 가장 빠르게 성장하는 서비스 분야가 될 것으로 전망되어, 베트남 핀테크 시장의 깊이와 폭이 부각되고 있습니다. 이와 병행하여 규제 샌드박스를 통해 P2P 대출, 신용 평가, 오픈 API 분야의 통제된 시범 사업이 가능해졌으며, 이는 대출 및 데이터 주도형 모델이 개념 증명(PoC) 단계에서 대규모 전개로 전환되는 과정을 지원할 것입니다. 네오뱅킹은 은행이 지원하는 디지털 브랜드나 기술 기업과의 제휴를 통해 발전하고 있으며, 이를 통해 고객 확보부터 제품 활용에 이르는 과정이 단축되고 있습니다. 각 플랫폼 기업들이 개인 자산 증가와 낮은 진입 장벽에 대한 수요에 대응함에 따라, 주식 분할 보유 및 자동 적립 도구를 통한 디지털 투자가 확대되고 있습니다. 인슈어테크의 성장은 임베디드 판매 및 디지털 채널을 활용하고 있으며, 이는 해당 분야에 대한 외국인 투자의 확대와 판매 채널의 현대화를 뒷받침해 온 정책 환경과 부합합니다.
성장 구성의 관점에서 볼 때, 베트남의 핀테크 시장은 결제 분야가 성숙하고 다른 분야가 소규모 기반에서 가속화됨에 따라 더욱 진화할 전망입니다. 디지털 결제는 계좌 보유율이 포화 상태에 가까워짐에 따라 10%대 중반의 성장률을 유지할 전망이지만, 가맹점 확보와 B2B 결제 분야의 새로운 활용 사례가 시장의 활기를 계속 뒷받침할 것입니다. 인슈어테크의 가속화는 보험사들이 임베디드 모델 및 소비자 중심의 디지털 경험으로 전환하는 과정에서 나타나는 ‘추격’ 추세를 반영하고 있습니다. 대출·금융 분야는 오픈 뱅킹 통합, 신용 데이터 개선, 신원 확인 절차의 향상으로부터 혜택을 볼 전망이며, 이러한 요소들이 결합되어 부도 위험을 낮추고 대상 수요를 확대할 것입니다. 이러한 동향은 베트남 핀테크 업계가 결제 주도형에서 다각적인 제품 전개로 광범위하게 전환하고 있음을 보여주며, 이를 통해 수익원이 확대되고 수익 창출의 다각화가 진행될 것으로 예측됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Vietnam fintech market size is USD 4.33 billion in 2026 and is projected to reach USD 8.85 billion by 2031 at a 15.37% CAGR.
This report is Segmented by Service Proposition (Digital Payments, Digital Lending & Financing, Digital Investments, Insurtech, Neobanking), End-User (Retail, Businesses), User Interface (Mobile Applications, Web/Browser, POS/IoT Devices), and Geography (Northern Vietnam, Central Vietnam, Southern Vietnam). The Market Forecasts are Provided in Terms of Value (USD).
Vietnam Fintech Market Trends and Insights
High Smartphone & Internet Penetration
Smartphone and internet penetration are a structural advantage for the Vietnam fintech market, with widespread connectivity enabling mobile-first service delivery across payments, lending, investments, and insurance. The Ministry of Information and Communications has driven household fiber and 4G coverage to high levels, which has reduced access friction for real-time transactions and account onboarding. National planning targets 5G availability at scale by 2030, which supports the next wave of low-latency fintech use cases like instant credit decisioning and dynamic QR payments. Platform growth shows the effect of this base, as leading wallets and bank apps scaled rapidly on the back of digital infrastructure and user readiness. As participation widens, hybrid models that blend digital channels with local agent support continue to expand reach in areas where digital literacy is still maturing, keeping the Vietnam fintech market inclusive while sustaining growth.
Government Cashless Roadmap & National Digital Transformation Program
The cashless roadmap and the National Digital Transformation Program have accelerated the Vietnam fintech market by pushing digital payments into the mainstream of commerce and public services. Fiscal and administrative measures, including requirements that link deductions and benefits to non-cash evidence, have created persistent incentives for businesses to digitize payment flows and record-keeping. National database integration prioritized by the government is improving the quality of identity, tax, and credit data that underpin digital onboarding, underwriting, and fraud control. Banks have reinforced these gains by rolling out biometric ID-based authentication at scale, which has improved security outcomes and reduced fraud exposure alongside compliance with new verification rules. As payroll, pensions, and subsidy distribution migrate to digital channels through local pilots, consumer switching costs rise, and platform lock-in strengthens, supporting durable adoption across the Vietnam fintech market.
Low Financial Literacy & Trust in Rural Areas
Over 70% of the population lives outside the largest cities, which means the Vietnam fintech market depends on outreach models that address gaps in confidence, awareness, and product understanding. Government programs focused on financial inclusion and digital transformation continue to push acceptance infrastructure and e-services deeper into rural districts. Payment providers, banks, and agents are testing hybrid delivery that combines mobile onboarding with local assistance to bridge literacy constraints and build trust. Greater coverage of identity services, including chip-based IDs and biometric verification, is also reducing fraud risk and improving confidence in digital channels. A sustained focus on education, grievance redressal, and agent quality is likely to determine how quickly advanced products like investments and insurance scale beyond major urban corridors in the Vietnam fintech market.
Other drivers and restraints analyzed in the detailed report include:
- Rising Middle-Class Demand for Convenient Financial Services
- Expansion of NAPAS 247 Real-Time QR Rail
- Fragmented KYC Rules Across Ministries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Digital payments held a commanding 71.73% share in 2025, while insurtech is forecast to be the fastest-growing service line at a 31.28% CAGR through 2031, underscoring the depth and breadth of the Vietnam fintech market. In parallel, the regulatory sandbox enables controlled pilots in P2P lending, credit scoring, and open APIs, which will support lending and data-led models as they transition from proof of concept to scaled deployment. Neobanking is advancing through bank-backed digital brands and partnerships with technology players that shorten the path from customer acquisition to product activation. Digital investments are expanding through fractional equity and automated saving tools, as platforms adapt to rising retail wealth and the need for low-barrier entry. Insurtech's growth is leveraging embedded distribution and digital channels, which aligns with the policy environment that has supported greater foreign investment into the sector and modernization of distribution.
From a growth-composition perspective, the Vietnam fintech market is set to evolve as payments mature and other verticals accelerate from a smaller base. Digital payments are likely to sustain mid-teen rates as account ownership nears saturation, while new use cases in merchant acquiring and B2B payments keep activity healthy. Insurtech's acceleration reflects a catch-up dynamic, as carriers pivot toward embedded models and consumer-grade digital experiences. Lending and financing are positioned to benefit from open-banking integration, improved credit data, and better verification, which together reduce default risk and increase addressable demand. These dynamics indicate a broader shift from a payments-led to a multi-product Vietnam fintech industry, which is likely to broaden revenue pools and diversify monetization.
Complete Report Scope:
- By Service Proposition
- Digital Payments
- Digital Lending & Financing
- Digital Investments
- Insurtech
- Neobanking
- By End-User
- Retail
- Businesses
- By User Interface
- Mobile Applications
- Web / Browser
- POS / IoT Devices
- By Geography
- Northern Vietnam
- Central Vietnam
- Southern Vietnam
List of Companies Covered in this Report:
- M_Service (MoMo)
- VNPay
- ZaloPay (VNG)
- ShopeePay (Sea Ltd.)
- Grab Financial Group (Vietnam)
- BePay (Be Group)
- Timo Digital Bank
- Cake by VPBank
- TPBank
- Techcombank Digital
- Vietcombank Digital
- VPBank
- Payoo
- FinHay
- Infina
- Trusting Social
- Lendbiz
- Mirae Asset Finance Vietnam
- F88
- MFast
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 High smartphone & internet penetration
- 4.2.2 Government cash-less roadmap & National Digital Transformation Program
- 4.2.3 Rising middle-class demand for convenient financial services
- 4.2.4 Expansion of NAPAS 247 real-time QR rail
- 4.2.5 Regulatory sandbox for P2P lending & open banking
- 4.2.6 Cross-border e-commerce remittance inflows
- 4.3 Market Restraints
- 4.3.1 Low financial literacy & trust in rural areas
- 4.3.2 Fragmented KYC rules across ministries
- 4.3.3 Unsustainably high CAC from cashback wars
- 4.3.4 Limited cloud availability zones & latency issues
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Service Proposition
- 5.1.1 Digital Payments
- 5.1.2 Digital Lending & Financing
- 5.1.3 Digital Investments
- 5.1.4 Insurtech
- 5.1.5 Neobanking
- 5.2 By End-User
- 5.2.1 Retail
- 5.2.2 Businesses
- 5.3 By User Interface
- 5.3.1 Mobile Applications
- 5.3.2 Web / Browser
- 5.3.3 POS / IoT Devices
- 5.4 By Geography
- 5.4.1 Northern Vietnam
- 5.4.2 Central Vietnam
- 5.4.3 Southern Vietnam
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 M_Service (MoMo)
- 6.4.2 VNPay
- 6.4.3 ZaloPay (VNG)
- 6.4.4 ShopeePay (Sea Ltd.)
- 6.4.5 Grab Financial Group (Vietnam)
- 6.4.6 BePay (Be Group)
- 6.4.7 Timo Digital Bank
- 6.4.8 Cake by VPBank
- 6.4.9 TPBank
- 6.4.10 Techcombank Digital
- 6.4.11 Vietcombank Digital
- 6.4.12 VPBank
- 6.4.13 Payoo
- 6.4.14 FinHay
- 6.4.15 Infina
- 6.4.16 Trusting Social
- 6.4.17 Lendbiz
- 6.4.18 Mirae Asset Finance Vietnam
- 6.4.19 F88
- 6.4.20 MFast
7 Market Opportunities & Future Outlook
- 7.1 Green financing for rooftop solar boom
- 7.2 Embedded insurance in super-apps