

|
시장보고서
상품코드
2125425
스페인의 초음파 기기 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Spain Ultrasound Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
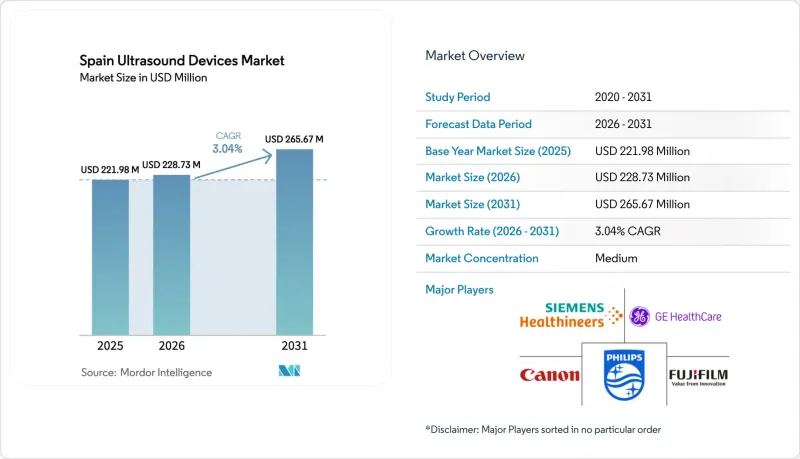
에 의하면, 스페인 초음파 기기 시장 규모는 2025년 2억 2,198만 달러에서 2026년에는 2억 2,873만 달러로 확대되어 2026년부터 2031년까지 CAGR 3.04%로 성장을 지속하여, 2031년에는 2억 6,567만 달러에 이를 것으로 예측됩니다.
본 보고서는 용도별(마취과, 순환기과,산부인과, 근골격계 등), 기술별(2D 초음파 영상 진단, 3D 및 4D 초음파 영상 진단, 도플러 영상 진단 등), 휴대성별(고정형 시스템 등), 최종 사용자별(공립 병원, 사립 병원 및 클리닉 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(대)으로 제시되어 있습니다.
스페인 초음파 기기 시장 동향 및 인사이트
고령화와 만성 질환의 부담
평균 수명의 연장으로 인해 순환기, 내분비, 근골격계 각 분야에서 초음파 기기에 대한 수요가 증가하고 있습니다. 유럽중앙은행(ECB)은 고령화와 관련된 의료비가 2070년까지 GDP의 7퍼센트 포인트 증가할 것으로 예측하고 있으며, 예산 계획에서 진단 효율성이 중요한 위치를 차지하고 있습니다. AI를 활용한 근기능 평가는 영양실조와 관련된 근감소증(사르코페니아)의 검출에서 이미 82.3%의 정확도를 달성했으며, 이는 제한된 검사 시간 내에 의사가 노인 증후군을 관리하는 데 있어 고도의 알고리즘이 얼마나 유용한지를 보여줍니다.
현장 진단(Point-of-Care) 및 휴대용 초음파 기기의 보급
안달루시아주 보건국은 1,000명 이상의 1차 진료 의사에게 복부 초음파 검사 교육을 실시하며, 병상 영상 진단 프로그램을 위한 정책 추진에 박차를 가하고 있습니다. Vscan Air 및 SonoEye와 같은 기기의 비교 평가를 통해 풀사이즈 콘솔과 동등한 진단 성능이 확인되었으며, 이는 병원이 ‘프로브 퍼스트(Probe First)’ 분류 절차를 채택하도록 뒷받침하고 있습니다. WONCA Europe이 제시한 체계적인 POCUS(포인트 오브 케어 초음파) 지침은 지역 간 의료 격차 해소에서 이 기술이 수행하는 역할을 강조하고 있습니다.
EU MDR 및 AEMPS 승인 일정
새로운 규제 하에서 인증 처리 능력이 낮아 시장 진입까지의 주기가 길어지고 있습니다. 의료기기 조정 그룹(MDCG)은 2025년까지 신청 건이 밀릴 위험이 있다고 지적하고 있으며, 이로 인해 제조업체들은 혁신이 아닌 시판 후 조사에 출시 예산을 할당해야 하는 상황에 몰리고 있습니다. 스페인의 AEMPS는 현지화된 임상 데이터 요건을 추가하여 중소기업의 자원을 압박하고 있습니다.
부문 분석
방사선과는 여전히 가장 큰 기여 분야로, 2025년 스페인 초음파 기기 시장 점유율의 37.42%를 차지하고 있습니다. 중환자 치료 분야는 규모는 작지만, 중환자 치료 레지던트 프로그램에서 초음파 진단 능력이 필수 요건으로 지정됨에 따라 연평균 성장률(CAGR) 5.87%를 달성할 것으로 예측됩니다. 스페인의 중환자 치료용 초음파 기기 시장 규모는 다중 질환을 앓고 있는 고령 환자의 입원 증가로 인해 발생한 수용 능력 격차를 메우는 궤도에 올라 있습니다. 병원에서는 쇼크 대응 팀에 휴대용 프로브를 배치하여 체액 상태를 신속하게 확인하고 심장 기능을 즉시 평가할 수 있도록 하고 있습니다. 한편, 순환기내과에서는 전자 상담 모델을 활용하여 심초음파 검사 판독을 신속하게 처리하고 있으며, 산부인과에서는 AI 도플러 분석을 도입해 산전 검진 시간을 단축하고 있습니다. 근골격계 및 류마티스학 진료 현장에서는 진료 단위의 90%에서 초음파 검사 도입이 진행되고 있으며, 이는 진료소 내 관절 평가에 대한 임상의들의 익숙함을 반영합니다. 비뇨기과 및 혈관 검사실에서는 비침습적 절제술을 위해 집속 초음파를 활용하고 있으며, 응급실에서는 외상 치료 영역의 배제 진단 프로토콜에 휴대용 스캐너를 활용하고 있습니다.
스페인 초음파 기기 시장의 참여 기업들은 콘솔의 부서 간 공유가 이용률을 향상시키며, 이것이 입찰의 중요한 기준임을 인식하고 있습니다. 스페인 중환자 의학회의 체계적인 인증이 일관된 영상 품질을 뒷받침하고 있으며, AI를 통한 의사 결정 지원이 관찰자 간 편차를 줄이고 있습니다. 환급 제도가 종합적 진료 모델로 전환됨에 따라, 다학제적 초음파 응용은 비용 절감 전략의 핵심으로 남아 있을 것입니다.
3D 및 4D 영상은 산과 분야의 검사 건수와 종양학 분야의 병기 분류 수요에 힘입어 2025년 스페인 초음파 기기 시장 규모의 41.12%를 차지했습니다. 고강도 집속 초음파(HIFU)는 5.36%의 연평균 성장률(CAGR)이 예상되며, 이는 카르투하 연구소(Cartuja Institute)의 MRgFUS를 이용한 자궁근종 치료 성공과 선근증에 대한 CE 마크 적용 범위 확대를 반영한 것입니다. 스페인 초음파 기기 시장의 이해관계자들은 HIFU의 비침습적 특성이 수술 후 입원 기간을 단축시켜 가치 기반 의료 지표와 부합한다고 지적하고 있습니다. 1차 진료 현장에서는 여전히 기존의 2D 영상 진단이 주류를 이루고 있으며, 카나리아 제도에서의 도입 사례는 폭넓은 접근성 측면에서 그 중요성을 입증하고 있습니다. 도플러 기술의 혁신은 AI를 통한 자동 분류를 통해 가속화되고 있으며, 이를 통해 태아 모니터링 워크플로우 시간을 단축하고 있습니다. 무선 및 스마트폰 연동형 프로브는 연구 참여를 확대하고 원격 교육을 지원함으로써, 학술 분야의 초음파 검사사 부족을 보완하고 있습니다.
각 개발사는 라이선스 비용을 절감하고 신속한 업그레이드를 촉진하는 오픈소스 운영 체제에 주력하고 있습니다. 이러한 방향성은 MDR의 소프트웨어 분류가 진화하는 가운데, 하드웨어의 긴 수명과 미래를 내다보는 연결성을 추구하는 스페인의 요구를 보완하는 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the Spain ultrasound devices market size is expected to grow from USD 221.98 million in 2025 to USD 228.73 million in 2026 and is forecast to reach USD 265.67 million by 2031 at 3.04% CAGR over 2026-2031.
This report is Segmented by Application (Anesthesiology, Cardiology, Gynecology/Obstetrics, Musculoskeletal, and More), Technology (2D Ultrasound Imaging, 3D & 4D Ultrasound Imaging, Doppler Imaging, and More), Portability (Stationary Systems, and More), End User (Public Hospitals, Private Hospitals & Clinics, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Spain Ultrasound Devices Market Trends and Insights
Aging population and chronic disease burden
Rising life expectancy lifts ultrasound demand across cardiology, endocrinology, and musculoskeletal care. The European Central Bank projects aging-related health costs to climb by 7 percentage points of GDP by 2070, placing diagnostic efficiency at the center of budget planning. AI-assisted muscle assessment already achieves 82.3% accuracy in detecting malnutrition-linked sarcopenia, illustrating how advanced algorithms help physicians manage geriatric syndromes with limited scan time.
Point-of-care and handheld ultrasound uptake
The Andalusian health service has trained more than 1,000 primary-care clinicians in abdominal scanning, reinforcing policy momentum for bedside imaging programs. Comparative evaluations of devices like Vscan Air and SonoEye confirm diagnostic performance on par with full-size consoles, encouraging hospitals to adopt "probe-first" triage pathways. Structured POCUS guidance from WONCA Europe underscores the technology's role in closing rural care gaps.
EU MDR and AEMPS approval timelines
Low certification throughput under the new regulation has extended market-entry cycles. The Medical Device Coordination Group noted backlog risks through 2025, prompting manufacturers to reroute launch budgets toward post-market surveillance rather than innovation. Spain's AEMPS adds localized clinical data requirements, stretching smaller companies' resources.
Other drivers and restraints analyzed in the detailed report include:
- Oncology and cardiac service capacity build-outs
- AI-enabled workflow optimization
- Public procurement price pressure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Radiology remained the largest contributor, holding 37.42% of Spain ultrasound devices market share in 2025. Critical Care, while smaller, is projected to deliver a 5.87% CAGR thanks to mandatory ultrasound competencies in intensive-care residency programs. Spain ultrasound devices market size for critical care is on track to bridge the capacity gap created by rising admissions of multimorbid elderly patients. Hospitals equip shock management teams with handheld probes that facilitate rapid fluid-status checks and cardiac function snapshots. Meanwhile, cardiology leverages electronic consultation models to accelerate echo interpretation, and gynecology/obstetrics integrates AI Doppler analytics to shorten prenatal visits. Musculoskeletal and rheumatology practitioners have raised ultrasound adoption to 90% of practice units, reflecting clinician comfort with in-office joint evaluation. Urology and vascular labs seize focused ultrasound for non-invasive ablation, and emergency departments rely on portable scanners for rule-out protocols in trauma bays.
Spain ultrasound devices market participants recognize that cross-department sharing of consoles boosts utilization rates, a key tender criterion. Structured accreditation from the Spanish Society of Intensive Medicine underpins consistent image quality, while AI decision support reduces inter-observer variability. As reimbursement moves toward bundled-care models, multispecialty ultrasound applications will remain central to cost-containment strategies.
3D & 4D imaging secured 41.12% of Spain ultrasound devices market size in 2025, driven by obstetric volume and oncologic staging needs. High-intensity Focused Ultrasound is poised for a 5.36% CAGR, reflecting Instituto Cartuja's success with MRgFUS uterine fibroid therapy and the CE extension for adenomyosis. Spain ultrasound devices market stakeholders note that HIFU's non-invasive nature lowers postoperative stays, aligning with value-based care metrics. Conventional 2D imaging persists in primary care, where the Canary Islands deployment verifies its relevance for broad access. Doppler innovation accelerates through AI auto-classification that trims fetal-monitoring workflow time. Wireless and smartphone-linked probes broaden research participation and support remote training, offsetting the shortage of academic sonographers.
Developers focus on open-source operating systems that cut licensing expenses and encourage agile upgrades. This orientation complements Spain's need for long hardware life cycles and future-proofed connectivity amid evolving MDR software classifications.
Complete Report Scope:
- By Application
- Anesthesiology
- Cardiology
- Gynecology / Obstetrics
- Musculoskeletal
- Radiology
- Critical Care
- Urology
- Vascular
- Other Applications
- By Technology
- 2D Ultrasound Imaging
- 3D & 4D Ultrasound Imaging
- Doppler Imaging
- High-Intensity Focused Ultrasound
- Other Technologies
- By Portability
- Stationary Systems
- Portable Cart-based Systems
- Hand-held / Pocket Devices
- By End User
- Public Hospitals
- Private Hospitals & Clinics
- Diagnostic Imaging Centres
- Home Healthcare Settings
- Other End Users
List of Companies Covered in this Report:
- GE Healthcare
- Siemens Healthineers
- Koninklijke Philips
- Canon
- FUJIFILM
- Mindray Medical
- Samsung Group
- Esaote
- Hologic
- Carestream Health
- Butterfly Network
- Sonoscape Medical
- Chison Medical Imaging
- Hitachi
- Terason
- Alpinion Medical
- Clarius Mobile Health
- Analogic
- Shenzhen Wisonic Medical
- Supersonic Imagine
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Population & Chronic Disease Burden
- 4.2.2 Expansion of Point-of-Care & Handheld Ultrasound Adoption
- 4.2.3 National Oncology & Cardiac Service-Capacity Build-Outs
- 4.2.4 AI-Enabled Workflow Optimization in Spanish Hospitals
- 4.2.5 Post-COVID Bedside Imaging Protocols Becoming Standard
- 4.2.6 Tele-Ultrasound Pilots in Spain's Remote Islands
- 4.3 Market Restraints
- 4.3.1 Stringent EU MDR & Spanish AEMPS Approval Timelines
- 4.3.2 Public Procurement Price Pressure
- 4.3.3 Shortage of Accredited Sonographers
- 4.3.4 Hospital CAPEX Reallocation Post-COVID
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value & Volume)
- 5.1 By Application
- 5.1.1 Anesthesiology
- 5.1.2 Cardiology
- 5.1.3 Gynecology / Obstetrics
- 5.1.4 Musculoskeletal
- 5.1.5 Radiology
- 5.1.6 Critical Care
- 5.1.7 Urology
- 5.1.8 Vascular
- 5.1.9 Other Applications
- 5.2 By Technology
- 5.2.1 2D Ultrasound Imaging
- 5.2.2 3D & 4D Ultrasound Imaging
- 5.2.3 Doppler Imaging
- 5.2.4 High-Intensity Focused Ultrasound
- 5.2.5 Other Technologies
- 5.3 By Portability
- 5.3.1 Stationary Systems
- 5.3.2 Portable Cart-based Systems
- 5.3.3 Hand-held / Pocket Devices
- 5.4 By End User
- 5.4.1 Public Hospitals
- 5.4.2 Private Hospitals & Clinics
- 5.4.3 Diagnostic Imaging Centres
- 5.4.4 Home Healthcare Settings
- 5.4.5 Other End Users
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 GE Healthcare
- 6.3.2 Siemens Healthineers AG
- 6.3.3 Koninklijke Philips N.V.
- 6.3.4 Canon Medical Systems Corporation
- 6.3.5 Fujifilm Holdings Corporation
- 6.3.6 Mindray Medical
- 6.3.7 Samsung Medison
- 6.3.8 Esaote SpA
- 6.3.9 Hologic Inc.
- 6.3.10 Carestream Health
- 6.3.11 Butterfly Network
- 6.3.12 Sonoscape Medical
- 6.3.13 Chison Medical Imaging
- 6.3.14 Hitachi Ltd.
- 6.3.15 Terason
- 6.3.16 Alpinion Medical
- 6.3.17 Clarius Mobile Health
- 6.3.18 Analogic Corporation
- 6.3.19 Shenzhen Wisonic Medical
- 6.3.20 Supersonic Imagine
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


