

|
시장보고서
상품코드
2125560
태국의 금속 포장 시장 : 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Thailand Metal Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
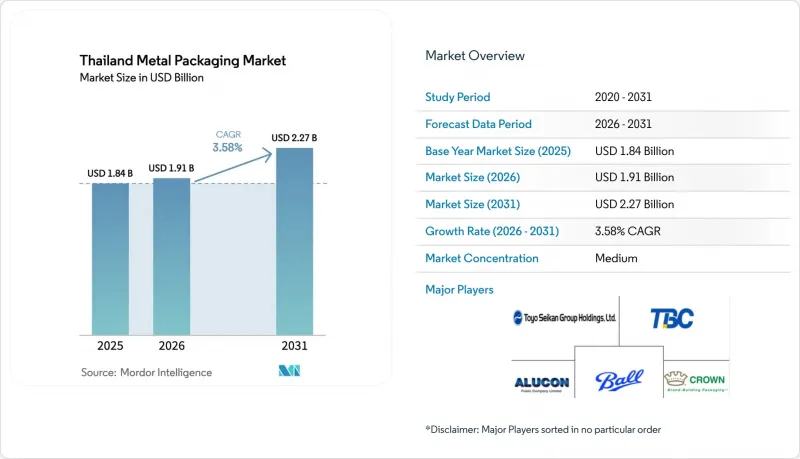
에 의하면, 태국 금속 포장 시장 규모는 2025년에 18억 4,000만 달러, 2026년에 19억 1,000만 달러되어, 2031년까지 22억 7,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년까지 CAGR 3.58%로 성장할 전망입니다.
본 보고서는 소재별(알루미늄, 강철), 제품 유형별(캔, 벌크 컨테이너, 운송용 배럴·드럼 등), 최종 사용자 산업별(음료, 식품, 도료·화학제품 등), 캔 제조 기술별(2피스 DWI, 2피스 DRD 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
태국 금속 포장 시장 동향 및 인사이트
즉석 음료의 프리미엄화
세련된 250밀리리터·330밀리리터 캔에 담긴 수제 맥주,에너지 드링크, 스파클링 티는 주류 음료보다 빠르게 성장하고 있으며, 이에 따라 가공업체들은 단위당 알루미늄 사용량을 10% 가까이 줄일 수 있는 2피스 드로우 앤 리드로우 생산 라인에 대한 투자를 확대되고 있습니다. 각 브랜드는 콜드체인에서의 결로를 줄이기 위해 360도 직접 인쇄를 채택하고 있으며, 이 기능은 이미 대형 다국적 기업이 운영하는 고속 생산 라인에 통합되어 있습니다. 이러한 프리미엄화 추세는 무알코올 음료의 신제품으로도 확산되고 있으며, 테더가 부착된 캡이나 미싱선이 있는 수축 슬리브가 편의점 등의 판매 채널에서 플라스틱 규제에 대응하는 데 기여하고 있습니다. 이러한 사양으로 인해 이음매 공차 및 두께 요건이 엄격해짐에 따라 소규모 지역 가공업체들은 설비 투자에 어려움을 겪고 있으며, 이는 업계 재편을 가속화할 가능성이 있습니다. 단기적으로는 프리미엄화 추세로 인해 알루미늄 수요가 강철을 상회하며 캔당 평균 가격을 끌어올리고 있기 때문에 음료 총 판매량이 정체되더라도 이익률은 견조한 수준을 유지하고 있습니다.
태국의 반려동물 사료 수출 거점 성장
태국은 2030년까지 반려동물 사료 수출액을 50억 달러로 늘리는 것을 목표로 하고 있으며, 이로 인해 121°C의 레토르트 살균을 견딜 수 있는 85그램 및 170그램 캔에 대한 지속적인 수요가 발생하고 있습니다. 수출처 고객들은 어류 유래 단백질로 인한 황 부식에 내성이 있는 에폭시-페놀계 코팅을 요구하고 있으며, 이 요건을 가장 잘 충족할 수 있는 것은 자동 코팅 라인을 갖춘 컨버터입니다. 걸프 시장이 이미 통조림 식품 수출의 3분의 1 이상을 차지하고 있는 만큼, 할랄 인증이 중요한 장벽으로 작용하고 있습니다. FDA 21 CFR 113 및 유럽의 이행 한계치 준수는 추가적인 기술적 검증 요건이 되며, 로트 추적이 가능한 공급업체가 유리합니다. 이러한 사양으로 인해 고차단성 금속 캔은 장기 보관이 가능한 습식 반려동물사료의 표준이 되었으며, 수출 경로에서 플렉서블 파우치를 능가하는 추세를 보이고 있습니다.
압연 강판 코일 가격 변동 심화
2024년, 아세안 지역의 열연 코일 시세는 두 자릿수 변동을 보였으며, 철강재를 현물 가격으로 조달하면서도 고객에게는 최근 평균 가격을 기준으로 청구하는 3피스 캔 제조업체들을 압박했습니다. 용접 식품 캔 비용 중 철강재가 최대 70%를 차지하기 때문에 단기적인 가격 급등은 전가 조항이 재설정되기 전에 이익률을 압박하게 됩니다. 태국은 평판강 수요의 약 60%를 수입에 의존하고 있어, 중국이 수출을 확대할 경우 가공업체들은 운임의 급격한 변동과 무역 구제 조치의 위험에 노출됩니다. 스코프 3 탄소 보고로 인해 세계 브랜드들은 저탄소 포장재로 전환해야 하는 압박을 받고 있으며, 알루미늄의 재활용성이라는 강점이 철강 업계에 더욱 큰 역풍이 되고 있습니다. 대형 페인트 통이나 산업용 드럼통에서는 여전히 철강이 주류를 이루고 있지만, 음료 및 수산물 가공업체에서는 더 가벼운 2피스 구조의 알루미늄 대체품으로의 전환이 시작되고 있습니다.
부문별 분석
2025년 매출의 69.03%를 알루미늄이 차지하고 있으며, 이는 음료 캔 및 수산물 캔 분야에서 알루미늄이 차지하는 압도적인 위상을 반영한 것입니다. 이러한 분야에서는 재활용 소재 함유율이 조달 결정의 기초가 되고 있습니다. 태국 금속 포장 시장에서 알루미늄의 점유율은 3대 주요 가공업체들이 볼(Ball)사의 재활용 소재 함유율 74%라는 벤치마크를 따르면서 더욱 상승할 것으로 예측됩니다. 경량화 노력 덕분에 맥주 제조업체들은 캔당 8-12%의 무게를 줄일 수 있게 되었습니다. 한편, 탄소 국경 조정 조치로 인해 탄소 배출량이 많은 철강에는 가격 부담이 부과될 것입니다. 철강은 도난 방지용 캡이나 20리터 페인트 통에서 여전히 중요한 역할을 하고 있지만, 수입 운임이 급등하거나 고객이 더 높은 재활용 소재 함유율을 요구할 경우, 국내에서의 비용 면에서의 우위는 점차 약화될 것입니다.
합금 비용 상승에도 불구하고, 태국의 금속 포장 시장은 2031년까지 확대될 것으로 예측됩니다. 이는 수입 슬래그에 대한 BOI의 관세 면제와 스크랩 조달 비용을 절감하는 EEC의 재활용 거점에 힘입은 결과입니다. 철강 가공 제조업체들은 에어로졸용 돔 및 산업용 드럼통 분야의 틈새 시장 리더십으로 대응하고 있지만, 코일 가격의 지속적인 변동과 VOC 규제 강화로 인해 새로운 용접 라인에 대한 자본 배분은 제한되고 있습니다. 알루미늄 스튜어드십 이니셔티브(ASI) 준수를 입증할 수 있는 공급업체는 음료 분야에서 장기 계약을 확보할 수 있어 알루미늄의 성장 궤도를 더욱 공고히할 것입니다.
2025년 매출액 중 음료 캔이 47.37%를 차지했으나, 캔(음료, 식품, 에어로졸 포함)의 총 매출은 2031년까지 연평균 성장률(CAGR) 4.26%로 성장하는 가장 빠르게 성장하는 분야가 될 것입니다. 이 부문과 관련된 태국의 금속 포장 시장 규모는 2024년에 수산 가공업체들이 63만 434톤의 참치 통조림을 출하할 예정이며, 양조장들이 매장 내 존재감을 높이기 위해 슬림형 캔을 선호하는 점으로부터 혜택을 보고 있습니다. 또한, 윤활유 수출업체들이 ISO 14001 감사에 부합하는 가압식 알루미늄 용기로 스틸 드럼에서 전환하고 있어, 에어로졸 제품이 추가적인 성장 동력이 되고 있습니다.
통, 드럼통, 캡 등 캔 이외의 용기는 화학 약품 분야에서 플렉시탱크로 대체되고, 청량음료 분야에서 플라스틱 캡이 보급됨에 따라 성장 속도가 둔화되고 있습니다. 그럼에도 불구하고, 맥주나 증류주 병입 과정에서 위조 방지 기능을 갖춘 스틸 캡이 여전히 필수적이기 때문에 캡 시장은 안정적인 틈새 시장을 형성하고 있습니다. 예측 기간 동안 브랜드 소유자들이 파우치로는 실현할 수 없는 적재성, 재활용성, 고급스러운 그래픽을 우선시함에 따라 캔은 계속해서 시장 점유율을 확대해 나갈 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.17According to Mordor Intelligence, the Thailand metal packaging market size is projected to be USD 1.84 billion in 2025, USD 1.91 billion in 2026, and reach USD 2.27 billion by 2031, growing at a CAGR of 3.58% from 2026 to 2031.

This report is Segmented by Material Type (Aluminium, and Steel), Product Type (Cans, Bulk Containers, Shipping Barrels and Drums, and More), End-User Vertical (Beverage, Food, Paints and Chemicals, and More), Can Manufacturing Technology (Two-Piece DWI, Two-Piece DRD, and More). The Market Forecasts are Provided in Terms of Value (USD).
Thailand Metal Packaging Market Trends and Insights
Premiumisation of Ready-to-Drink Beverages
Craft beers, energy drinks, and sparkling teas packaged in sleek 250- and 330-milliliter cans are growing faster than mainstream beverages, prompting converters to invest in two-piece drawn-and-redrawn lines that cut aluminum use by nearly 10% per unit. Brands deploy 360-degree direct printing to mitigate cold-chain condensation, a feature already embedded in the high-speed lines operated by leading multinationals . The premium trend is spilling into nonalcoholic launches, where tethered caps and perforated shrink sleeves help meet plastics regulations in convenience channels . As these specifications tighten seaming tolerances and gauge requirements, smaller local converters face capital hurdles that could accelerate industry consolidation. In the near term, premiumisation keeps aluminum demand ahead of steel and lifts average price per can, supporting margin resilience even as total beverage volumes flatten.
Growth of Thailand's Pet-Food Export Hub
Thailand aims to lift pet-food exports to USD 5 billion by 2030, creating sustained demand for 85-gram and 170-gram cans that withstand retort sterilization at 121 °C. Export customers insist on epoxy-phenolic coatings that resist sulfur corrosion from fish proteins, requirements best met by converters with automated coating lines. Halal certification has become a gating factor because Gulf markets already absorb more than one-third of canned-food exports. Compliance with FDA 21 CFR 113 and European migration limits adds a further layer of technical validation, favoring suppliers capable of batch traceability. These specifications position high-barrier metal cans as the default for long-shelf-life wet pet foods, outpacing flexible pouches in export channels.
Rising Price Volatility of Rolled Steel Coil
ASEAN hot-rolled-coil quotations swung double digits in 2024, squeezing three-piece can producers that buy steel spot yet invoice customers on trailing averages. Steel accounts for as much as 70% of a welded food can's cost, so a short-cycle spike erodes margins before pass-through clauses reset. Thailand imports roughly 60% of its flat-rolled requirements, exposing converters to freight-rate turbulence and trade-remedy risks when China increases exports. Scope 3 carbon reporting is pushing global brands toward low-carbon packaging, making aluminum's circularity advantage an even stronger headwind for steel. While steel remains dominant in large paint cans and industrial drums, beverage and seafood processors have begun migrating to lighter two-piece aluminum alternatives.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Halal-Certified Canned Seafood
- Government Push for Circular-Economy Aluminum
- Substitution by Bio-Polymer Pouches in Sauce
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Aluminum claimed 69.03% of 2025 revenue, reflecting its dominant position in beverage and seafood cans, where recycled content underpins procurement decisions. The Thailand metal packaging market share for aluminum is projected to rise further as three leading converters match Ball's 74% recycled-content benchmark. Lightweighting campaigns allow breweries to cut weight by 8-12% per can, while carbon border adjustment rules embed a price on steel's higher carbon footprint. Steel remains relevant for pilfer-proof closures and 20-liter paint tins, but its domestic cost advantage erodes when import freight costs spike or customers demand higher recycled content.
Despite higher alloy costs, the Thailand metal packaging market for aluminum cans is expected to expand through 2031, supported by BOI duty waivers on imported slugs and EEC recycling hubs that lower scrap input costs. Steel converters counter through niche leadership in aerosol domes and industrial drums, yet sustained volatility in coil prices and tighter VOC rules limit capital allocation to new welded lines. Suppliers able to certify Aluminum Stewardship Initiative compliance should lock in long-term beverage contracts, reinforcing aluminum's trajectory.
Beverage cans delivered 47.37% of 2025 sales, but aggregate cans, beverage, food, and aerosol, form the fastest growing cluster at a 4.26% CAGR up to 2031. The Thailand metal packaging market size attached to this cluster benefits from seafood processors shipping 630,434 tonnes of canned tuna in 2024 and from breweries that favor slim cans to enhance shelf presence. Aerosols add incremental upside as lubricant exporters migrate from steel drums to pressurized aluminum formats that meet ISO 14001 audits.
Non-can formats such as barrels, drums, and caps grow more slowly, hampered by flexitank substitution in chemicals and by plastic closures in soft drinks. Nevertheless, closures carve a stable niche because tamper-proof steel caps remain integral to beer and spirits bottling. Over the forecast window, cans will continue to capture incremental share as brand owners prioritize stackability, circularity, and premium graphics that are unattainable in pouches.
Complete Report Scope:
- By Material Type
- Aluminium
- Steel
- By Product Type
- Cans
- Food Cans
- Beverage Cans
- Aerosol Cans
- Bulk Containers
- Shipping Barrels and Drums
- Caps and Closures
- Cans
- By End-User Vertical
- Beverage
- Food
- Paints and Chemicals
- Industrial and Automotive Oils
- By Can Manufacturing Technology
- Two-Piece DWI
- Two-Piece DRD
- Three-Piece Welded
List of Companies Covered in this Report:
- Toyo Seikan Group Holdings, Ltd.
- ALUCON Public Company Limited
- Crown Holdings, Inc.
- Ball Corporation
- Thai Beverage Can Co., Ltd.
- Bangkok Can Manufacturing Co., Ltd.
- Swan Industries (Thailand) Co., Ltd.
- Lohakij Rung Charoen Sub Co., Ltd.
- Next Can Innovation Co., Ltd.
- Asian-Pacific Can Co., Ltd.
- Standard Can Co., Ltd.
- Royal Can Industries Co., Ltd.
- Great Siam Metal Packaging Co., Ltd.
- Siam Toppan Packaging Co., Ltd.
- Perfect Can Manufacturing Co., Ltd.
- Can One (Thailand) Co., Ltd.
- Thai Oil Can Manufacturing Co., Ltd.
- Supreme Metal Container Co., Ltd.
- Thien Long Metal Can (Thailand) Co., Ltd.
- WR Will (Thailand) Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors
- 4.3 Market Drivers
- 4.3.1 Premiumisation of Ready-to-Drink Beverages
- 4.3.2 Growth of Thailand's Pet-Food Export Hub
- 4.3.3 Expansion of Halal-Certified Canned Seafood
- 4.3.4 Government Push for Circular-Economy Aluminium
- 4.3.5 Rapid Scale-Up of E-Commerce Grocery Formats
- 4.3.6 Brewery Shift to Sleek and Slim Can Formats
- 4.4 Market Restraints
- 4.4.1 Rising Price Volatility of Rolled Steel Coil
- 4.4.2 Substitution by Bio-Polymer Pouches in Sauces
- 4.4.3 Slow Uptake of Recycling Infrastructure Outside EEC
- 4.4.4 Stringent VOC Emission Norms for Aerosol Plants
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Aluminium
- 5.1.2 Steel
- 5.2 By Product Type
- 5.2.1 Cans
- 5.2.1.1 Food Cans
- 5.2.1.2 Beverage Cans
- 5.2.1.3 Aerosol Cans
- 5.2.2 Bulk Containers
- 5.2.3 Shipping Barrels and Drums
- 5.2.4 Caps and Closures
- 5.2.1 Cans
- 5.3 By End-User Vertical
- 5.3.1 Beverage
- 5.3.2 Food
- 5.3.3 Paints and Chemicals
- 5.3.4 Industrial and Automotive Oils
- 5.4 By Can Manufacturing Technology
- 5.4.1 Two-Piece DWI
- 5.4.2 Two-Piece DRD
- 5.4.3 Three-Piece Welded
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Toyo Seikan Group Holdings, Ltd.
- 6.4.2 ALUCON Public Company Limited
- 6.4.3 Crown Holdings, Inc.
- 6.4.4 Ball Corporation
- 6.4.5 Thai Beverage Can Co., Ltd.
- 6.4.6 Bangkok Can Manufacturing Co., Ltd.
- 6.4.7 Swan Industries (Thailand) Co., Ltd.
- 6.4.8 Lohakij Rung Charoen Sub Co., Ltd.
- 6.4.9 Next Can Innovation Co., Ltd.
- 6.4.10 Asian-Pacific Can Co., Ltd.
- 6.4.11 Standard Can Co., Ltd.
- 6.4.12 Royal Can Industries Co., Ltd.
- 6.4.13 Great Siam Metal Packaging Co., Ltd.
- 6.4.14 Siam Toppan Packaging Co., Ltd.
- 6.4.15 Perfect Can Manufacturing Co., Ltd.
- 6.4.16 Can One (Thailand) Co., Ltd.
- 6.4.17 Thai Oil Can Manufacturing Co., Ltd.
- 6.4.18 Supreme Metal Container Co., Ltd.
- 6.4.19 Thien Long Metal Can (Thailand) Co., Ltd.
- 6.4.20 WR Will (Thailand) Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


