

|
시장보고서
상품코드
2118952
중동의 OTT 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Middle East OTT - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
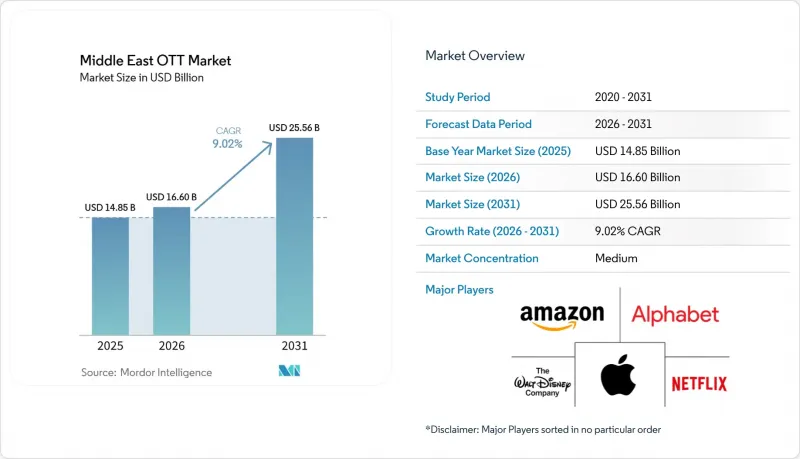
중동의 OTT 시장 규모는 2025년에 148억 5,000만 달러로 평가되었고, 2026년 166억 달러에서 2031년까지 255억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 9.02%를 나타낼 전망입니다.
본 보고서는 수익 모델별(SVOD, AVOD, TVOD, 하이브리드, 구독 및 광고), 기기 유형별(스마트폰·태블릿, 노트북·데스크톱 PC, 기타), 컨텐츠 장르별(영화, TV 프로그램·에피소드형 컨텐츠, 다큐멘터리, 기타), 지역별(사우디아라비아, 아랍에미리트, 카타르, 쿠웨이트, 바레인, 오만, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 제시되어 있습니다.
중동의 OTT 시장 동향 및 인사이트
스마트폰 및 스마트 TV 보급률 상승
2024년, 사우디아라비아의 스마트폰 보급률은 90%를 넘어섰으며, 2025년에는 걸프 국가 가구의 85% 이상에 인터넷 연결이 가능한 스크린이 도입되었습니다. 이러한 보급 기반은 시청자가 위성 기기에 의존하지 않고 모바일 기기와 가정용 스크린 사이를 자유롭게 오갈 수 있게 해주므로, 중동 OTT 시장에 유리하게 작용하고 있습니다. 또한, 인터넷 연결형 TV를 통한 시청은 선형 TV에 비해 광고주에게 더 직접적인 시청자 측정을 가능하게 합니다. 사우디아라비아, UAE, 카타르는 5G 구축을 우선시하고 있으며, 이로 인해 높은 비트레이트의 모바일 시청에 대한 장벽이 낮아지고 버퍼링도 감소하고 있습니다. 따라서 중동의 OTT 시장은 모바일을 주로 이용하는 시청자뿐만 아니라, 점점 더 큰 화면을 선호하는 가구 모두를 만족시킬 수 있습니다.
아랍어 및 현지 언어 오리지널 작품이 시청자 유지율 향상
아랍어 작품의 제작 편수는 2020년 120편에서 2025년에는 400편 이상으로 증가했으며, 2026년에는 500편을 넘어설 것으로 예측됩니다. 컨텐츠 카탈로그가 확충됨에 따라 중동 OTT 시장은 국제적인 서비스로 쉽게 대체되기 어려운 프로그램을 제공할 수 있게 됩니다. 또한, 시청 의욕이 떨어지기 쉬운 라마단 시즌 이외의 시기에도 플랫폼이 가입자를 유지하는 데 도움이 될 것입니다. 넷플릭스는 2025년 사우디아라비아의 ‘Righters House’와 공동으로 ‘Write the Future’ 장편 영화 시나리오 작가 랩을 출범시켜, 컨텐츠 라이선싱에서 인재 육성으로 그 역할을 확대했습니다. 아랍어 대본으로 제작된 드라마는 20억 달러 규모의 계절적 광고 기회로 평가받고 있지만, 제작비는 많은 서유럽 기준보다 낮습니다. 플랫폼이 적절한 권리와 배포망을 확보할 수 있다면, 이러한 조합이 구독 수익과 광고 슬롯 확보를 뒷받침하게 될 것입니다.
해적판, 계정 공유 및 불법 IPTV 유출
불법 스트리밍은 단순한 계정 공유 단계를 넘어, 프리미엄 동영상 및 스포츠 중계 분야에서 중요한 경쟁 채널로 발전하고 있습니다. 크리에이티비티 앤 엔터테인먼트 얼라이언스(ACE)에 따르면, StreamEast는 2025년 8월 폐쇄될 때까지 16억 회 이상의 접속을 기록했습니다. beIN Sports는 중동의 무단 스트리밍으로 인해 연간 10억 달러 이상의 손실을 입었습니다고 보고했습니다. 2026년 7월, 카이로 경제 법원은 StreamEast 운영자 2명에게 징역 2년형을 선고하고, 각 피고인에게 550만 이집트 파운드(11만 달러)의 벌금을 부과했습니다. 지역 사용자의 약 23%가 여전히 불법 IPTV 서비스를 이용하고 있어, 컨텐츠 구매자가 얻을 수 있는 수익을 감소시키고 있습니다. 계정 정보 공유에 대해서는 지역별 법제도가 달라, 이를 특정하기가 여전히 어려운 상황입니다.
부문 분석
2025년, SVOD는 중동 OTT 시장 점유율의 47.50%를 차지했으며, 이는 광고가 없는 아랍어 오리지널 작품 및 독점 스포츠 프로그램에 대한 수요에 힘입은 것입니다. 과거 페이퍼뷰(Pay-Per-View)로 제공되던 타이틀이 정기 구독 플랜에 포함되는 사례가 증가함에 따라, 구독형 라이브러리로 인해 TVOD의 역할은 축소되고 있습니다. TVOD는 극장 개봉 직후의 작품이나 프리미엄 라이브 이벤트 등, 즉시 이용에 대해 별도로 과금이 가능한 분야에서 여전히 중요한 역할을 수행하고 있습니다. 중동 OTT 시장 규모는 플랫폼이 가치 있는 아랍어 컨텐츠 카탈로그를 유지할 수 있는지 여부에 계속해서 좌우될 것입니다. 이러한 카탈로그의 존재는 고객이 유사한 대안들 사이를 쉽게 전환하지 않고 특정 서비스를 계속 이용하는 이유가 됩니다.
광고주가 스트리밍 광고 공간을 찾고, 시청자가 더 저렴한 대안을 추구하는 가운데, AVOD는 2031년까지 연평균 성장률(CAGR) 9.86%로 확대될 것으로 예측됩니다. 또한 유료 요금제와 무료 또는 저가 옵션을 함께 제공할 수 있다는 점에서 구독과 광고를 결합한 하이브리드 모델에도 관심이 쏠리고 있습니다. 통신 사업자는 모든 가구에 일률적인 고정 가격을 제시하지 않고, 소득 계층별로 이러한 모델을 묶어 제공할 수 있습니다. 중동의 OTT 업계는 이러한 구조를 활용함으로써 가격 민감도를 시청의 장벽이 아닌, 접근 수준의 선택지로 전환할 수 있습니다. 경쟁 플랫폼에서는 현지 프로그램이 거의 제공되지 않기 때문에 현지 컨텐츠를 갖춘 서비스는 우위를 유지하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the Middle East OTT market size was valued at USD 14.85 billion in 2025 and estimated to grow from USD 16.60 billion in 2026 to reach USD 25.56 billion by 2031, at a CAGR of 9.02% during the forecast period (2026-2031).
This report is Segmented by Revenue Model (SVOD, AVOD, TVOD, and Hybrid, Subscription and Ads), Device Type (Smartphones and Tablets, Laptops and Desktops, and More), Content Genre (Movies and Films, TV Shows and Episodic Content, Documentaries, and More), and Geography (Saudi Arabia, United Arab Emirates, Qatar, Kuwait, Bahrain, Oman, and More). The Market Forecasts are Provided in Terms of Value (USD).
Middle East OTT Market Trends and Insights
Rising Smartphone and Smart TV Penetration
Smartphone penetration exceeded 90% in Saudi Arabia during 2024, and connected screens were present in more than 85% of Gulf households in 2025. This installed base favors the Middle East OTT market because viewers can move between mobile and household screens without relying on satellite equipment. Connected television viewing also gives advertisers more direct audience measurement than linear television. Saudi Arabia, the UAE, and Qatar have prioritized 5G deployment, lowering barriers to high-bitrate mobile viewing and reducing buffering. The Middle East OTT market can therefore serve both mobile-first viewers and households that increasingly prefer larger screens.
Arabic and Local Language Originals Scaling Retention
Arabic output increased from 120 titles in 2020 to more than 400 in 2025, and was expected to exceed 500 in 2026. The larger catalog gives the Middle East OTT market programming that is less easily replaced by international services. It also helps platforms keep subscribers outside the Ramadan season, when viewing interest can otherwise weaken. Netflix launched its Write the Future Feature Film Writers Lab with Saudi Arabia's Righters House in 2025, extending its role from content licensing to talent development. Arabic-scripted drama was described as a USD 2 billion seasonal advertising opportunity, while production costs remained below many Western benchmarks. This combination supports subscription revenue and advertising inventory when platforms have suitable rights and distribution.
Piracy, Credential Sharing, and Illegal IPTV Leakage
Illegal streaming has developed beyond casual account sharing into a substantial competing channel for premium video and live sports. StreamEast logged more than 1.6 billion visits before its August 2025 shutdown, according to the Alliance for Creativity and Entertainment. beIN Sports reported annual losses exceeding USD 1 billion due to unauthorized streaming in the Middle East. In July 2026, the Cairo Economic Court sentenced 2 StreamEast operators to 2 years in prison and imposed EGP 5.5 million (USD 110,000) in fines on each defendant. An estimated 23% of regional users still access pirate IPTV services, reducing the returns available to content buyers. Credential sharing remains difficult to identify because legal treatment varies across regional jurisdictions.
Other drivers and restraints analyzed in the detailed report include:
- Telecom Bundling and Carrier Billing Expansion
- FAST and Ad-Supported Monetization Broadening Reach
- Fragmented Content Regulation and Censorship Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
SVOD held 47.50% of the Middle East OTT market share in 2025, supported by demand for ad-free Arabic originals and exclusive sports programs. Subscription libraries have reduced TVOD's role, as titles that once supported pay-per-view are increasingly included in recurring plans. TVOD remains relevant for recent theatrical releases and premium live events where immediate access can support a separate charge. The Middle East OTT market size continues to depend on the platform's ability to maintain a valuable Arabic catalog. These catalogs create a reason for customers to retain a specific service rather than switching easily between similar options.
AVOD is projected to expand at a 9.86% CAGR through 2031 as advertisers seek streaming inventory and viewers look for lower-cost choices. Hybrid subscription and advertising models are also gaining interest because they can offer paid tiers alongside free or lower-priced options. Telecom companies can bundle these models across income groups without presenting a single fixed price to every household. The Middle East OTT industry can use this structure to turn price sensitivity into a choice of access level rather than a barrier to viewing. Services with local catalogs retain an advantage because local programming is less available on competing platforms.
Complete Report Scope:
- By Revenue Model
- SVOD
- AVOD
- TVOD
- Hybrid, Subscription and Ads
- By Device Type
- Smartphones and Tablets
- Smart TVs
- Laptops and Desktops
- Other Device Types
- By Content Genre
- Movies and Films
- TV Shows and Episodic Content
- Documentaries
- Other Content Genres
- By Geography
- Saudi Arabia
- United Arab Emirates
- Qatar
- Kuwait
- Bahrain
- Oman
- Rest of Middle East
List of Companies Covered in this Report:
- Netflix, Inc.
- Amazon.com, Inc.
- Alphabet Inc.
- The Walt Disney Company
- Apple Inc.
- YuppTV, Inc.
- Paramount, a Skydance Corporation
- MBC Group
- Orbit Showtime Network FZ-LLC
- beIN MEDIA GROUP LLC
- StarzPlay Arabia FZ-LLC
- Saudi Telecom Company
- Yango Group
- Rotana Media Group Holding Company
- Saudi Broadcasting Authority
- Al Jazeera Media Network
- Zee Entertainment Enterprises Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Rising Smartphone and Smart TV Penetration
- 4.3.2 Telecom Bundling and Carrier Billing Expansion
- 4.3.3 Arabic and Local Language Originals Scaling Retention
- 4.3.4 Connected TV and Big-Screen Streaming Adoption
- 4.3.5 Content Anti-Piracy Enforcement Improving Monetization Capture
- 4.3.6 FAST and Ad-Supported Monetization Broadening Reach
- 4.4 Market Restraints
- 4.4.1 Piracy, Credential Sharing, and Illegal IPTV Leakage
- 4.4.2 Fragmented Content Regulation and Censorship Requirements
- 4.4.3 Price Sensitivity and Subscription Fatigue in Multi-Service Households
- 4.4.4 Rights Fragmentation Across Leagues, Studios, and Windowing Models
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Revenue Model
- 5.1.1 SVOD
- 5.1.2 AVOD
- 5.1.3 TVOD
- 5.1.4 Hybrid, Subscription and Ads
- 5.2 By Device Type
- 5.2.1 Smartphones and Tablets
- 5.2.2 Smart TVs
- 5.2.3 Laptops and Desktops
- 5.2.4 Other Device Types
- 5.3 By Content Genre
- 5.3.1 Movies and Films
- 5.3.2 TV Shows and Episodic Content
- 5.3.3 Documentaries
- 5.3.4 Other Content Genres
- 5.4 By Geography
- 5.4.1 Saudi Arabia
- 5.4.2 United Arab Emirates
- 5.4.3 Qatar
- 5.4.4 Kuwait
- 5.4.5 Bahrain
- 5.4.6 Oman
- 5.4.7 Rest of Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Netflix, Inc.
- 6.4.2 Amazon.com, Inc.
- 6.4.3 Alphabet Inc.
- 6.4.4 The Walt Disney Company
- 6.4.5 Apple Inc.
- 6.4.6 YuppTV, Inc.
- 6.4.7 Paramount, a Skydance Corporation
- 6.4.8 MBC Group
- 6.4.9 Orbit Showtime Network FZ-LLC
- 6.4.10 beIN MEDIA GROUP LLC
- 6.4.11 StarzPlay Arabia FZ-LLC
- 6.4.12 Saudi Telecom Company
- 6.4.13 Yango Group
- 6.4.14 Rotana Media Group Holding Company
- 6.4.15 Saudi Broadcasting Authority
- 6.4.16 Al Jazeera Media Network
- 6.4.17 Zee Entertainment Enterprises Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


