|
시장보고서
상품코드
2124411
ASEAN의 전기차 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)ASEAN Electric Vehicle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
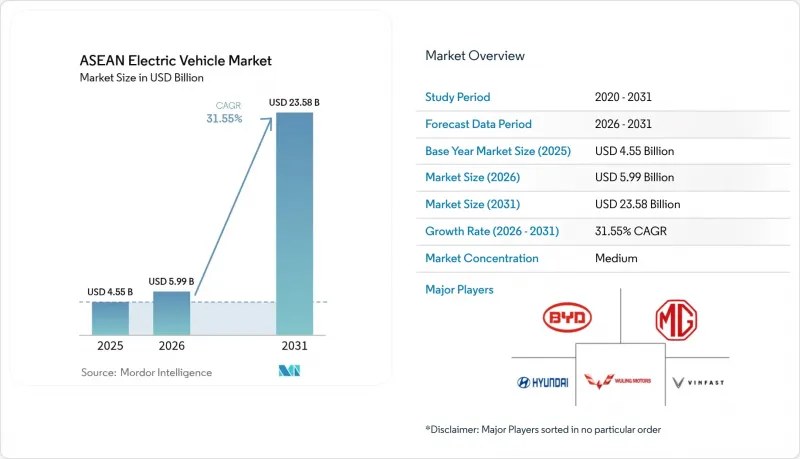
에 의하면, ASEAN 전기차 시장 규모는 2025년 45억 5,000만 달러에서 2026년에는 59억 9,000만 달러로 확대되어 2026-2031년까지 CAGR 31.55%로 성장을 지속하여, 2031년에는 235억 8,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 차종별(이륜차 및 삼륜차, 승용차, 기타), 구동계 기술별(배터리 전기차(BEV), 플러그인 하이브리드 전기차(PHEV), 기타),충전 레벨별(AC 저속 충전/레벨 2 충전, DC 급속 충전), 최종 사용자 유형별, 국가별(인도네시아, 태국, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러)과 수량(대수)으로 제시되어 있습니다.
아세안(ASEAN) 전기차 시장 동향 및 인사이트
정부의 구매 지원 및 소비세 우대 조치
적극적인 재정 정책이 아세안 전기차 시장 전반의 조기 도입을 뒷받침하고 있습니다. 태국은 보조금 수령 요건으로 현지 조립을 의무화하는 340억 바트의 보조금을 투입하고 있으며, 이 정책은 2025년까지 배터리식 전기차에 대해 사치세 0%와 부가가치세(VAT) 1%를 적용하는 인도네시아의 정책과 유사합니다. 베트남은 등록비 면제를 2027년까지 연장한 반면, 말레이시아는 구매세 경감 및 수입 관세 면제를 통해 2030년까지 전기차 판매 비중을 20%로 높이는 것을 목표로 하고 있습니다. 필리핀은 ‘전기차 산업 개발법’에 따라 정부와 기업의 차량 보유 대수 중 전기차 비중을 5%로 의무화하고 있으며, 무관세 수입을 통해 입고 비용을 더욱 절감하고 있습니다. 이러한 협력적인 정책 덕분에 태국의 전기차 판매 대수는 증가했고, 베트남의 전기 이륜차 판매 대수는 급증했습니다.
OEM의 현지 생산 추진
아세안(ASEAN)의 전기차 시장은 수입 주도형에서 현지 생산 주도형으로 전환되고 있습니다. 2025년 하반기에 가동을 시작할 BYD의 10억 달러 규모 인도네시아 거점에서는 연간 15만 대가 생산될 예정이며, 한편 자카르타 근교에 위치한 현대자동차의 15억 5,000만 달러 규모 복합 시설에서는 25만 대의 생산 능력이 추가될 예정입니다. 태국은 장성자동차(Great Wall Motor)와 치루이(Chery)를 핵심으로 삼아 중국 자동차 제조업체들로부터 30억 달러가 넘는 투자 약속을 확보했습니다. VinFast의 해외 진출에는 인도네시아와 인도에서의 신규 생산 라인이 포함되어 있으며, 지리(Geely)는 PT Handal Indonesia Motor와의 합작 투자를 통해 시장에 진출하여 3년 내에 100개 매장으로 소매망을 확대할 계획입니다. 이러한 공장들은 높아지는 현지 조달률 기준을 충족하고 물류 비용을 절감하는 동시에, 배터리, 파워 일렉트로닉스, 소프트웨어에 걸친 부품 생태계의 기반을 마련하고 있습니다.
내연기관 차량(ICE)과의 큰 소매 가격 격차
아세안 전역에서 보급형 전기차는 동급 내연기관(ICE) 차량에 비해 가격이 2배로 책정되는 경우가 많아, 이것이 대중 시장에서의 보급을 저해하고 있습니다. 인도네시아에서는 판매 대수가 267% 급증했음에도 불구하고, 2025년 상반기 시장 침투율은 9.1%에 그쳤습니다. 이는 여전히 큰 가격 차이가 가격에 민감한 구매자들의 구매 의욕을 꺾고 있기 때문입니다. 태국의 고급차 하위 부문에서는 인센티브가 단계적으로 축소되자 수요가 둔화되었으며, 보조금 폐지에 대한 수요의 탄력성이 드러났습니다. 화물 운송 사업자들은 중형 트럭의 초기 비용이 높다는 점을 지적하고 있으나, 배터리 교체 시범 사업에서는 수명 주기 전체에 걸쳐 30-40%의 비용 절감이 예상됩니다. 지속적인 가격 인하를 위해서는 현지에서 생산된 배터리 팩과 지역 내 신규 공장을 통한 규모의 경제가 핵심이 될 것입니다.
부문 분석
2025년, 아세안(ASEAN) 전기차 시장에서 승용차가 46.55%를 차지했으나, 베트남에서는 2025년 상반기 VinFast의 국내 판매가 488% 급증함에 따라 전기 이륜차 판매가 급증했습니다. 이륜차와 삼륜차는 성장 시나리오를 완전히 바꾸고 있으며, 2031년까지 연평균 성장률(CAGR) 32.40%의 성장이 예상됩니다. 인도네시아와 태국에서는 주차료 및 번호판 수수료를 면제하는 카셰어링 우대 조치를 통해 이러한 성장세가 재현되고 있습니다. 이커머스 배송 차량이 20-30%의 연료비 절감을 달성함에 따라 소형 상용차 부문이 탄력을 받고 있으며, 이는 물류 사업자들에게 전기화 의무화를 촉진하고 있습니다. 반면, 중대형 트럭은 고에너지 밀도 배터리와 초기 비용 차이를 상쇄할 재정적 조치를 기다리는 동안 뒤처지고 있습니다.
도시 지역 배송 라이더들은 충전 시간을 2분 미만으로 단축하는 배터리 교환 네트워크의 편리성을 꼽고 있습니다. 베트남은 2030년까지 무공해 이륜차 100만 대를 도입하는 것을 목표로 하고 있으며, 이러한 야심찬 목표는 하노이에서의 정체 요금 면제와 연계되어 있습니다. 싱가포르에서는 고밀도 공항 승강장에서 무공해 차량을 우선적으로 허용하는 전기 차량 공유 허가제의 시범 운영을 통해 운전자의 수익성을 높이고 있습니다. 버스와 장거리 버스는 지방자치단체의 조달 목표의 혜택을 받고 있습니다. 싱가포르는 2030년까지 전기 버스 비율을 50%로 늘리는 것을 목표로 하고 있으며, 베트남 게안성에서는 2025년 이후 신규 도입 차량을 완전 전기차로만 구성하도록 의무화하고 있습니다. 이러한 정책들이 맞물려 아세안 전기차 시장에서 교통 수단의 다양화를 가속화하고 있습니다.
2025년, 배터리 전기차(BEV)는 아세안 전기차 시장 점유율의 85.70%를 유지하며, 2031년까지 주요 OEM의 로드맵을 주도하고 있습니다. 배터리 가격 하락, 에너지 밀도 향상, 충전 네트워크 확충이 소비자의 신뢰를 강화하고 있습니다. 플러그인 하이브리드 전기차(PHV)는 고속도로 상의 충전기 정비 상황에 대해 일반 시민들의 회의적인 시각이 뿌리 깊은 태국에서 과도기적인 틈새 시장을 개척하고 있습니다. 도요타는 가정용 충전기 설치와 연장 보증을 패키지로 제공함으로써 브랜드력을 활용하여 하이브리드 차량의 잔존 가치를 지키고 있습니다.
연료전지차는 소규모 기반에서 출발했음에도 불구하고, 2026년부터 2031년까지 38.90%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 인도네시아의 PLN은 2024년 자카르타에 해당 지역 최초의 수소 충전소를 개설하고, 연간 203톤을 생산하는 22곳의 그린 수소 플랜트 건설을 계획하고 있습니다. 싱가포르에서는 항만 지역 인근의 전용 차로에서 수소 버스 실증 실험이 진행되고 있으며, 말레이시아의 페트로나스(Petronas)는 상용차에 청색 수소를 혼합하여 사용하는 방안을 검토하고 있습니다. 아세안 전역의 실무 그룹에서는 대규모 수입의 전제조건이 되는 유엔 규정 134를 준수하기 위해 연료전지 안전 기준안을 마련 중입니다. 이러한 기술의 다양성은 아세안 전기차 시장을 원자재 가격 변동으로부터 보호하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the ASEAN electric vehicle market size is expected to grow from USD 4.55 billion in 2025 to USD 5.99 billion in 2026 and is forecast to reach USD 23.58 billion by 2031 at 31.55% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (Two and Three Wheelers, Passenger Cars, and More), Drive-Train Technology (Battery Electric Vehicles (BEV), Plug-In Hybrid Electric Vehicles (PHEV), and More), Charging Level (AC Slow/Level-2, DC Fast), End-User Type, and Country (Indonesia, Thailand, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
ASEAN Electric Vehicle Market Trends and Insights
Government Purchase and Excise-Tax Incentives
Aggressive fiscal programs underpin early adoption across the ASEAN electric vehicle market. Thailand channels 34 billion baht in subsidies that require local assembly for eligibility, a policy mirrored by Indonesia's 0% luxury tax and 1% VAT on battery electric vehicles through 2025. Vietnam has extended registration-fee exemptions until 2027, while Malaysia targets a 20% EV sales mix by 2030 via purchase-tax relief and import-duty waivers. The Philippines mandates a 5% EV share in government and corporate fleets under the Electric Vehicle Industry Development Act, further reducing landed costs through zero-tariff imports. These coordinated instruments have lifted Thailand's EV sales and turbocharged Vietnam's electric-motorcycle sales volumes.
OEM Localization Commitments
The ASEAN electric vehicle market is shifting from import-led to locally manufactured supply. BYD's USD 1 billion Indonesian hub coming online in late 2025 will produce 150,000 vehicles annually, while Hyundai's USD 1.55 billion complex near Jakarta adds 250,000-unit capacity. Thailand has secured over USD 3 billion in Chinese OEM pledges, anchored by Great Wall Motor and Chery. VinFast's outward expansion includes new lines in Indonesia and India, and Geely enters via a joint venture with PT Handal Indonesia Motor to scale 100 retail outlets in three years. These factories meet rising local-content thresholds, compress logistics costs, and seed component ecosystems across batteries, power electronics, and software.
High Retail Price Gap Vs. ICE
Entry-level EVs across ASEAN are often priced at twice that of comparable internal-combustion models, curbing mass-market uptake. Indonesia's penetration reached 9.1% in 1H 2025 despite a 267% sales spike, as the remaining sticker premium deters cost-sensitive buyers. Thailand's premium-car sub-segment experienced softening demand once incentives tapered, revealing elasticity to subsidy removal. Freight operators highlight elevated upfront costs for medium-duty trucks, even though battery-swap pilots hint at 30-40% lifetime savings. Continual price compression depends on localized battery packs and scale economics from new regional plants .
Other drivers and restraints analyzed in the detailed report include:
- Rapid Roll-Out of DC Fast-Charging Corridors
- Nickel-Rich Battery Supply Advantage
- Patchy Charging Outside Tier-1 Cities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars delivered 46.55% of the ASEAN electric vehicle market in 2025, yet electric motorcycles posted a sales jump in Vietnam in 1H 2025, powered by VinFast's 488% domestic surge. Two- and three-wheelers are rewriting the growth script, projecting a growth of 32.40% CAGR by 2031. Indonesia and Thailand replicate this momentum through ride-hail incentives that waive parking fees and license-plate charges. The light-commercial segment gains traction as e-commerce fulfillment fleets log 20-30% fuel savings, nudging logistics operators toward electrification mandates. Medium and heavy trucks lag while waiting for higher-density batteries and fiscal levers that neutralize upfront differentials.
Urban delivery riders cite the convenience of battery-swap networks that compress refueling to under two minutes. Vietnam targets 1 million zero-emission motorcycles by 2030, an ambition linked to congestion-charge exemptions in Hanoi. Singapore pilots electric ride-hail permits that prioritize emissions-free vehicles at high-density airport ranks, enhancing driver economics. Buses and coaches benefit from municipal procurement targets, with Singapore aiming for 50% electric buses by 2030 and Vietnam's Nghe An province mandating fully electric additions from 2025. Collectively, these policies accelerate modal diversification within the ASEAN electric vehicle market.
Battery electric vehicles maintained 85.70% ASEAN electric vehicle market share in 2025 and anchor most OEM roadmaps through 2031. Lower battery prices, rising energy density, and expanded charging corridors reinforce consumer confidence. Plug-in hybrids carve out a transition niche in Thailand where public skepticism over highway charger availability lingers. Toyota leverages brand equity by bundling home-charger installation and extended warranties, insulating hybrid residual values.
Fuel-cell electric vehicles register the highest 2026-2031 CAGR at 38.90% from a small base. Indonesia's PLN opened the sub-region's first hydrogen station in Jakarta in 2024 and plans 22 green-hydrogen plants producing 203 tons yearly. Singapore tests hydrogen buses on dedicated lanes near port zones, and Malaysia's Petronas evaluates blue-hydrogen blending for commercial fleets. A pan-ASEAN working group is drafting fuel-cell safety codes to align with UN Regulation 134, a prerequisite for scaled imports. This technology pluralism cushions the ASEAN electric vehicle market against raw-material volatility.
Complete Report Scope:
- By Vehicle Type
- Two and Three Wheelers
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Buses and Coaches
- By Drive-train Technology
- Battery Electric Vehicles (BEV)
- Plug-in Hybrid Electric Vehicles (PHEV)
- Fuel-Cell Electric Vehicles (FCEV)
- Hybrid Electric Vehicles (HEV)
- By Charging Level
- AC Slow / Level-2
- DC Fast (>= 50 kW)
- By End-User Type
- Personal / Household
- Commercial Fleet and Logistics
- Government and Public Transport
- By Country
- Indonesia
- Thailand
- Malaysia
- Vietnam
- Philippines
- Singapore
- Myanmar
- Cambodia
- Laos
- Brunei
List of Companies Covered in this Report:
- BYD Co. Ltd.
- SAIC Motor / MG Motor
- Hyundai Motor Company
- Toyota Motor Corporation
- Honda Motor Co., Ltd.
- Mitsubishi Motors Corporation
- Nissan Motor Corporation
- VinFast Auto Ltd.
- Wuling Motors
- Great Wall Motor
- GAC Aion
- Chery Automobile
- Tesla Inc.
- BMW Group
- Mercedes-Benz Group
- Kia Corp.
- Isuzu Motors
- BAIC Group
- Stellantis NV
- UD Trucks
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Purchase and Excise-Tax Incentives
- 4.2.2 OEM Localization Commitments
- 4.2.3 Rapid Roll-Out of DC Fast-Charging Corridors
- 4.2.4 Nickel-Rich Battery Supply Advantage
- 4.2.5 Cross-Border Zero-Tariff EV Trade
- 4.2.6 Two-Wheeler Battery-Swap Ecosystems Scaling
- 4.3 Market Restraints
- 4.3.1 High Retail Price Gap Vs. ICE
- 4.3.2 Patchy Charging Outside Tier-1 Cities
- 4.3.3 Grid Instability and Peak-Load Limits
- 4.3.4 Cultural Preference for Diesel Pick-Ups
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Vehicle Type
- 5.1.1 Two and Three Wheelers
- 5.1.2 Passenger Cars
- 5.1.3 Light Commercial Vehicles
- 5.1.4 Medium and Heavy Commercial Vehicles
- 5.1.5 Buses and Coaches
- 5.2 By Drive-train Technology
- 5.2.1 Battery Electric Vehicles (BEV)
- 5.2.2 Plug-in Hybrid Electric Vehicles (PHEV)
- 5.2.3 Fuel-Cell Electric Vehicles (FCEV)
- 5.2.4 Hybrid Electric Vehicles (HEV)
- 5.3 By Charging Level
- 5.3.1 AC Slow / Level-2
- 5.3.2 DC Fast (>= 50 kW)
- 5.4 By End-User Type
- 5.4.1 Personal / Household
- 5.4.2 Commercial Fleet and Logistics
- 5.4.3 Government and Public Transport
- 5.5 By Country
- 5.5.1 Indonesia
- 5.5.2 Thailand
- 5.5.3 Malaysia
- 5.5.4 Vietnam
- 5.5.5 Philippines
- 5.5.6 Singapore
- 5.5.7 Myanmar
- 5.5.8 Cambodia
- 5.5.9 Laos
- 5.5.10 Brunei
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 BYD Co. Ltd.
- 6.4.2 SAIC Motor / MG Motor
- 6.4.3 Hyundai Motor Company
- 6.4.4 Toyota Motor Corporation
- 6.4.5 Honda Motor Co., Ltd.
- 6.4.6 Mitsubishi Motors Corporation
- 6.4.7 Nissan Motor Corporation
- 6.4.8 VinFast Auto Ltd.
- 6.4.9 Wuling Motors
- 6.4.10 Great Wall Motor
- 6.4.11 GAC Aion
- 6.4.12 Chery Automobile
- 6.4.13 Tesla Inc.
- 6.4.14 BMW Group
- 6.4.15 Mercedes-Benz Group
- 6.4.16 Kia Corp.
- 6.4.17 Isuzu Motors
- 6.4.18 BAIC Group
- 6.4.19 Stellantis NV
- 6.4.20 UD Trucks
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment