|
시장보고서
상품코드
2125746
베트남의 전기자동차 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Vietnam Electric Vehicle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
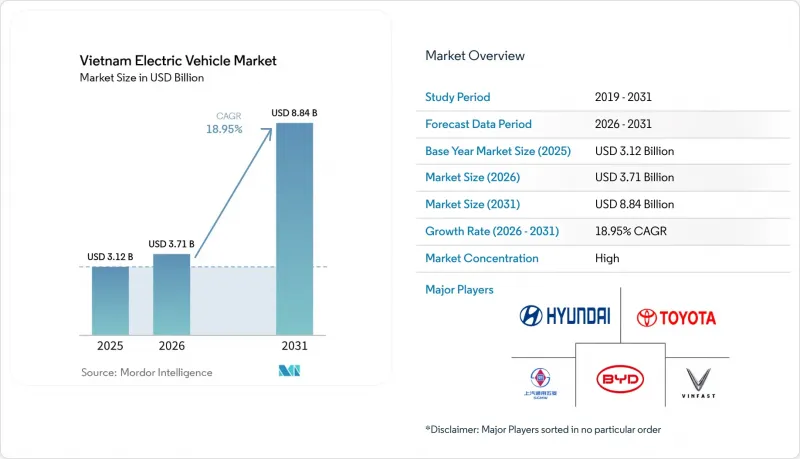
에 의하면, 2026년 베트남 전기자동차 시장 규모는 37억 1,000만 달러로 추정되고, 2025년 31억 2,000만 달러에서 확대될 전망입니다.
또한, 2031년의 예측치는 88억 4,000만 달러로 추정되며, 2026-2031년 연평균 성장률(CAGR) 18.95%로 성장할 것으로 전망됩니다.
본 보고서는 차종별(승용차, 상용차, 기타), 구동 방식별(배터리식 전기자동차, 플러그인 하이브리드 전기자동차, 기타),주행 거리별(200km 이하, 200-400km, 기타), 배터리 유형별(LFP, 기타), 최종 사용자별(개인 소유, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)과 수량(대수)으로 제시되어 있습니다.
베트남의 전기자동차 시장 동향 및 인사이트
국내 생산 확대(VinFast 및 수입차)
VinFast는 2026년까지 국내 조달 비율을 약 80%로 높이는 것을 목표로 하고 있으며, 2027년까지 생산 능력을 약 50만 대, 2030년까지 연간 최대 100만 대까지 확대할 예정입니다. 이러한 생산 규모 확대는 부품 1개당 비용을 절감하고, 공급업체의 현지화를 심화하며, 수입 부품으로 인한 환율 변동 위험을 줄이는 것을 목적으로 합니다. Chery와 Geely의 병행 투자 계획은 신흥 지역 조립 및 수출 허브로서 베트남의 위상을 더욱 공고히 하고 있습니다. 그러나 첨단 반도체, 파워 일렉트로닉스, 배터리 관리 시스템 등 고부가가치 부품의 경우, 국내 생산 능력이 제한적이어서 여전히 수입에 대한 의존도가 높습니다. VinFast가 주도하는 장기 조달 및 인수 계약을 통해 현지 공급업체들은 수요 전망을 더 명확히 파악할 수 있게 되었으며, 이는 새로운 설비 투자, 기술 이전, 생태계 현지화의 가속화를 뒷받침하고 있습니다.
정부의 우대 조치 및 세금 환급
정부의 인센티브 체계에 따라 2027년 2월까지 전기자동차(BEV) 등록비가 전액 면제되어, 이를 통해 소비자 및 차량 대여 사업자의 초기 구매 비용이 대폭 절감되고 있습니다. 이와 동시에, 현행 지역 무역 협정에 따라 아세안(ASEAN) 회원국에서 조달되는 차량에 대한 수입 관세는 0%로 유지되고 있으며, 대상 모델 1대당 소매 가격은 1억 VND 이상 인하되었습니다. 전기자동차용 우대 충전 요금이 1kWh당 약 2,204VND로 설정됨에 따라, 전체 수명 주기 동안의 운영 경제성이 더욱 향상되고, 내연기관 차량과의 회수 기간이 단축됨과 동시에 총 소유 비용(TCO)의 경쟁력이 강화되어 다층적인 정책 연계가 두드러지고 있습니다. 2027년 이후의 지속 여부는 비용 평준화 달성에 달려 있으며, 시장에는 재정 정책의 지속성에 대한 리스크가 잠재되어 있습니다.
공공 충전 인프라 부족
충전 인프라는 주요 대도시권에서는 비교적 잘 정비되어 있지만, 지방이나 도시 간을 연결하는 회랑을 따라서는 커버율이 급격히 떨어지고 있어 장거리 이동의 실현성을 저해하고, 주행 거리가 200km 이하인 모델을 초과하는 차종에 대한 수요를 제한하고 있습니다. 이러한 불균형한 분포로 인해 대도시권을 넘어선 광역적인 시장 확대가 제약받고 있습니다. V-Green은 전국적인 충전소 확대를 가속화하기 위해 약 4억 400만 달러를 투자하고 있지만, 인허가 절차 기간, 송전망 통합 일정, 건설 리드타임을 고려할 때, 단기적으로는 병목 현상이 지속될 것으로 보입니다. 계절적인 전력 수요의 급증은 송전망에 대한 부담 위험을 더욱 높이고 있으며, 전기자동차의 지속적인 보급을 뒷받침하기 위해 송전 용량 강화와 전력 공급의 복원력 확보에 초점을 맞춘 정부 지침이 제시되고 있습니다.
부문 분석
2025년에는 승용차가 총매출의 67.65%를 차지하며 시장 전체에 대한 기여도 측면에서 계속해서 주도적인 위치를 유지한 반면, 버스는 연평균 성장률(CAGR) 33.11%라는 가장 빠른 성장 궤적을 기록했습니다. 지방 자치단체의 전기화 의무화로 인해 대규모 공공 입찰 및 체계적인 조달 주기가 촉진됨에 따라, 버스 부문은 2028년까지 급속히 확대될 것으로 예측됩니다. 현재 차량 보유 대수에서는 개인 소유가 주류를 이루고 있지만, 상업 사업자에 의한 수요 증가가 점점 더 두드러지고 있습니다. 호치민시의 대규모 도입과 하노이 중심 지역의 전기화 로드맵에 따라 예측 가능한 대량 주문이 발생하고 있으며, 이로 인해 공급업체의 가시성과 생산 계획이 강화되고 있습니다.
차량 함대 운영의 높은 일일 가동률은 총 소유 비용(TCO)의 우위를 더욱 높여주며, 상업용 구매자들을 첨단 배터리 화학 기술 및 대용량 급속 충전 솔루션의 조기 도입자로 자리매김하고 있습니다. 한편, 이륜차는 계속해서 도시 외곽 및 농촌 지역의 교통 회랑에서 통근 수요를 뒷받침하고 있으며, 간접적으로 충전소의 이용 효율을 향상시켜 사륜차의 보급도 촉진하고 있습니다. 예측 기간 동안 승용차의 매출 점유율은 절대 수량이 증가함에도 불구하고 소폭 둔화될 전망입니다. 이는 대중교통의 현대화와 라스트 마일 물류 네트워크에서 버스와 전기 밴이 정책의 뒷받침을 받아 성장세를 보이고 있기 때문입니다.
2025년에는 배터리 전기자동차(BEV)가 전체 시장 점유율의 70.82%를 차지했으며, 하이브리드차나 플러그인 하이브리드 전기자동차와 같은 대체 차량을 확실히 앞질렀습니다. 과도기적인 구동 기술보다 완전한 전동화를 우선시하는 국가 정책의 틀에 힘입어, BEV의 판매 대수는 연평균 성장률(CAGR) 27.85%로 확대될 것으로 예측되며, 이러한 선두 격차는 더욱 벌어질 전망입니다. 하이브리드차는 주행 거리 유연성을 추구하는 도시 외곽 지역 사용자들 사이에서 제한적인 수요를 유지하고 있지만, 재정적 인센티브가 비교적 제한적이어서 더 광범위한 보급에는 제약이 따르고 있습니다. 연료전지차는 수소 인프라가 미비하고 도입 비용이 높기 때문에 여전히 주로 시험 단계에 머물러 있습니다.
VinFast의 BEV에 중점을 둔 집중적인 제품 전략은 소비자 인식 속에서 순수 전기자동차로서의 입지를 강화하고 있으며, 전국적인 충전 인센티브가 도입의 탄력을 더욱 뒷받침하고 있습니다. 국제 자동차 제조업체들은 남아 있는 주행 거리 불안을 해소하기 위해 플러그인 하이브리드(PHV) 모델을 도입할 가능성이 있지만, 규제 방향은 여전히 순수 전기자동차(BEV) 플랫폼을 우선시하고 있습니다. 배터리 기술의 지속적인 발전으로 충전 시간이 단축되고 에너지 밀도가 향상되면서, 과거 하이브리드 차량의 가격 프리미엄을 정당화했던 기능적 격차가 점차 줄어들고 있습니다. 그 결과, 베트남의 전기자동차 시장은 일부 성숙한 경제권에서 볼 수 있는 단계적인 하이브리드차로의 전환 과정을 거치지 않고, BEV로의 직접적인 전환 궤도를 따르고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Vietnam electric vehicle market size in 2026 is estimated at USD 3.71 billion, growing from the 2025 value of USD 3.12 billion, with 2031 projections showing USD 8.84 billion, growing at 18.95% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (Passenger Cars, Commercial Vehicles, and More), Propulsion (Battery Electric Vehicles, Plug-In Hybrid Electric Vehicles, and More), Driving Range (Below 200 Km, 200 To 400 Km, and More), Battery Type (LFP, and More), End User (Private Ownership and More), and Region. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Vietnam Electric Vehicle Market Trends and Insights
Domestic Manufacturing Scale-up
VinFast targets roughly 80% domestic content by 2026 while expanding installed capacity to about 500,000 vehicles by 2027 and up to 1 million units annually by 2030. This scale-up is designed to compress per-unit component costs, deepen supplier localization, and reduce exposure to exchange-rate volatility tied to imported parts. Parallel investment plans from Chery and Geely further strengthen Vietnam's position as an emerging regional assembly and export hub. However, high-value components such as advanced semiconductors, power electronics, and battery management systems continue to rely significantly on imports due to limited domestic fabrication capability. Long-term procurement and offtake agreements led by VinFast provide local suppliers with stronger demand visibility, supporting fresh capital expenditure, technology transfer, and faster ecosystem localization.
Government Incentives and Tax Rebates
The national incentive framework extends full registration-fee exemptions for battery electric vehicles through February 2027, materially lowering upfront acquisition costs for consumers and fleet operators. In parallel, import duties remain at 0% for vehicles sourced from ASEAN member states under prevailing regional trade agreements, reducing retail prices by more than VND 100 million per unit for qualifying models. Preferential EV charging tariffs set at approximately 2,204 VND/kWh further improve lifetime operating economics, narrowing payback periods versus internal combustion alternatives and strengthening the total cost of ownership proposition, underscoring multi-tier policy coordination. Continuity beyond 2027 depends on reaching cost parity, exposing the market to fiscal-policy rollover risk.
Sparse Public Charging Infrastructure
While charging infrastructure remains relatively dense across tier-one urban clusters, coverage declines sharply along rural and inter-city corridors, constraining long-distance travel viability and limiting demand for models exceeding sub-200 km range brackets. This uneven distribution restricts broader geographic market expansion beyond metropolitan centers. V-Green has committed approximately USD 404 million to accelerate nationwide station deployment, yet permitting cycles, grid integration timelines, and construction lead times suggest near-term bottlenecks will persist. Seasonal electricity demand spikes further expose grid stress risks, prompting government directives focused on strengthening transmission capacity and ensuring power-supply resilience to support sustained EV penetration.
Other drivers and restraints analyzed in the detailed report include:
- Rising Environmental Awareness and Net-Zero Targets
- Electric Two-wheeler Ecosystem Spill-over
- High Up-front Vehicle Cost vs Average Income
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars accounted for 67.65% of total revenue in 2025, maintaining leadership in overall market contribution, while buses recorded the fastest expansion trajectory at a 33.11% CAGR. The bus segment is expected to scale rapidly through 2028 as provincial electrification mandates unlock sizeable public tenders and structured procurement cycles. Although private ownership dominates the current vehicle base, commercial operators are increasingly shaping incremental demand. Large-scale deployments in Ho Chi Minh City and the central-district electrification roadmap in Hanoi are creating predictable bulk orders that strengthen supplier visibility and manufacturing planning.
High daily utilization rates in fleet operations amplify total-cost-of-ownership advantages, positioning commercial buyers as early adopters of advanced battery chemistries and high-capacity fast-charging solutions. Meanwhile, two-wheelers continue serving commuter flows across peri-urban and rural corridors, indirectly improving charging-station utilization economics that also support four-wheeler penetration. Over the forecast horizon, passenger-car revenue share is likely to moderate slightly despite rising absolute volumes, as buses and electric vans gain policy-driven traction in public transport modernization and last-mile logistics networks.
Battery electric vehicles (BEVs) accounted for 70.82% of the total market share in 2025, clearly outperforming hybrid and plug-in hybrid alternatives. This lead is expected to widen as BEV volumes expand at a projected 27.85% CAGR, supported by a national policy framework that prioritizes full electrification over transitional drivetrain technologies. Hybrids retain selective demand among peri-urban users seeking extended range flexibility, yet comparatively limited fiscal incentives constrain broader uptake. Fuel-cell vehicles remain largely at a pilot stage due to minimal hydrogen infrastructure and high deployment costs.
VinFast's concentrated BEV-focused product strategy reinforces the pure-electric positioning in consumer perception, while nationwide charging incentives further strengthen adoption momentum. International automakers may introduce plug-in hybrid variants as a hedge against residual range anxiety, but regulatory direction continues to favor fully electric platforms. Continuous battery improvements are reducing charging times and improving energy density, narrowing the functional gap that once justified hybrid premiums. Consequently, the Vietnam electric vehicle market is progressing along a direct-to-BEV trajectory rather than following the phased hybrid transition observed in several mature economies.
Complete Report Scope:
- By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- Two-Wheelers
- Buses
- By Propulsion
- Battery Electric Vehicles (BEV)
- Plug-in Hybrid Electric Vehicles (PHEV)
- Hybrid Electric Vehicles (HEV)
- Fuel-Cell Electric Vehicles (FCEV)
- By Driving Range
- Below 200 km
- 200 to 400 km
- Above 400 km
- By Battery Type
- LFP
- NMC/NCA
- Others
- By End User
- Private Ownership
- Commercial Fleet/Ride-Hailing
- Government and Public Transport
- By Region
- Northern Vietnam
- Central Vietnam
- Southern Vietnam
List of Companies Covered in this Report:
- VinFast Auto Ltd.
- Hyundai Motor Company
- Toyota Motor Corporation
- BYD Auto Co. Ltd
- SAIC-GM-Wuling Automobile Co., Ltd.
- Tesla Inc.
- Mercedes-Benz Group AG
- Kia Corporation
- Nissan Motor Co. Ltd
- Honda Motor Co. Ltd
- MG Motor (China)
- Chery Automobile Co.
- Great Wall Motor (Haval)
- Volvo Car AB
- Selex Motors (VN)
- Dat Bike (VN)
- Foxconn EV Charging (VN)
- VinES Battery (VN)
- ABB Vietnam (Chargers)
- Delta Electronics (VN)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Domestic Manufacturing Scale-up (VinFast and Imports)
- 4.2.2 Government Incentives and Tax Rebates
- 4.2.3 Rising Environmental Awareness and Net-Zero Targets
- 4.2.4 Electric Two-Wheeler Ecosystem Spill-Over
- 4.2.5 Falling Battery Pack Prices
- 4.2.6 Preferential EV-Charging Tariff Structure
- 4.3 Market Restraints
- 4.3.1 Sparse Public Charging Infrastructure
- 4.3.2 High Up-Front Vehicle Cost Vs Average Income
- 4.3.3 Limited Mid-Range Model Availability
- 4.3.4 Grid Capacity Constraints At Peak Hours
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 EV Charging Infrastructure Development
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.2 Commercial Vehicles
- 5.1.3 Two-Wheelers
- 5.1.4 Buses
- 5.2 By Propulsion
- 5.2.1 Battery Electric Vehicles (BEV)
- 5.2.2 Plug-in Hybrid Electric Vehicles (PHEV)
- 5.2.3 Hybrid Electric Vehicles (HEV)
- 5.2.4 Fuel-Cell Electric Vehicles (FCEV)
- 5.3 By Driving Range
- 5.3.1 Below 200 km
- 5.3.2 200 to 400 km
- 5.3.3 Above 400 km
- 5.4 By Battery Type
- 5.4.1 LFP
- 5.4.2 NMC/NCA
- 5.4.3 Others
- 5.5 By End User
- 5.5.1 Private Ownership
- 5.5.2 Commercial Fleet/Ride-Hailing
- 5.5.3 Government and Public Transport
- 5.6 By Region
- 5.6.1 Northern Vietnam
- 5.6.2 Central Vietnam
- 5.6.3 Southern Vietnam
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 VinFast Auto Ltd.
- 6.4.2 Hyundai Motor Company
- 6.4.3 Toyota Motor Corporation
- 6.4.4 BYD Auto Co. Ltd
- 6.4.5 SAIC-GM-Wuling Automobile Co., Ltd.
- 6.4.6 Tesla Inc.
- 6.4.7 Mercedes-Benz Group AG
- 6.4.8 Kia Corporation
- 6.4.9 Nissan Motor Co. Ltd
- 6.4.10 Honda Motor Co. Ltd
- 6.4.11 MG Motor (China)
- 6.4.12 Chery Automobile Co.
- 6.4.13 Great Wall Motor (Haval)
- 6.4.14 Volvo Car AB
- 6.4.15 Selex Motors (VN)
- 6.4.16 Dat Bike (VN)
- 6.4.17 Foxconn EV Charging (VN)
- 6.4.18 VinES Battery (VN)
- 6.4.19 ABB Vietnam (Chargers)
- 6.4.20 Delta Electronics (VN)
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment