|
시장보고서
상품코드
2124414
동남아시아의 중고차 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South-East Asia Used Car - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
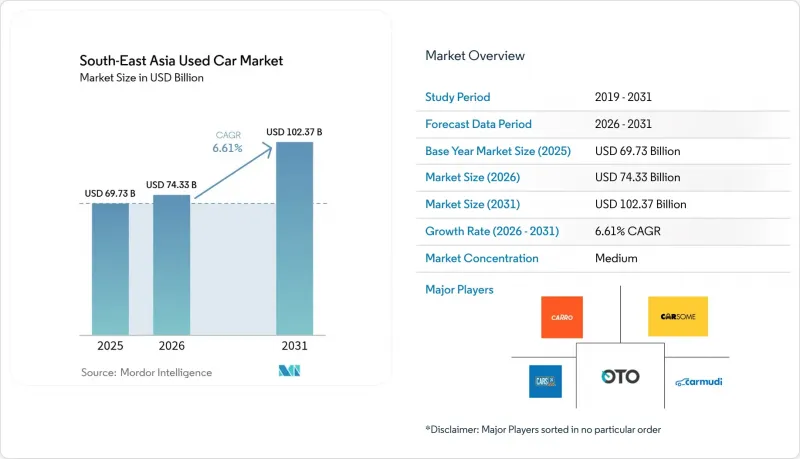
에 의하면, 동남아시아 중고차 시장 규모는 2025년에 697억 3,000만 달러, 2026년에 743억 3,000만 달러가 되어, 2031년까지 1,023억 7,000만 달러에 이를 것으로 예측되며, 2026-2031년까지 CAGR 6.61%로 성장할 전망입니다.
본 보고서는 차종별(해치백, 기타), 연료 유형별(가솔린, 디젤, 기타), 차량 연식별(0-3년, 기타),주행 거리별(3만 km 이하, 기타), 유통 채널별(오프라인 및 온라인), 공급업체 유형별(조직형 및 비조직형), 구매 방법별, 국가별로 분류되어 있습니다. 시장 전망은 금액(달러)과 수량(대)으로 제시되어 있습니다.
동남아시아 중고차 시장 동향과 인사이트
조직형 딜러 네트워크 및 인증 중고차 프로그램의 확대
‘Toyota U-Trust’와 ‘Honda Certified’는 1년 보증과 100개 항목의 점검을 추가로 제공하며, 많은 SUV 구매자들은 안심감을 얻기 위해 그 프리미엄 가격을 기꺼이 지불하고 있습니다. 고급차 브랜드는 한 걸음 더 나아가고 있습니다. 싱가포르의 ‘BMW 프리미엄 셀렉션’은 24개월 보증과 계열 금융기관을 통한 금리 할인을 제공하여 고객을 브랜드 라이프사이클에 묶어두고 있습니다. 말레이시아의 차량 검사 기관인 푸스파콤(Puspakom)은 2025년에 AI를 활용한 ‘CAVIS V4’를 도입하여, 정식 대리점에 노상 판매업자와의 차별화를 도모할 수 있는 외부 벤치마크를 제공했습니다.
통합형 금융 및 보험 솔루션 제공
Carsome Capital은 부실채권을 억제함으로써 입지를 강화했습니다. 이는 차주의 현금 흐름 데이터와 AI를 활용한 차량 등급 평가를 통합하여, 이를 통해 신용 위험 평가를 정교화함으로써 달성되었습니다. 이러한 치밀한 전략을 통해 AmBank와 Maybank를 비롯한 대형 은행들의 신뢰를 얻었으며, 이들 은행으로부터 막대한 신용 한도가 제공됨과 동시에 Carsome의 대출 모델에 대한 신뢰도도 높아졌습니다. 2025년 초, JACCS는 긱 경제 부문에 주목하여 Carsome의 상당한 소수 지분을 인수했습니다. 이 회사는 전자 지갑 거래를 비롯한 얼터너티브 데이터 스트림을 활용하여 사업 범위를 확대했습니다. 동시에 Carsome은 보험 번들 상품을 도입하여 로드사이드 어시스턴스 서비스를 월별 할부 결제에 원활하게 통합했습니다. 이러한 조치는 구매자의 구매 장벽을 낮췄을 뿐만 아니라 고객 경험을 풍부하게 하고, Carsome 생태계 내 수수료율을 향상시켰습니다.
비공식 딜러와 길거리 판매점의 부상
동남아시아 중고차 시장에서는 현금 거래를 주된 방식으로 하는 길거리 딜러들이 정식 신용 조사를 필요로 하지 않으면서 저렴한 가격과 유연한 주 단위 할부 계획을 제공함으로써 공인 판매업체들을 앞지르고 있습니다. 예를 들어, 자카르타의 케마요란 시장에서는 디지털 기록보다 사회적 신뢰가 우선시되는 경우가 많아, 이러한 비공식 딜러들의 입지가 더욱 공고해지고 있습니다. 한편, 태국에서는 은행 대출 규제가 강화되면서 많은 소규모 딜러들이 폐업에 내몰리고 있습니다. 살아남은 딜러들은 정비 비용을 피하기 위해 재고를 확보하는 수단으로 압류 차량 경매에 의존하고 있습니다. 또한, 딜러에 대한 면허 취득이 의무화되어 있지 않기 때문에 규제 대상에서 제외된 판매업자는 규정 준수 비용을 낮게 유지할 수 있어, 더 엄격한 규제에 얽매여 있는 정식 딜러에 비해 경쟁 우위를 점하고 있습니다.
부문 분석
SUV는 2025년 시장 점유율의 32.37%를 차지하고 있으며, 연평균 성장률(CAGR) 6.63%를 나타낼 것으로 예측되는데, 이는 모든 차체 유형 중 가장 높은 성장률입니다. 동남아시아의 중고 SUV 시장은 3년이 지난 후에도 잔존 가치가 구매 가격의 60-70%를 유지한다는 점을 배경으로, 2031년에는 331억 달러에 달할 것으로 예측됩니다. 태국의 토요타 ‘포츈너’와 인도네시아의 미쓰비시 ‘익스팬더’는 고상형 차량을 인증 중고차 시장에 공급하고 있는 반면, 말레이시아의 프로톤 ‘X70’은 중가 시장을 주도하고 있습니다. 기업 및 차량 공유 사업자의 차량이 크로스오버 차량으로 전환됨에 따라 세단의 점유율은 하락하고 있습니다. 해치백과 다목적 차량(MPV)은 좁은 도심 도로에서 컴팩트한 차체가 선호되는 베트남과 필리핀에서 틈새 수요를 모으고 있습니다.
SUV의 교체 주기는 평균 3-5년인 반면, 세단은 5-7년으로, 이로 인해 보증 기간 연장 대상이 되는 최신 모델이 시장에 유입되고 있습니다. BYD ‘Atto 3’와 같은 신형 모델은 2028년까지 공급원을 확충할 예정이며, 그때쯤이면 얼리 어답터들이 동남아시아 중고차 시장에 재진입하게 될 것입니다. 인증 중고차 프로그램은 재정비 비용이 더 높은 재판매 가격으로 상쇄되기 때문에 SUV를 엄선하여 도입하고 있습니다.
2025년 시장 점유율에서 가솔린 차량은 여전히 73.36%를 차지하고 있지만, 전기차(EV)는 2031년까지 연평균 성장률(CAGR) 6.71%로 성장할 전망입니다. 말레이시아의 ‘배터리 패스포트’ 제도는 배터리의 건강 상태 점수를 제공함으로써, 중고 전기차 구매 시 할인 폭을 기존 30-40%에서 20%로 축소하고 있습니다.
2020년 판매 대수가 150대 이하라는 소극적인 수준에서 시작된 전기차(EV) 판매는 특히 2025년 상반기에 두드러진 성장세를 보였습니다. 2025년 2분기까지 분기 판매 대수는 약 2만 2,000대까지 증가했습니다. 이 차량의 대부분은 2028년 이후 동남아시아의 중고차 시장으로 유입될 것입니다. 방콕과 자카르타에서 저공해 구역이 도입됨에 따라 디젤차의 존재감은 줄어들고 있습니다. 베트남에서는 2026년에 하이브리드 차량 세금을 내연기관 차량 세금의 70%로 설정하는 세제 우대 조치가 도입되어, 이를 통해 하이브리드 차량의 보급이 촉진되고 향후 공급이 확대될 전망입니다.
2025년에는 차령 4-6년 부문이 38.72%라는 압도적인 점유율을 차지했습니다. 그러나 현재는 가격 면에서 압박을 받고 있습니다. 2015년 이후 태국의 중고차 지수는 30포인트 이상 급락하며 잔존 가치가 하락하고 있습니다. 한편, 0-3년 차 부문은 급속히 부상하고 있으며, 연평균 성장률(CAGR)은 6.78%로 예측됩니다. 이러한 성장은 SUV의 조기 교체 및 잔존 가치 보증에 힘입어 가속화되고 있으며, 이 두 요인이 차량 교체 주기의 단축을 촉진하고 있습니다.
한편, 베트남과 태국 양국에서는 10년 이상 경과한 수입차에 대해 엄격한 정책적 과제가 부과되고 있습니다. 이에 따라 구매자들은 연식이 더 새로운 인증 중고차로 눈을 돌리게 되었으며, 동남아시아 중고차 시장에서 정식 유통 채널로의 이동 추세가 더욱 강화되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the south-East Asia used car market size is projected to be USD 69.73 billion in 2025, USD 74.33 billion in 2026, and reach USD 102.37 billion by 2031, growing at a CAGR of 6.61% from 2026 to 2031.
This report is Segmented by Vehicle Type (Hatchback and More), Fuel Type (Gasoline, Diesel, and More), Vehicle Age (0 To 3 Years and More), Mileage (Less Than 30, 000 Km and More), Sales Channel (Offline and Online), Vendor Type (Organized and Unorganized), Purchase Method, and Country. The Market Forecasts are Provided in Value (USD) and Volume (Units).
South-East Asia Used Car Market Trends and Insights
Growth in Organized Dealership Networks and Certified Pre-Owned Programs
Toyota U Trust and Honda Certified add one-year warranties and 100-point inspections, commanding premiums that many SUV buyers accept for peace of mind . Luxury badges push the envelope: BMW Premium Selection in Singapore offers 24-month coverage and rate discounts through its captive lender, tethering clients to the brand's lifecycle. Malaysia's inspection firm Puspakom rolled out AI-aided CAVIS V4 in 2025, giving organized lots an external benchmark to distance themselves from curbside sellers .
Availability of Integrated Financing and Insurance Solutions
Carsome Capital bolstered its standing by curbing non-performing loans. This was achieved by merging borrower cash-flow data with AI-driven vehicle grading, thereby refining credit risk assessments. Such a meticulous strategy won the trust of major banks, including AmBank and Maybank, which offered substantial credit lines and bolstered confidence in Carsome's lending model. In early 2025, JACCS, eyeing the gig-economy segment, acquired a notable minority stake. They tapped into alternative data streams, notably e-wallet transactions, to broaden their reach. Concurrently, Carsome introduced bundled insurance offerings, seamlessly integrating roadside assistance into monthly installments. This move not only alleviated buyer friction but also enriched the customer experience and elevated commission take-rates within Carsome's ecosystem.
Dominance of Unorganized Dealers and Roadside Lots
In Southeast Asia's used car market, cash-based curbside dealers are outpacing certified sellers by offering lower prices and flexible weekly payments, all without the need for formal credit checks. For instance, in Jakarta's Kemayoran market, social trust often takes precedence over digital records, bolstering the presence of these informal dealers. Meanwhile, in Thailand, stricter bank lending has shuttered many small dealerships. Those that remain are turning to repossession auctions for inventory, sidestepping refurbishment costs. Furthermore, the lack of mandatory dealer licensing means that unregulated vendors incur lower compliance costs, giving them a competitive edge over organized dealers bound by stricter regulations.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Turnover of New-Car Sales (Especially SUVs) Feeding Used Supply
- Rising Sales Through Online Channels and Digital Marketplaces
- Lack of Standardized Vehicle-Condition Reporting Protocols
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
SUVs represented 32.37% of the 2025 market share and are set to climb at a 6.63% CAGR, the fastest of any body style. The Southeast Asia used-car market for SUVs is projected to reach USD 33.1 billion in 2031, driven by residual values that remain 60-70% of the original price after 3 years. Thailand's Toyota Fortuner and Indonesia's Mitsubishi Xpander funnel high-clearance stock into certified lots, while Malaysia's Proton X70 lifts the mid-range bracket. Sedans lose share as corporate and ride-hailing fleets pivot toward crossovers. Hatchbacks and multipurpose vehicles hold niche appeal in Vietnam and the Philippines, where tight urban lanes favor compact footprints.
Trade-in cycles average 3-5 years for SUVs, compared with 5-7 years for sedans, which injects late-model units that qualify for warranty extensions. New launches such as the BYD Atto 3 will seed the pipeline by 2028, when early adopters re-enter the Southeast Asian used-car market. Certified programs cherry-pick SUVs because reconditioning costs are spread over higher resale values.
Gasoline cars still accounted for 73.36% of the 2025 market share, yet electric vehicles will grow at a 6.71% CAGR through 2031. Malaysia's battery passport rule reduces buyer discounting of used EVs from the historical 30-40% to 20% by providing state-of-health scores.
Starting from a modest base of under 150 units sold in 2020, electric vehicle (EV) sales have experienced a notable uptick, especially in the first half of 2025. By the second quarter of 2025, quarterly sales had climbed to around 22,000 units; most of these units will enter the Southeast Asian used-car market after 2028. Diesel's relevance slides as Bangkok and Jakarta introduce low-emission zones. Vietnam's 2026 tax incentive, pricing hybrids at 70% of the internal-combustion duty, will spur hybrid adoption and expand future supply.
In 2025, the 4-to-6-year age band commanded a dominant 38.72% share. However, it now grapples with pricing pressures. Since 2015, Thailand's used-vehicle index has plummeted by over 30 points, diminishing residual values. On the other hand, the 0-to-3-year segment is on a rapid ascent, boasting a projected CAGR of 6.78%. This growth is bolstered by early SUV upgrades and residual-value guarantees, which promote swifter replacement cycles.
Meanwhile, in both Vietnam and Thailand, imports over a decade old face stringent policy challenges. This has nudged buyers towards younger, certified vehicles, further solidifying the trend towards organized channels in Southeast Asia's used-car arena.
Complete Report Scope:
- By Vehicle Type
- Hatchback
- Sedan
- Sport-Utility Vehicle (SUV)
- Multi-Purpose Vehicle (MPV)
- By Fuel Type
- Gasoline
- Diesel
- Electric
- Alternative Fuels (LPG/CNG/Hybrid)
- By Vehicle Age
- 0 to 3 Years
- 4 to 6 Years
- 7 to 10 Years
- More than 10 Years
- By Mileage
- Less than 30 000 km
- 30 001 to 60 000 km
- 60 001 to 100 000 km
- More than 100 000 km
- By Sales Channel
- Online
- Offline
- By Vendor Type
- Organized
- Unorganized
- By Purchase Method
- Outright Purchase
- Financed Purchase
- Captive Financing
- Bank Financing
- Non-Banking Financial Companies (NBFC)
- By Country
- Indonesia
- Thailand
- Vietnam
- Malaysia
- Philippines
- Singapore
- Other Countries (Cambodia, Laos, Myanmar, Brunei)
List of Companies Covered in this Report:
- Carro
- Carsome
- Cars24 Services Pvt Ltd
- Carousell
- OLX
- iCar Asia (Carlist.my)
- myTukar
- BeliMobilGue.co.id
- Carmudi
- Oto.com
- Automart PH
- Mercedes-Benz Certified
- Toyota U Trust
- Honda Certified Pre-Owned
- BMW Premium Selection
- Nissan Intelligent Choice
- Hyundai Promise
- Mitsubishi Diamond Certified
- Isuzu Used Car Program
- LausAutoGroup (Carmix)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in Organized Dealership Networks and Certified-Pre-Owned Programs
- 4.2.2 Availability of Integrated Financing and Insurance Solutions
- 4.2.3 Increasing Turnover of New-Car Sales (Especially SUVs) Feeding Used Supply
- 4.2.4 Rising Sales Through Online Channels and Digital Marketplaces
- 4.2.5 Government Circular-Economy and Scrappage Incentives Accelerating Trade-Ins
- 4.2.6 AI-Driven Inspection/Pricing Platforms Boosting Buyer Trust
- 4.3 Market Restraints
- 4.3.1 Dominance of Unorganized Dealers and Roadside Lots
- 4.3.2 Lack of Standardized Vehicle-Condition Reporting Protocols
- 4.3.3 Emerging Import Restrictions on Older Used Vehicles
- 4.3.4 Reduced Private-Car Ownership in Urban Areas Due to Mobility-As-A-Service
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Vehicle Type
- 5.1.1 Hatchback
- 5.1.2 Sedan
- 5.1.3 Sport-Utility Vehicle (SUV)
- 5.1.4 Multi-Purpose Vehicle (MPV)
- 5.2 By Fuel Type
- 5.2.1 Gasoline
- 5.2.2 Diesel
- 5.2.3 Electric
- 5.2.4 Alternative Fuels (LPG/CNG/Hybrid)
- 5.3 By Vehicle Age
- 5.3.1 0 to 3 Years
- 5.3.2 4 to 6 Years
- 5.3.3 7 to 10 Years
- 5.3.4 More than 10 Years
- 5.4 By Mileage
- 5.4.1 Less than 30 000 km
- 5.4.2 30 001 to 60 000 km
- 5.4.3 60 001 to 100 000 km
- 5.4.4 More than 100 000 km
- 5.5 By Sales Channel
- 5.5.1 Online
- 5.5.2 Offline
- 5.6 By Vendor Type
- 5.6.1 Organized
- 5.6.2 Unorganized
- 5.7 By Purchase Method
- 5.7.1 Outright Purchase
- 5.7.2 Financed Purchase
- 5.7.3 Captive Financing
- 5.7.4 Bank Financing
- 5.7.5 Non-Banking Financial Companies (NBFC)
- 5.8 By Country
- 5.8.1 Indonesia
- 5.8.2 Thailand
- 5.8.3 Vietnam
- 5.8.4 Malaysia
- 5.8.5 Philippines
- 5.8.6 Singapore
- 5.8.7 Other Countries (Cambodia, Laos, Myanmar, Brunei)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Carro
- 6.4.2 Carsome
- 6.4.3 Cars24 Services Pvt Ltd
- 6.4.4 Carousell
- 6.4.5 OLX
- 6.4.6 iCar Asia (Carlist.my)
- 6.4.7 myTukar
- 6.4.8 BeliMobilGue.co.id
- 6.4.9 Carmudi
- 6.4.10 Oto.com
- 6.4.11 Automart PH
- 6.4.12 Mercedes-Benz Certified
- 6.4.13 Toyota U Trust
- 6.4.14 Honda Certified Pre-Owned
- 6.4.15 BMW Premium Selection
- 6.4.16 Nissan Intelligent Choice
- 6.4.17 Hyundai Promise
- 6.4.18 Mitsubishi Diamond Certified
- 6.4.19 Isuzu Used Car Program
- 6.4.20 LausAutoGroup (Carmix)
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment