

|
시장보고서
상품코드
2124764
인도네시아의 윤활유 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Indonesia Lubricants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
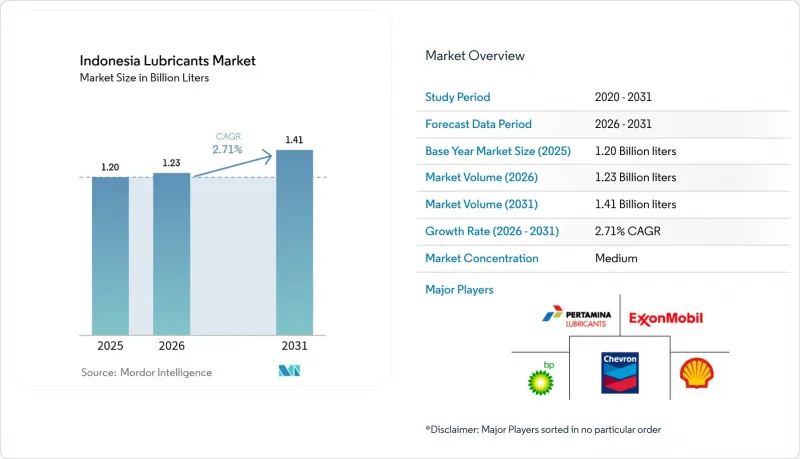
에 의하면, 인도네시아의 윤활유 시장 규모는 2025년에 12억 리터로 평가되어 2026년 12억 3,000만 리터에서 2031년까지 14억 1,000만 리터에 달할 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 2.71%를 기록할 전망입니다.
본 보고서는 제품 유형(자동차용 엔진 오일, 산업용 엔진 오일, 변속기 오일, 기어 오일, 브레이크 오일,작동유, 그리스 등), 최종 사용자 산업(자동차, 선박, 항공우주, 중장비, 산업용), 베이스스톡 유형(광물유계, 합성계, 반합성계, 바이오계)별로 분류되어 있습니다. 시장 예측은 판매량(리터) 기준으로 제시되어 있습니다.
인도네시아의 윤활유 시장 동향 및 인사이트
자동차 보유 대수의 확대
인도네시아 자동차 부문의 확대는 승용차 증가와 인도네시아 전역의 물류 네트워크 내 상용차 차량단의 현대화를 통해 윤활유 소비를 견인하고 있습니다. 국제자동차산업협회(OICA)에 따르면, 2024년 인도네시아에서는 119만 대의 자동차가 생산되었습니다. 자동 변속기가 장착된 오토바이로의 전환으로 인해, 자동 변속기 차량용 특수 윤활유 배합에 대한 수요가 발생하고 있습니다. 전자상거래의 확대와 라스트 마일 배송의 보급으로 차량 이용률이 향상되어, 기존의 소비 패턴을 넘어 윤활유 교체 빈도가 높아지고 있습니다. 정부의 전기차 추진과 2040년까지 내연기관의 단계적 폐지 계획은 자동차용 윤활유 판매량 성장에 구조적인 상한선을 가져오고 있습니다. 지역 유통 네트워크는 인도네시아의 외딴 섬에 효율적인 서비스를 제공하는 데 어려움을 겪고 있으며, 신흥 자동차 산업 클러스터에서 시장 침투를 제한하는 공급 병목 현상이 발생하고 있습니다.
산업 및 제조업의 급속한 성장
인도네시아 제조업의 성장세는 금속 가공, 발전, 중장비 용도에서의 산업용 윤활유 소비 증가로 직접 이어지고 있습니다. 세계 최대의 니켈 생산국이라는 인도네시아의 위상은 제련 공정에서 특수 금속 가공액 및 유압 시스템용 윤활유에 대한 수요를 더욱 높이고 있습니다. 제조업에 대한 투자는 새로운 산업 생산 능력을 창출하며, 초기 윤활유 충전 및 지속적인 유지보수 프로그램을 필요로 합니다. 2024년 6월에 도입된 엑슨모빌의 ‘MACHINEXT’ 현장 윤활 관리 기술은 디지털 최적화를 통해 총 소유 비용을 절감하는 동시에 설비의 수명을 연장하는 방안을 제시하고 있습니다. 자바 섬에 제조업이 집중되면서 물류상의 이점이 발생하는 반면, 인프라 개발이 산업 투자를 따라가지 못하고 있는 자원이 풍부한 외곽 지역의 성장 가능성은 제한되고 있습니다.
거시경제 및 원자재 가격 변동이 설비 가동률을 끌어내리고 있습니다.
인도네시아의 윤활유 업계는 거시경제의 불확실성과 원자재 가격 변동으로 인해 산업 활동과 소비자 지출 패턴이 위축되면서 설비 가동률 문제에 직면해 있습니다. 국내 업계의 설비 가동률은 약 60% 수준을 유지하고 있습니다. 세계 공급망의 혼란과 환율 변동이 기유 수입 비용에 영향을 미치고 있어, 제조업체들은 가격 전략을 조정할 수밖에 없으며 수요 탄력성에 미치는 영향도 고려해야 합니다. 팜유나 광업 등 수출 의존도가 높은 부문에서는 경기 순환에 따른 침체가 나타나며, 상품 가격이 하락하는 시기에는 산업용 윤활유 소비량이 감소합니다. 생산 능력이 자바 섬에 집중되어 있어 지역 간 불균형이 발생하고 있으며, 경제가 불안정한 시기에는 외곽 섬에서의 사업 운영에 있어 공급망의 신뢰성 확보가 과제로 대두되고 있습니다. 또한, SNI 규격 준수 의무에 따른 규제 준수 비용은 이익률 압박이 지속되는 시기에 소규모 사업자에게는 쉽게 감당하기 어려운 운영상의 부담이 되고 있습니다.
부문 분석
자동차 엔진 오일은 2025년 인도네시아의 윤활유 시장 점유율의 35.80%를 차지하고 있으며, 이는 인도네시아의 자동차 중심 윤활유 소비 패턴과 승용차 및 상용차 양 부문에서 내연기관의 우위를 반영하고 있습니다. 유압작동유는 고성능 유압 시스템이 필요한 인프라 건설 및 광산기계의 확대에 힘입어 2026-2031년 연평균 성장률(CAGR) 3.51%를 기록하며 가장 빠르게 성장하는 제품 카테고리가 되고 있습니다. 산업용 엔진 오일은 발전 및 선박 용도로 사용되는 반면, 변속기 오일은 이륜차 업계에서 자동 변속기의 보급 확대에 힘입어 성장하고 있습니다. 기어 오일은 특히 칼리만탄과 술라웨시 지역의 광업 운영을 중심으로 인도네시아의 중장비 및 산업기계 기반을 뒷받침하고 있습니다.
고무 가공유 및 화이트 오일을 포함한 공정 오일은 인도네시아의 타이어 제조 및 석유화학 산업에 이용되고 있는 반면, 금속 가공유는 인도네시아의 확대되는 제조업을 뒷받침하고 있습니다. 터빈 오일과 변압기유은 발전 인프라에 공급되며, 그리스는 자동차 섀시 윤활에서 산업용 베어링 시스템에 이르기까지 다양한 용도로 활용되고 있습니다. 제품 구성이 특수한 배합으로 진화하고 있는 것은 인도네시아 산업의 고도화가 진행되고 있다는 점, 그리고 API, JASO, ACEA 등의 국제 규격을 충족하는 고성능 윤활유를 요구하는 OEM 사양의 영향력이 커지고 있음을 반영하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
제8장 CEO을 위한 중요 전략적 과제
LSH 26.09.14According to Mordor Intelligence, the indonesian lubricants market size was valued at 1.20 billion liters in 2025 and estimated to grow from 1.23 billion liters in 2026 to reach 1.41 billion liters by 2031, at a CAGR of 2.71% during the forecast period (2026-2031).
This report is Segmented by Product Type (Automotive Engine Oil, Industrial Engine Oil, Transmission Fluids, Gear Oil, Brake Fluids, Hydraulic Fluids, Greases, and More), End-User Industry (Automotive, Marine, Aerospace, Heavy Equipment, and Industrial), and Base Stock Type (Mineral Oil-Based, Synthetic, Semi-Synthetic, and Bio-Based). The Market Forecasts are Provided in Terms of Volume (Liters).
Indonesia Lubricants Market Trends and Insights
Growing Automotive Parc Expansion
Indonesia's expanding automotive sector drives lubricant consumption through both passenger vehicle growth and commercial fleet modernization across the archipelago's logistics networks. According to the International Organization of Motor Vehicle Manufacturers (OICA), the country produced 1.19 million vehicles in 2024. The shift toward automatic transmission motorcycles creates demand for specialized lubricant formulations for matic applications. E-commerce expansion and the proliferation of last-mile delivery increase vehicle utilization rates, leading to a higher frequency of lubricant replacement beyond traditional consumer patterns. The government's push for electric vehicles and its planned phase-out of internal combustion engines by 2040 creates a structural ceiling for growth in automotive lubricant volumes. Regional distribution networks struggle to efficiently serve Indonesia's outer islands, creating supply bottlenecks that limit market penetration in emerging automotive clusters.
Rapid Industrial and Manufacturing Growth
Indonesia's manufacturing sector momentum directly translates to heightened industrial lubricant consumption across metalworking, power generation, and heavy equipment applications. The country's position as the world's largest nickel producer amplifies demand for specialized metalworking fluids and hydraulic systems lubricants in smelting operations. Manufacturing investment creates new industrial capacity requiring initial lubricant fills and ongoing maintenance programs. ExxonMobil's MACHINEXT on-site lubrication management technology, launched in June 2024, demonstrates how digital optimization reduces the total cost of ownership while extending equipment life cycles. The concentration of manufacturing on Java Island creates logistical advantages but limits growth potential in resource-rich outer regions where infrastructure development lags behind industrial investment.
Macroeconomic and Commodity-Price Volatility Dampening Cap-Utilization
Indonesia's lubricant industry faces capacity utilization challenges due to macroeconomic uncertainty and fluctuations in commodity prices, which dampen industrial activity and consumer spending patterns. The domestic industry operates at approximately 60% capacity utilization. Global supply chain disruptions and currency volatility impact base oil import costs, forcing manufacturers to adjust their pricing strategies and consider the effect on demand elasticity. Export-dependent sectors, such as palm oil and mining, experience cyclical downturns that reduce industrial lubricant consumption during commodity price slumps. The concentration of manufacturing capacity on Java island creates regional imbalances, while outer island operations struggle with supply chain reliability during economic turbulence. Regulatory compliance costs under mandatory SNI standards add operational overhead that smaller players cannot easily absorb during periods of margin compression.
Other drivers and restraints analyzed in the detailed report include:
- Nation-wide Infrastructure and Mining Activity Boom
- Marine and Fisheries Fleet Modernization
- Longer Drain-Interval Synthetic Formulations Lowering Volume/Vehicle
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Automotive engine oil commands 35.80% Indonesia's lubricant market share in 2025, reflecting Indonesia's vehicle-centric lubricant consumption patterns and the dominance of internal combustion engines across passenger and commercial segments. Hydraulic fluids represent the fastest-growing product category, with a 3.51% CAGR for 2026-2031, driven by infrastructure construction and the expansion of mining equipment, which require high-performance hydraulic systems. Industrial engine oil serves power generation and marine applications, while transmission fluids benefit from the automatic transmission boom in the motorcycle industry. Gear oils support Indonesia's heavy equipment and industrial machinery base, particularly in mining operations across Kalimantan and Sulawesi.
Process oils, including rubber process oil and white oil, serve the tire manufacturing and petrochemical industries in Indonesia, while metalworking fluids support the country's expanding manufacturing sector. Turbine oils and transformer oils cater to the power generation infrastructure, while greases serve a diverse range of applications, from automotive chassis lubrication to industrial bearing systems. The evolution of the product mix toward specialized formulations reflects Indonesia's increasing industrial sophistication and the growing influence of OEM specifications, which demand performance lubricants that meet international standards, such as API, JASO, and ACEA certifications.
Complete Report Scope:
- By Product Type
- Automotive Engine Oil
- Industrial Engine Oil
- Transmission Fluids
- Gear Oil
- Brake Fluids
- Hydraulic Fluids
- Greases
- Process Oil (Including Rubber Process Oil and White Oil)
- Metalworking Fluids
- Turbine Oil
- Transformer Oil
- Other Product Types
- By End-user Industry
- Automotive
- Passenger Vehicles
- Commercial Vehicles
- Two-Wheelers
- Marine
- Aerospace
- Heavy Equipment
- Construction
- Mining
- Agriculture
- Industrial
- Power Generation
- Metallurgy and Metalworking
- Textiles
- Oil and Gas
- Other End-Use Industries
- Automotive
- By Base Stock Type
- Mineral Oil-Based Lubricants
- Synthetic Lubricants
- Semi-Synthetic Lubricants
- Bio-Based Lubricants
List of Companies Covered in this Report:
- BP Plc (Castrol)
- Chevron Corporation
- Exxon Mobil Corporation
- FUCHS
- Gulf Oil International Ltd
- Idemitsu Kosan Co., Ltd.
- PETRONAS Lubricants International
- PT Pertamina Lubricants
- PT Wiraswasta Gemilang Indonesia
- Shell plc
- The Lubrizol Corporation
- TOP 1 Oil Products Company
- TotalEnergies
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing automotive parc expansion
- 4.2.2 Rapid industrial and manufacturing growth
- 4.2.3 Nation-wide infrastructure and mining activity boom
- 4.2.4 Marine and fisheries fleet modernization
- 4.2.5 Biodiesel-linked lubricant contamination driving premium additives
- 4.3 Market Restraints
- 4.3.1 Macroeconomic and commodity-price volatility dampening cap-utilization
- 4.3.2 Longer drain-interval synthetic formulations lowering volume/vehicle
- 4.3.3 Crude-oil price swings squeezing margins and price-sensitive buyers
- 4.4 Value Chain Analysis
- 4.5 Regulatory Framework
- 4.6 End-User Trends
- 4.6.1 Automotive Industry
- 4.6.2 Manufacturing Industry
- 4.6.3 Power Generation Industry
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Automotive Engine Oil
- 5.1.2 Industrial Engine Oil
- 5.1.3 Transmission Fluids
- 5.1.4 Gear Oil
- 5.1.5 Brake Fluids
- 5.1.6 Hydraulic Fluids
- 5.1.7 Greases
- 5.1.8 Process Oil (Including Rubber Process Oil and White Oil)
- 5.1.9 Metalworking Fluids
- 5.1.10 Turbine Oil
- 5.1.11 Transformer Oil
- 5.1.12 Other Product Types
- 5.2 By End-user Industry
- 5.2.1 Automotive
- 5.2.1.1 Passenger Vehicles
- 5.2.1.2 Commercial Vehicles
- 5.2.1.3 Two-Wheelers
- 5.2.2 Marine
- 5.2.3 Aerospace
- 5.2.4 Heavy Equipment
- 5.2.4.1 Construction
- 5.2.4.2 Mining
- 5.2.4.3 Agriculture
- 5.2.5 Industrial
- 5.2.5.1 Power Generation
- 5.2.5.2 Metallurgy and Metalworking
- 5.2.5.3 Textiles
- 5.2.5.4 Oil and Gas
- 5.2.5.5 Other End-Use Industries
- 5.2.1 Automotive
- 5.3 By Base Stock Type
- 5.3.1 Mineral Oil-Based Lubricants
- 5.3.2 Synthetic Lubricants
- 5.3.3 Semi-Synthetic Lubricants
- 5.3.4 Bio-Based Lubricants
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 BP Plc (Castrol)
- 6.4.2 Chevron Corporation
- 6.4.3 Exxon Mobil Corporation
- 6.4.4 FUCHS
- 6.4.5 Gulf Oil International Ltd
- 6.4.6 Idemitsu Kosan Co., Ltd.
- 6.4.7 PETRONAS Lubricants International
- 6.4.8 PT Pertamina Lubricants
- 6.4.9 PT Wiraswasta Gemilang Indonesia
- 6.4.10 Shell plc
- 6.4.11 The Lubrizol Corporation
- 6.4.12 TOP 1 Oil Products Company
- 6.4.13 TotalEnergies
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


