

|
시장보고서
상품코드
2124771
아프리카의 윤활유 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Africa Lubricants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
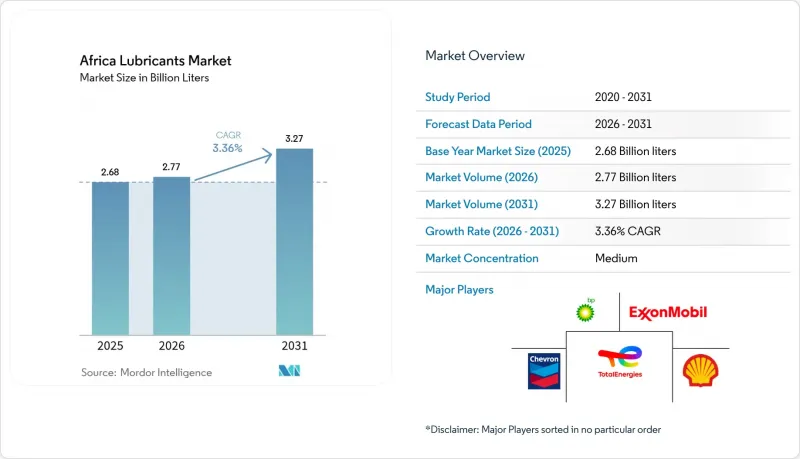
에 의하면, 아프리카의 윤활유 시장 규모는 2025년 26억 8,000만 리터로 평가되었고, 2026년에는 27억 7,000만 리터로 추정되고, 2026-2031년 CAGR 3.36%로 성장을 지속할 전망이며, 2031년에는 32억 7,000만 리터에 이를 것으로 예측됩니다.
본 보고서는 제품 유형별(자동차 엔진 오일, 산업용 엔진 오일 등), 최종 사용자 산업별(자동차, 선박, 항공우주, 중장비, 산업), 기유 유형별(광물유계, 합성계, 반합성계, 바이오), 지역별(나이지리아, 남아프리카공화국, 이집트, 알제리, 모로코 및 기타 아프리카 국가)로 분류되어 있습니다. 시장 전망은 수량(리터) 기준으로 제시되어 있습니다.
아프리카의 윤활유 시장 동향 및 인사이트
급속한 자동차 보급이 자동차용 윤활유 수요를 견인
주요 도시 지역에서는 인구 증가율을 웃도는 속도로 자동차 보유 대수가 증가하고 있어, 엔진 오일, 변속기 오일, 브레이크 오일에 대한 안정적인 수요를 창출하고 있습니다. 라고스와 요하네스버그의 상업용 트럭 차량은 가혹한 운행 주기에 노출되어 있어, 이로 인해 오일 교환 주기가 단축되고 소비량이 증가하고 있습니다. 북아프리카 전역의 자동차 조립 공장에서는 현재 공장 충전 용량의 확보와 애프터마켓에서의 안정적인 공급이 요구되고 있으며, 현지 조달 규제로 인해 국내 블렌딩이 촉진되고 있습니다. 현대식 엔진이 보급됨에 따라 운전자들은 모노그레이드 제품에서 멀티그레이드 제품으로 점차 전환하고 있으며, 소용량 패키지를 선호하는 경향은 개인 자동차 소유자의 구매력과 부합합니다. OEM 서비스 네트워크는 유로 5 배기가스 규제를 충족하는 인증 제품을 권장하고 있으며, 이에 따라 Mid-SAP(합성 첨가제 수준)의 합성 블렌드 제품의 보급이 가속화되고 있습니다.
인프라 주도형 광업 및 건설 붐
남아프리카, 잠비아, 모로코에서는 구리, 인산염, 중요 광물 프로젝트가 확대되고 있으며, 각 프로젝트에서는 분진 및 높은 부하를 견딜 수 있는 고품질 작동유와 EP 기어 오일이 필요한 대형 기계식 로더와 컨베이어가 사용되고 있습니다. 이집트와 나이지리아 전역에서 동시에 진행되고 있는 도로, 항만, 철도 개보수 공사로 인해 대형 토목 기계 및 발전 세트에 사용되는 그리스와 터빈 오일에 대한 수요가 유지되고 있습니다. 원격지에 대량 공급이 가능한 공급업체가 계약을 수주하는 한편, 유질 분석 및 상태 모니터링 서비스를 제공하는 공급업체는 제품 인수를 확약하는 장기적인 거래 관계를 구축하고 있습니다. 건설 컨소시엄의 예측 가능한 가동 일정에 따라, 승용차 수요가 계절적으로 감소하는 시기에도 블렌더의 가동률을 안정적으로 유지할 수 있는 기반이 되는 수주가 확보되고 있습니다.
연료 보조금의 변동이 가격을 왜곡
보조금의 갑작스러운 폐지나 부활은 소매 가격을 변동시키고, 운송업체가 주행 거리나 유지보수 예산을 재검토하게 함으로써 간접적으로 윤활유 수요에 영향을 미칩니다. 비용의 급격한 상승으로 인해 사업자는 오일 교환 주기를 연장하거나 더 저렴한 단급 오일로 전환하게 되어, 프리미엄 부문의 판매량이 감소합니다. 환율과 보조금 수준이 동시에 변동하면 수입업체는 입항 비용 예측에 어려움을 겪게 되며, 재고 관리 판단이 복잡해집니다. 정책의 불확실성으로 인해 블렌딩 플랜트나 저장 시설에 대한 대규모 설비 투자가 주저되면서, 위탁 블렌딩이나 제3자 물류에 대한 의존이 장기화되고 있습니다.
부문 분석
2025년, 아프리카 윤활유 시장 점유율의 36.05%를 자동차 엔진 오일이 차지했습니다. 이는 어려운 운영 조건 속에서 노후화가 진행되고 있는 대륙 전체의 차량 군에 힘입은 결과입니다. 상용 트럭은 오일 탱크 용량의 상당 부분을 차지했으며, 빈번한 오일 교환으로 인해 연간 총 소비량이 증가하고 있습니다. 고무, 섬유, 석유화학 플랜트용 공정 오일은 이집트와 나이지리아의 산업 다각화 프로그램 덕분에 전체 제품 라인 중 가장 높은 연평균 성장률(CAGR) 4.25%를 나타낼 것으로 예측됩니다. 기어 오일은 극심한 충격 하중에서 작동하는 지하 채굴 기계에 공급되고 있는 반면, 상용 차량에서 자동 변속기의 보급이 확대됨에 따라 변속기 오일의 중요성이 높아지고 있습니다. 작동유에 대해서는 서아프리카 및 북아프리카 전역의 대규모 건설 현장에서 가동되는 백호 및 크레인으로부터 안정적인 수요가 예상됩니다. 금속 가공유는 국내 부품 제조의 발전, 특히 모로코에 최근 설립된 브레이크 패드 및 필터 공장의 동향과 연동되어 있습니다.
그리스 수요는 노천 광산 및 선박용 스러스터 분야에서 증가하고 있으며, 내수성이 뛰어난 리튬 복합 제품이 선호되고 있습니다. 브레이크 오일은 신차 생산 대수에 연동되어 직선적인 성장을 보이고 있으나, 전기차로의 전환이 장기적인 확대를 억제할 가능성이 있습니다. 터빈 오일은 각국의 전력화 계획에 따라 가동을 시작한 복합 사이클 가스 발전소에서 확고한 입지를 다지고 있으며, 변압기유은 급속한 도시화가 진행되는 지역에 전력을 공급하기 위한 송전망 강화 프로젝트의 혜택을 받고 있습니다. 전반적으로 이러한 다각화된 제품 라인업이 아프리카 윤활유 시장의 회복력을 뒷받침하고 있으며, 특정 최종 용도 분야의 경기 순환적 침체를 다른 분야의 성장세로 상쇄하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
제8장 CEO가 생각해야 할 중요 전략적 과제
AJY 26.09.15According to Mordor Intelligence, the Africa lubricants market size is expected to grow from 2.68 billion liters in 2025 to 2.77 billion liters in 2026 and is forecast to reach 3.27 billion liters by 2031 at 3.36% CAGR over 2026-2031.
This report is Segmented by Product Type (Automotive Engine Oil, Industrial Engine Oil, and More), End-User Industry (Automotive, Marine, Aerospace, Heavy Equipment, and Industrial), Base Stock Type (Mineral Oil-Based, Synthetic, Semi-Synthetic, and Bio-Based), and Geography (Nigeria, South Africa, Egypt, Algeria, Morocco, and Rest of Africa). The Market Forecasts are Provided in Terms of Volume (Liters).
Africa Lubricants Market Trends and Insights
Rapid Motorization Driving Automotive Lubricant Demand
Vehicle ownership is rising faster than population growth in major urban centers, creating a steady pull for engine oils, transmission fluids, and brake fluids. Commercial truck fleets in Lagos and Johannesburg experience arduous duty cycles, which shorten oil change intervals and increase consumption. National assembly plants across North Africa now require factory-fill volumes and consistent aftermarket supply, with local content regulations encouraging in-country blending. Motorists are gradually shifting from monograde to multigrade formulations as modern engines become more prevalent, and the preference for smaller pack sizes aligns with the purchasing power of individual car owners. OEM service networks champion licensed products that meet Euro 5 emission requirements, thereby accelerating the uptake of mid-SAPs synthetic blends.
Infrastructure-Led Mining and Construction Boom
Copper, phosphate, and critical mineral projects are expanding in South Africa, Zambia, and Morocco, each utilizing heavy mechanical loaders and conveyors that require premium hydraulic fluids and EP gear oils capable of withstanding dust and high loads. Concurrent road, port, and rail upgrades across Egypt and Nigeria sustain demand for greases and turbine oils used in large earth-moving equipment and power generation sets. Suppliers able to deliver bulk volumes to remote sites win contracts, while those offering oil analysis and condition monitoring services secure long-term relationships that lock in product offtake. The predictable operating schedules of construction consortia create baseline orders that stabilize blender capacity utilization even during seasonal dips in passenger car consumption.
Persistent Fuel-Subsidy Volatility Distorting Prices
Abrupt subsidy removals or reinstatements shift pump prices and indirectly influence lubricant demand, as transporters recalibrate mileage and maintenance budgets. Sudden cost spikes prompt operators to stretch drain intervals or down-trade to cheaper monograde oils, eroding premium segment volumes. Importers struggle to forecast landed costs when exchange rates and subsidy levels change in tandem, complicating inventory decisions. Policy uncertainty discourages heavy capital investment in blending plants and storage, prolonging reliance on toll blending and third-party logistics.
Other drivers and restraints analyzed in the detailed report include:
- Local Refinery Upgrades Boosting Base-Oil Availability
- OEM Drain-Interval Extensions Favoring Synthetics
- Dominance of Low-Grade Group I Imports
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Automotive engine oil held 36.05% of Africa's lubricants market share in 2025, supported by a continent-wide vehicle fleet that continues to age under challenging operating conditions. Commercial trucks account for a sizable portion of sump volumes, and frequent oil changes increase the total liters consumed each year. Process oils, serving rubber, textile, and petrochemical plants, are forecast to grow at a 4.25% CAGR, the fastest among all product lines, thanks to industrial diversification programs in Egypt and Nigeria. Gear oils cater to underground mining machines that operate under extreme shock loads, while transmission fluids gain prominence as automatic gearboxes become more prevalent in commercial fleets. Hydraulic fluids experience steady demand from backhoes and cranes operating on large construction sites throughout West and North Africa. Metalworking fluids track the evolution of domestic component manufacturing, particularly the brake pad and filter plants that have recently been established in Morocco.
Demand for greases is rising in surface mining and marine thrusters, with lithium-complex products preferred for their water resistance. Brake fluids show linear growth in line with new vehicle assemblies, though the shift toward electric cars may curb long-term expansion. Turbine oils secure slots in combined-cycle gas plants commissioned under national electrification agendas, and transformer oils benefit from grid reinforcement projects feeding rapidly urbanizing regions. Collectively, the diversified product slate anchors the resilience of the Africa lubricants market, balancing cyclical softness in any single end-use with momentum in others.
Complete Report Scope:
- By Product Type
- Automotive Engine Oil
- Industrial Engine Oil
- Transmission Fluids
- Gear Oil
- Brake Fluids
- Hydraulic Fluids
- Greases
- Process Oil (Including Rubber Process Oil and White Oil)
- Metalworking Fluids
- Turbine Oil
- Transformer Oil
- Other Product Types
- By End-user Industry
- Automotive
- Passenger Vehicles
- Commercial Vehicles
- Two-Wheelers
- Marine
- Aerospace
- Heavy Equipment
- Construction
- Mining
- Agriculture
- Industrial
- Power Generation
- Metallurgy and Metalworking
- Textiles
- Oil and Gas
- Other End-Use Industries
- Automotive
- By Base Stock Type
- Mineral Oil-Based Lubricants
- Synthetic Lubricants
- Semi-Synthetic Lubricants
- Bio-Based Lubricants
- By Geography
- Nigeria
- South Africa
- Egypt
- Algeria
- Morocco
- Rest of Africa
List of Companies Covered in this Report:
- Ardova Plc
- BP plc
- Chevron Corporation
- CONOIL GROUP PTY LTD.
- Engen Petroleum (PTY) LTD
- Exxon Mobil Corporation
- FUCHS
- Misr Petroleum
- MRS OIL NIGERIA PLC
- Oando PLC
- Sasol
- Shell plc
- TotalEnergies
- Vivo Energy Holding B.V.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid motorisation driving automotive lubricant demand
- 4.2.2 Infrastructure-led mining and construction boom
- 4.2.3 Local refinery upgrades boosting base-oil availability
- 4.2.4 OEM drain-interval extensions favouring synthetics
- 4.2.5 Fast-growing e-commerce fleet requiring high-performance fluids
- 4.3 Market Restraints
- 4.3.1 Persistent fuel-subsidy volatility distorting prices
- 4.3.2 Dominance of low-grade Group I imports
- 4.3.3 Informal counterfeit-oil networks eroding brand value
- 4.4 Value Chain Analysis
- 4.5 Regulatory Framework
- 4.6 End-User Trends
- 4.6.1 Automotive Industry
- 4.6.2 Manufacturing Industry
- 4.6.3 Power Generation Industry
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Automotive Engine Oil
- 5.1.2 Industrial Engine Oil
- 5.1.3 Transmission Fluids
- 5.1.4 Gear Oil
- 5.1.5 Brake Fluids
- 5.1.6 Hydraulic Fluids
- 5.1.7 Greases
- 5.1.8 Process Oil (Including Rubber Process Oil and White Oil)
- 5.1.9 Metalworking Fluids
- 5.1.10 Turbine Oil
- 5.1.11 Transformer Oil
- 5.1.12 Other Product Types
- 5.2 By End-user Industry
- 5.2.1 Automotive
- 5.2.1.1 Passenger Vehicles
- 5.2.1.2 Commercial Vehicles
- 5.2.1.3 Two-Wheelers
- 5.2.2 Marine
- 5.2.3 Aerospace
- 5.2.4 Heavy Equipment
- 5.2.4.1 Construction
- 5.2.4.2 Mining
- 5.2.4.3 Agriculture
- 5.2.5 Industrial
- 5.2.5.1 Power Generation
- 5.2.5.2 Metallurgy and Metalworking
- 5.2.5.3 Textiles
- 5.2.5.4 Oil and Gas
- 5.2.5.5 Other End-Use Industries
- 5.2.1 Automotive
- 5.3 By Base Stock Type
- 5.3.1 Mineral Oil-Based Lubricants
- 5.3.2 Synthetic Lubricants
- 5.3.3 Semi-Synthetic Lubricants
- 5.3.4 Bio-Based Lubricants
- 5.4 By Geography
- 5.4.1 Nigeria
- 5.4.2 South Africa
- 5.4.3 Egypt
- 5.4.4 Algeria
- 5.4.5 Morocco
- 5.4.6 Rest of Africa
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Ardova Plc
- 6.4.2 BP plc
- 6.4.3 Chevron Corporation
- 6.4.4 CONOIL GROUP PTY LTD.
- 6.4.5 Engen Petroleum (PTY) LTD
- 6.4.6 Exxon Mobil Corporation
- 6.4.7 FUCHS
- 6.4.8 Misr Petroleum
- 6.4.9 MRS OIL NIGERIA PLC
- 6.4.10 Oando PLC
- 6.4.11 Sasol
- 6.4.12 Shell plc
- 6.4.13 TotalEnergies
- 6.4.14 Vivo Energy Holding B.V.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


