|
시장보고서
상품코드
2124856
스페인의 시설 관리 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Spain Facility Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
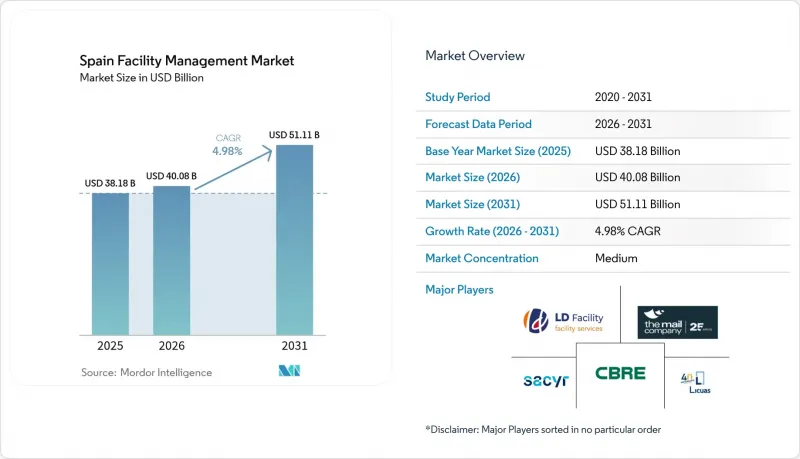
에 의하면, 스페인의 시설 관리 시장 규모는 2025년 381억 8,000만 달러에서 2026년에는 400억 8,000만 달러에 이르고, 2026-2031년 CAGR 4.98%로 성장을 지속하여 2031년에는 511억 1,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 서비스 유형(하드 서비스, 소프트 서비스), 제공 형태(사내 대응, 외부 위탁), 최종 사용자 산업(상업, 호스피탈리티, 공공 인프라, 의료, 산업·프로세스, 기타 최종 사용자 산업)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
스페인의 시설 관리 시장 동향 및 인사이트
대기업의 통합형 시설 관리(IFM) 계약으로의 전환
스페인의 기업들은 실시간 건물 분석, 통일된 서비스 수준, 그리고 ESG 규정 준수를 보장받기 위해 여러 공급업체를 단일 소스의 IFM 계약으로 통합하고 있습니다. 주목할 만한 사례로 Hotelatelier를 들 수 있습니다. 이 회사는 HVAC 최적화와 프런트 업무 서비스 조정을 통합한 모델로 전환한 후 88%의 고객 만족도 지수를 달성했습니다. 이러한 추세는 여러 거점을 보유한 오피스 포트폴리오에서 특히 두드러지지만, 병원 및 데이터센터 운영사들도 가동률 향상과 거버넌스 간소화를 위해 기술 업무와 소프트 업무를 통합하기 시작하고 있습니다. 계약 규모와 기간의 확대로 인해 공급업체의 수익 예측 가시성은 향상되지만, 엄격한 핵심 성과 지표(KPI)를 충족하기 위해서는 고도화된 디지털 플랫폼과 변경 관리 능력이 요구됩니다.
호텔 및 관광 업계의 회복
스페인에서는 2024년부터 2025년 초에 걸쳐 해외에서 방문하는 관광객 수가 급증하면서 발레아레스 제도, 카나리아 제도, 코스타 델 솔의 객실 가동률이 회복되었습니다. 각 호텔 기업은 계절적 인력 변동에 대응하기 위해 청소, 경비, 컨시어지 업무를 외주화하는 한편, 자동 체크인 등 고객 경험 향상 기술에 주력하고 있으며, Kora Living 시설에서는 그 도입률이 60%에 달할 전망입니다. ‘NextGenerationEU’ 개보수 사업과 연계된 지속가능성 목표에 따라 서비스 범위는 더욱 확대되어, 에너지 벤치마킹 및 폐기물 감축 프로그램도 포함되게 되었습니다. 여행 성수기에는 아웃소싱 수요가 정점에 달하기 때문에 유연한 계약 구조와 성과 연동형 가격 책정 메커니즘의 필요성이 더욱 높아지고 있습니다.
새로운 단체협약에 따른 인건비 상승
‘고용 및 단체 교섭에 관한 제5차 협정(V Agreement)’은 2025년 임금 4% 인상을 의무화하고 있으며, 이로 인해 스페인의 시설 관리 시장의 계약에서 가장 큰 비용 요소가 상승하게 됩니다. 수익 구성의 비중이 소프트 서비스에 치우쳐 있는 제공업체는 자동화 선택지가 제한적이기 때문에 가장 큰 영향을 받게 될 것입니다. 한편, 지역 간 임금 격차는 카탈루냐와 바스크 지방에서 이익률에 대한 압박을 더욱 가중시키고 있습니다. 이에 대응하여 각 기업은 청소 업무에 로봇 도입을 가속화하고, 서비스 수준 범위를 재검토하며, 서비스를 묶어 제공함으로써 간접비를 분산시키는 방식으로 대처하고 있습니다.
부문 분석
2025년, 스페인의 시설 관리 시장 규모의 62.94%를 하드 서비스가 차지하고 있으며, 이는 수십년전부터 사용되어 온 공조(HVAC), 전기, 방화 설비의 현대화가 시급함을 반영하고 있습니다. 소유주가 예기치 못한 가동 중단에 대처하기 위해 예측 분석을 도입함에 따라, 자산 관리 하도급 계약이 주류를 이루고 있습니다. 무르시아에 위치한 한 화학 공장에서는 에너지 관리 시스템과 유지보수 관리 시스템을 연동한 결과, 10년 동안 에너지 사용량을 50% 가까이 절감했습니다. 기술 서비스 제공업체들은 설비 투자 계획과 일상적인 운영·유지보수 업무를 결합한 다년 계약을 체결하여 수익의 안정성을 높이고 있습니다.
소프트 서비스는 하이브리드 근무와 호스피탈리티 업계의 회복을 호재로 삼아 연평균 성장률(CAGR) 5.08%로 다른 분야를 웃도는 성장이 예상됩니다. 이용 현황이 주 단위로 변동함에 따라 보안 및 사무 지원 업무는 복잡해지고 있으며, 접근 제어 통합 및 책상 예약 분석에 대한 수요가 증가하고 있습니다. 청소 계약은 임금 인플레이션에 따른 비용 상승이라는 역풍을 맞고 있지만, 실시간 방문객 수에 맞추어 근로 시간을 조정하는 센서 기반 일정 관리의 이점도 누리고 있습니다. 케이터링 사업은 사무실 복귀 추세와 관광 수요 회복에 힘입어 회복세를 보이고 있으나, 식자재 가격 급등으로 인한 메뉴 원가 압박으로 인해 동적 가격 책정 모델의 도입이 필요해지고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the Spain facility management market size is expected to grow from USD 38.18 billion in 2025 to USD 40.08 billion in 2026 and is forecast to reach USD 51.11 billion by 2031 at 4.98% CAGR over 2026-2031.
This report is Segmented by Service Type (Hard Services, Soft Services), Offering Type (In-House, Outsourced), End-User Industry (Commercial, Hospitality, Institutional and Public Infrastructure, Healthcare, Industrial and Process, Other End-User Industries). The Market Forecasts are Provided in Terms of Value (USD).
Spain Facility Management Market Trends and Insights
Shift toward integrated facility management (IFM) contracts among large enterprises
Spanish corporations are consolidating multiple vendors into single-source IFM agreements to gain real-time building analytics, unified service levels and ESG compliance assurance. A notable case is Hotelatelier, which achieved an 88% guest-satisfaction index after switching to an integrated model that merges HVAC optimization with front-of-house service orchestration. The move is strongest in multi-site office portfolios, but hospital and data-center operators are also beginning to bundle technical and soft scopes to improve uptime and simplify governance. Greater contract size and duration improve provider revenue visibility, yet require advanced digital-platform and change-management capability to meet stringent key-performance indicators.
Hospitality and tourism rebound
Spain welcomed a sharp rise in international arrivals in 2024 and early 2025, restoring room-occupancy levels in the Balearic and Canary Islands as well as the Costa del Sol. Hotels outsource cleaning, security and concierge functions to withstand seasonal labor swings and focus on guest experience technologies such as automated check-in, which reached 60% adoption at Kora Living properties. Sustainability targets linked to NextGenerationEU retrofits further widen the service scope to include energy benchmarking and waste-reduction programs. Outsourcing peaks during peak travel months, reinforcing the need for agile contract structures and performance-based pricing mechanisms.
Rising labor costs under new collective-bargaining agreements
The V Agreement for Employment and Collective Bargaining mandates wage increases of 4% for 2025, lifting the largest cost element in Spain facility management market contracts. Providers whose revenue mix tilts toward soft services face the greatest exposure because automation options are limited, while regional wage differentials intensify margin pressure in Catalonia and the Basque Country. Companies respond by accelerating robotics in cleaning, renegotiating service-level scopes and bundling services to dilute overhead.
Other drivers and restraints analyzed in the detailed report include:
- E-commerce logistics and data-center expansion
- PPP social-infrastructure projects
- Volatile energy prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hard services commanded 62.94% of Spain facility management market size in 2025, mirroring the imperative to modernize decades-old HVAC, electrical and fire-safety installations. Asset-management subcontracts dominate as owners deploy predictive analytics to counter unplanned downtime. A chemical plant in Murcia cut energy use by almost 50% over ten years after pairing energy-management and maintenance-management systems. Technical-service providers secure multiyear agreements that couple capital-expenditure planning with day-to-day operations and maintenance tasks, improving revenue stability.
Soft services are forecast to outpace at 5.08% CAGR, fueled by hybrid workplaces and hospitality recovery. Security and office-support functions gain complexity as occupancy fluctuates weekly, prompting demand for access-control integrations and desk-booking analytics. Cleaning contracts face cost headwinds from wage inflation but also benefit from sensor-driven scheduling that aligns labor hours with real-time footfall. Catering rebounds on return-to-office trends and tourism demand, although menu-cost pressure from food inflation necessitates dynamic pricing models.
Complete Report Scope:
- By Service Type
- Hard Services
- Asset Management
- MEP and HVAC Services
- Fire Systems and Safety
- Other Hard FM Services
- Soft Services
- Office Support and Security
- Cleaning Services
- Catering Services
- Other Soft FM Services
- Hard Services
- By Offering Type
- In-house
- Outsourced
- Single FM
- Bundled FM
- Integrated FM
- By End-user Industry
- Commercial (IT and Telecom, Retail and Warehouses, etc.)
- Hospitality (Hotels, Eateries, Large-scale Restaurants)
- Institutional and Public Infrastructure (Govt, Education, Transportation)
- Healthcare (Public and Private Facilities)
- Industrial and Process (Manufacturing, Energy, Mining)
- Other End-user Industries (Multi-housing, Entertainment, Sports and Leisure)
List of Companies Covered in this Report:
- ISS Global
- Ferrovial Servicios
- Acciona Facility Services SA
- Licuas SA
- CBRE
- Sacyr Facilites
- The Mail Company
- LD Facility
- Savills
- TDGI Spain
- Eulen Servicios
- Clece
- Serveo
- Valoriza Servicios
- Ilunion Facility Services
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.1.1 Current Occupancy Rates
- 4.1.2 Profitability Rates of Major FM Players
- 4.1.3 Workforce Indicators - Labor Participation
- 4.1.4 Facility Management Market Share (%), by Service Type
- 4.1.5 Facility Management Market Share (%), by Hard Services
- 4.1.6 Facility Management Market Share (%), by Soft Services
- 4.1.7 Urbanization and Population Growth in Major Metros
- 4.1.8 Sector Investment Priorities in Spain's Infrastructure Pipeline
- 4.1.9 Regulatory Drivers Specific to Labour and Safety Standards
- 4.2 Market Drivers
- 4.2.1 Shift toward integrated facility management (IFM) contracts among large enterprises
- 4.2.2 Recovery of hospitality and tourism sectors boosting demand for outsourced FM services
- 4.2.3 Expansion of e-commerce logistics and data centers requiring specialized hard FM services
- 4.2.4 Public-private partnership (PPP) social-infrastructure projects creating long-term FM pipelines
- 4.2.5 NextGenerationEU renovation-wave funding driving energy-efficient retrofits in public buildings
- 4.2.6 Flexible workspace operators demanding agile micro-contract FM models
- 4.3 Market Restraints
- 4.3.1 Rising labor costs under new collective-bargaining agreements squeezing FM margins
- 4.3.2 Volatile energy prices eroding profitability of energy-intensive hard services
- 4.3.3 Legacy building stock with poor asset documentation inflating operations and maintenance risk premiums
- 4.3.4 Chronic late-payment culture among public-sector clients stressing FM working capital
- 4.4 Value Chain Analysis
- 4.5 PESTEL Analysis
- 4.6 Regulatory and Legislative Framework for Market Entrants
- 4.7 Impact of Macroeconomic Indicators on FM Demand
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Services
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment and Funding Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Hard Services
- 5.1.1.1 Asset Management
- 5.1.1.2 MEP and HVAC Services
- 5.1.1.3 Fire Systems and Safety
- 5.1.1.4 Other Hard FM Services
- 5.1.2 Soft Services
- 5.1.2.1 Office Support and Security
- 5.1.2.2 Cleaning Services
- 5.1.2.3 Catering Services
- 5.1.2.4 Other Soft FM Services
- 5.1.1 Hard Services
- 5.2 By Offering Type
- 5.2.1 In-house
- 5.2.2 Outsourced
- 5.2.2.1 Single FM
- 5.2.2.2 Bundled FM
- 5.2.2.3 Integrated FM
- 5.3 By End-user Industry
- 5.3.1 Commercial (IT and Telecom, Retail and Warehouses, etc.)
- 5.3.2 Hospitality (Hotels, Eateries, Large-scale Restaurants)
- 5.3.3 Institutional and Public Infrastructure (Govt, Education, Transportation)
- 5.3.4 Healthcare (Public and Private Facilities)
- 5.3.5 Industrial and Process (Manufacturing, Energy, Mining)
- 5.3.6 Other End-user Industries (Multi-housing, Entertainment, Sports and Leisure)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ISS Global
- 6.4.2 Ferrovial Servicios
- 6.4.3 Acciona Facility Services SA
- 6.4.4 Licuas SA
- 6.4.5 CBRE
- 6.4.6 Sacyr Facilites
- 6.4.7 The Mail Company
- 6.4.8 LD Facility
- 6.4.9 Savills
- 6.4.10 TDGI Spain
- 6.4.11 Eulen Servicios
- 6.4.12 Clece
- 6.4.13 Serveo
- 6.4.14 Valoriza Servicios
- 6.4.15 Ilunion Facility Services
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Technology-led Integrated FM (IoT, BMS, AI-based Predictive Maintenance)
- 7.3 ESG-compliant FM Solutions Demand
- 7.4 Future Service-Model Shifts (Outcome-based Contracts)