|
시장보고서
상품코드
2125544
ASEAN의 모바일 가상 네트워크 사업자(MVNO) : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)ASEAN Mobile Virtual Network Operator (MVNO) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
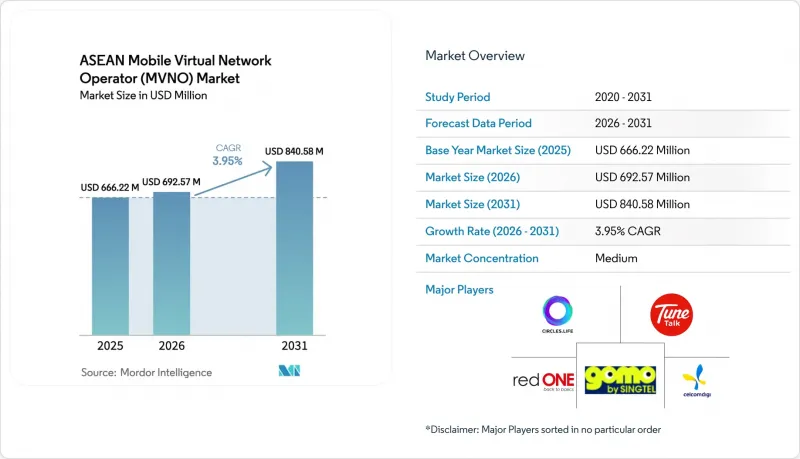
에 의하면, ASEAN의 모바일 가상 네트워크 사업자(MVNO) 시장 규모는 2025년 6억 6,622만 달러로 평가되었습니다. 2026년에는 6억 9,257만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 3.95%로 성장을 지속하여, 2031년에는 8억 4,058만 달러에 이를 것으로 예측됩니다.

본 보고서는 도입 모델(클라우드·On-Premise), 운영 모드(재판매업체 등), 가입자 유형(소비자 등), 용도(할인, 비즈니스, 셀룰러 M2M 등),네트워크 기술(2G/3G, 4G/LTE 등), 유통 채널(온라인/디지털 전용 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
ASEAN의 모바일 가상 네트워크 사업자(MVNO) 시장 동향 및 인사이트
증가하는 모바일 가입자 수와 스마트폰 보급률
2025년, 아세안(ASEAN)의 모바일 브로드밴드 회선 수는 4억 5,000만 회선을 넘어섰으며, 그중에서도 베트남이 선두를 차지하여 용량의 90% 이상을 점유하는 3대 통신사 아래 1억 470만 명의 가입자 수를 기록했습니다. 싱가포르, 말레이시아, 태국에서는 도시 지역의 스마트폰 보급률이 이미 80%를 넘어섰습니다. 그러나 인도네시아와 필리핀의 저소득층 및 농촌 지역에서는 여전히 선불 데이터 요금제에 의존하고 있어, 이는 가치 중심의 MVNO에게 성장의 여지를 제공합니다. 주요 시장 전반에서 30세 미만이 인구 중앙값을 차지하는 젊은 층의 인구 구성이 음성 통화량을 상회하는 데이터 이용을 주도하고 있기 때문에 가상 이동통신 사업자들은 대용량 데이터 요금제와 최소한의 통화 시간을 중심으로 한 요금제를 설계하고 있습니다. 과거 데이터에 따르면, 스마트폰 보급률이 1% 상승할 때마다 MVNO 가입자 수는 약 1.5포인트 증가하는 것으로 나타나, 이러한 선순환이 더욱 강화되고 있습니다. 독립형 5G의 전개에 따라 MVNO는 차별화된 저지연 서비스를 시작할 수 있지만, 4G 커버리지가 아직 불충분한 지역에서는 도입이 지연되고 있어 단기적으로는 LTE 네트워크의 역할이 유지될 전망입니다.
저가 음성·데이터 요금제에 대한 수요
인도네시아와 필리핀의 월평균 ARPU(가입자 1인당 평균 수익)가 5-8달러인 반면, 싱가포르에서는 15-20달러에 달하기 때문에 가격 경쟁이 치열합니다. 2025년에는 할인 MVNO가 현지 통화로 5-15달러 상당의 가격에 100-300GB의 선불 SIM을 판매함으로써 신규 계약의 28.71%를 확보하며, MNO의 서브 브랜드보다 낮은 가격 설정을 실현했습니다. 지역 전체에 약 1,000만 명에 달하는 이주 노동자들은 무제한 국제 통화 및 지역 내 로밍을 선호하며, 세계 브랜드들은 송금 서비스가 포함된 요금제를 통해 이러한 틈새 시장을 개척하고 있습니다. 2026년에 예정된 태국의 도매 요금 20% 인하로 인해 소매 가격 인상 여지는 넓어지겠지만, 지속적인 가격 경쟁으로 인해 가입자 투자 회수 기간이 18-24개월로 길어지면서 현금 흐름이 악화되고 있습니다. 이에 통신사들은 표면상의 가격 인상을 하지 않으면서 실질 ARPU를 높이기 위해 데이터 이월 및 로열티 혜택을 패키지로 제공합니다.
치열한 경쟁으로 인한 이익률 압박
GOMO나 Giga와 같은 MNO의 디지털 브랜드는 100-300GB 요금제를 10-18 싱가포르 달러에 제공하며, 네트워크 비용의 우위를 살리면서도 독립형 MVNO의 요금과 어깨를 나란히 하고 있습니다. 도매 요금은 MVNO 소매 수익의 최대 60%를 차지하며, 마케팅 및 지원 비용을 차감하면 매출 총이익률은 고작 15-20%에 그칩니다. 싱가포르에서는 2023년부터 2025년에 걸쳐 사용자 1인당 40-60 싱가포르 달러의 고객 확보 비용에 대해 2년의 회수 기간이 필요하기 때문에 자금 사정에 어려움을 겪는 신규 진입 사업자들이 이를 유지하지 못해 여러 사업자가 철수했습니다. 말레이시아의 듀얼 5G 네트워크에서는 공식적인 가격 감독이 도입되어 있지만, 공개된 계약서에 따르면 호스트 사업자는 여전히 요금 책정에서 주도권을 가지고 있습니다. 최소 보장 조항에 따라 이용률이 기준치를 밑돌 경우 벌금이 부과되기 때문에 가상 통신 사업자들은 계약 물량이 예측 가능한 수요와 일치하는 고부가가치 기업용 및 IoT 틈새 시장으로 사업을 전환하고 있습니다.
부문별 분석
2025년에는 클라우드 호스팅형 솔루션이 ASEAN 모바일 가상 네트워크 사업자(MVNO) 시장 점유율의 56.71%를 차지했으며, 클라우드 도입에 따른 ASEAN의 모바일 가상 네트워크 사업자(MVNO) 시장 규모는 2031년까지 연평균 성장률(CAGR) 4.58%로 확대될 것으로 전망됩니다. 초기 투자를 300만-500만 달러에서 ‘성장에 따른 종량제’ 운영비로 전환할 수 있게 됨에 따라, 많은 스타트업 기업이 BSS·OSS에 AWS, Azure 또는 Google Cloud를 채택하게 되었습니다. MyRepublic은 Tata Communications의 클라우드 스택으로 이전한 지 불과 90일 만에 서비스를 시작했으나, On-Premise 구축에는 최대 18개월이 소요됩니다. 또한, 싱글 테넌트형 클라우드 인스턴스에서는 현지화 모듈을 신속하게 통합할 수 있어 다국적 사업 확장이 간소화됩니다. 이는 아세안 전역에 걸친 성장 전략에서 매우 중요합니다. On-Premise 시스템은 여전히 56.71%의 점유율을 차지하고 있는데, 이는 Full MVNO나 규제 대상 산업이 현지 데이터 저장 및 초저지연을 선호하기 때문입니다. Circles.Life는 2024년에 클라우드 네이티브 핵심 시스템으로 전환한 후 가입자 1인당 비용을 40% 가까이 절감했으나, 이러한 효율성은 레거시 도입 환경에서는 재현하기 어렵습니다. 규제상의 미묘한 차이도 중요합니다. 인도네시아의 데이터 주권 관련 규정에서는 특정 데이터 분류를 국내에 보관하도록 의무화하고 있으므로, 과금 처리는 국내에서 수행하면서 CRM은 퍼블릭 클라우드에서 운영하는 하이브리드 클라우드가 전환 기간 동안 주류를 이룰 것입니다. 향후 2028년까지 ASEAN의 모바일 가상 네트워크 사업자(MVNO) 시장의 신규 출시 사례 중 70% 이상이 ‘클라우드 퍼스트’ 방식으로 진행될 것으로 예상되며, 이는 하드웨어 소유에서 서비스 오케스트레이션으로의 전략적 전환을 반영합니다.
경쟁상의 이점은 속도와 유연성에 있습니다. 클라우드 API는 모바일 결제, 컨텐츠 스트리밍, IoT 대시보드와 같은 부가가치 앱의 신속한 통합을 지원하며, 이를 통해 가상 통신 사업자는 분기마다가 아니라 매주 서비스 내용을 업데이트할 수 있게 됩니다. 그러나 클라우드 간 마이그레이션에는 연간 IT 지출의 20-30%에 달하는 비용이 발생할 수 있으며, 이는 민첩성 향상으로 얻는 이점의 일부를 상쇄하기 때문에 벤더 종속이 우려 사항으로 대두되고 있습니다. 통신 사업자들은 중복성을 확보하기 위해 멀티클라우드 도입을 시도하고 있지만, 소규모 팀의 경우 복잡성 증가가 이점을 상쇄할 가능성이 있습니다. 전반적으로 클라우드 도입은 비용 구조를 재정의하고, 진입 장벽을 낮추며, ASEAN의 모바일 가상 네트워크 사업자(MVNO) 시장의 경쟁을 심화시키고 있습니다.
2025년에는 리셀러 모델이 38.57%의 점유율을 차지했으나, Full MVNO 구성의 ASEAN 모바일 가상 네트워크 사업자(MVNO) 시장 규모는 2031년까지 연평균 성장률(CAGR) 4.91%로 확대될 것으로 예측됩니다. 리셀러는 통화 시간이나 데이터 통신량을 일괄 구매하여 자사 브랜드로 재판매하는 단순한 비즈니스 모델로 성공을 거두고 있으며, 이를 통해 초기 투자를 100만 달러 미만으로 억제할 수 있습니다. 하지만 라우팅, 서비스 품질, 도매 비용에 대한 관리 권한은 포기하게 됩니다. 경쟁이 치열해지는 가운데, 가상 통신 사업자들은 Full MVNO로 전환하고, HLR, 패킷 게이트웨이, 정책 엔진을 도입함으로써 이익률 회복과 서비스 차별화를 꾀하고 있습니다. Circles.Life와 StarHub의 ‘giga’는 이러한 변화를 여실히 보여주고 있으며, 두 회사 모두 QoS를 관리하고 기업용 프라이빗 APN 등의 부가가치 기능을 제공하기 위해 코어 네트워크 요소를 추가하고 있습니다. 서비스 운영자나 라이트/브랜드 MVNO는 비용과 제한된 차별화 사이의 균형을 맞추는 중간적인 대안을 제공하고 있지만, 그 성장률은 Full MVNO 분야에 미치지 못하는 상황입니다.
자금 조달은 여전히 장벽으로 남아 있습니다. 기본적인 코어 네트워크 구축에는 500만-1,000만 달러와 숙련된 엔지니어가 필요하기 때문에 많은 신규 진출기업들은 여러 고객과 인프라 비용을 분담하는 매니지드 서비스 제공업체와 제휴하고 있습니다. 규제 변화도 순풍이 되고 있습니다. 태국과 베트남에서는 개방형 도매 접근이 의무화되어 있어, Full MVNO를 목표로 하는 사업자들에게는 투자를 정당화할 수 있는 협상력이 강화되고 있습니다. 수익성의 조짐도 나타나기 시작했으며, 선행 기업들에 따르면 매출 총이익률은 재판매업자 시절의 20%에서 완전 전환 후에는 35% 가까이 상승했다고 합니다. 그 결과, ASEAN의 모바일 가상 네트워크 사업자(MVNO) 시장에서 Full MVNO의 점유율은 2029년 이후 재판매 업체를 추월할 것으로 예상되며, 업계는 더욱 심화된 수직 통합으로 나아갈 것으로 전망됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.16According to Mordor Intelligence, the ASEAN MVNO market size is expected to grow from USD 666.22 million in 2025 to USD 692.57 million in 2026 and is forecast to reach USD 840.58 million by 2031 at 3.95% CAGR over 2026-2031.
This report is Segmented by Deployment Model (Cloud and On-Premise), Operational Mode (Reseller, and More), Subscriber Type (Consumer, and More), Application (Discount, Business, Cellular M2M, and More), Network Technology (2G/3G, 4G/LTE, and More), Distribution Channel (Online/Digital-Only, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
ASEAN Mobile Virtual Network Operator (MVNO) Market Trends and Insights
Rising Mobile-Subscriber Base and Smartphone Penetration
ASEAN counted more than 450 million mobile broadband lines in 2025, led by Vietnam with 104.7 million subscriptions under three dominant networks that control over 90% of capacity. Urban smartphone penetration already tops 80 percent in Singapore, Malaysia, and Thailand, but lower-income and rural zones across Indonesia and the Philippines still rely on prepaid data packs, creating headroom for value-driven MVNOs. Youthful demographics median age below 30 across key markets propel data usage that outpaces voice traffic, so virtual operators design plans centered on large data buckets and minimal voice minutes. Historical data show every 1-percentage-point uptick in smartphone penetration adds roughly 1.5 points to MVNO subscriber growth, reinforcing the positive feedback loop. As standalone 5G rolls out, MVNOs can launch differentiated low-latency services, yet adoption lags in areas where 4G coverage remains incomplete, preserving the near-term role of LTE networks.
Demand for Low-Cost Voice and Data Plans
Average monthly ARPU ranges between USD 5 and USD 8 in Indonesia and the Philippines, compared with USD 15-20 in Singapore, so price competition is acute. Discount MVNOs captured 28.71% of applications in 2025 by marketing prepaid SIMs with 100-300 GB for the local equivalent of USD 5-15, undercutting MNO sub-brands. Migrant workers about 10 million region-wide favour unlimited international calls and regional roaming, niches that global brands exploit with bundled remittance services. Thailand's 20% wholesale-fee reduction scheduled for 2026 will widen retail price headroom, but sustained undercutting lengthens subscriber payback periods to 18-24 months, stretching cash flow. Operators therefore bundle data rollover or loyalty rewards to lift effective ARPU without headline price hikes.
Margin Squeeze from Intense Price Competition
MNO digital brands such as GOMO and Giga price 100-300 GB plans at SGD 10-18, matching independent MVNO offers while enjoying network cost advantages. Wholesale fees absorb up to 60% of MVNO retail revenue, leaving slender 15-20% gross margins after marketing and support. Singapore saw multiple shutdowns between 2023 and 2025 because acquisition costs of SGD 40-60 per user demanded two-year payback periods that cash-strapped entrants could not sustain. Malaysia's dual 5G network introduces official price oversight, yet disclosed contracts show host operators still retain rate-setting leverage. Minimum-guarantee clauses penalize under-utilization, prompting virtual operators to pivot toward higher-value enterprise and IoT niches where volume commitments align with predictable demand.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of IoT and M2M Connections
- Regulatory Push for Open Wholesale Access and eSIM-Enabled Entry
- Dependence on Host MNOs for Network Quality and Wholesale Fees
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud-hosted solutions captured 56.71% of the ASEAN MVNO market share in 2025, and the ASEAN MVNO market size for cloud deployments is forecast to expand at a 4.58% CAGR through 2031. Reduced capital outlay shift from USD 3-5 million upfront to pay-as-you-grow operating expense has convinced many start-ups to adopt AWS, Azure, or Google Cloud for BSS and OSS. MyRepublic launched in just 90 days after migrating to Tata Communications' cloud stack, whereas on-premises builds require up to 18 months. Single-tenant cloud instances also simplify multi-country expansion because localization modules plug in quickly, which is critical for pan-ASEAN growth strategies. On-premises systems still hold 56.71% share because full MVNOs and regulated verticals prefer local data custody and ultra-low latency. Circles.Life trimmed per-subscriber costs by almost 40% after shifting to a cloud-native core in 2024, an efficiency that is hard for legacy deployments to replicate. Regulatory nuances matter: Indonesia's data-sovereignty rules oblige certain data classes to reside domestically, so hybrid clouds that keep billing in-country while running CRM in public cloud will dominate the transition period. Looking ahead, over 70% of new ASEAN MVNO market launches are expected to be cloud-first by 2028, reflecting a strategic pivot from hardware ownership to service orchestration.
The competitive payoff is speed and flexibility. Cloud APIs support rapid integration of value-added apps mobile payments, content streaming, or IoT dashboards allowing virtual operators to refresh offers weekly rather than quarterly. However, vendor lock-in is emerging as a concern since migrating between clouds could cost 20-30% of annual IT spend, offsetting some agility gains. Operators are experimenting with multi-cloud for redundancy, though added complexity may outweigh benefits for smaller teams. Overall, cloud adoption is redefining cost structures and lowering entry barriers, intensifying rivalry within the ASEAN MVNO market.
Reseller models led with 38.57% share in 2025, yet the ASEAN MVNO market size for full MVNO configurations is projected to grow at a 4.91% CAGR to 2031. Resellers thrive on simplicity, purchasing bulk minutes and data, then rebranding, which keeps initial investment under USD 1 million. Still, they surrender control over routing, quality of service, and wholesale costs. As price competition intensifies, virtual operators are upgrading to full MVNO status, installing HLRs, packet gateways, and policy engines to reclaim margin and service differentiation. Circles.Life and StarHub's giga illustrate the shift, each adding core-network elements to manage QoS and launch value-added features like private APN for enterprises. Service Operator and Light/Brand MVNOs provide a middle path, balancing cost with limited differentiation, but growth rates lag the full MVNO frontier.
Capital remains the hurdle: basic core deployments need USD 5-10 million and skilled engineers, so many entrants partner with managed-service providers who amortize infrastructure across multiple clients. Regulatory changes help; Thailand and Vietnam mandate open wholesale access, giving would-be full MVNOs better bargaining power to justify investment. Profitability evidence is building early movers report gross margins rising from 20 percent as resellers to near 35 percent after full migration. Consequently, the share of full MVNOs in the ASEAN MVNO market is expected to overtake resellers after 2029, pushing the industry toward deeper vertical integration.
Complete Report Scope:
- By Deployment Model
- Cloud
- On-Premise
- By Operational Mode
- Reseller
- Service Operator
- Full MVNO
- Light, Brand MVNO
- By Subscriber Type
- Consumer
- Enterprise
- IoT-Specific
- By Application
- Discount
- Business
- Cellular M2M
- Media and Entertainment
- Retail
- Roaming
- Migrant
- Telecom Wholesale
- By Network Technology
- 2G, 3G
- 4G, LTE
- 5G
- Satellite, NTN
- By Distribution Channel
- Online, Digital-Only
- Traditional Retail Stores
- Carrier Sub-Brand Stores
- Third-Party, Wholesale
List of Companies Covered in this Report:
- TracFone Wireless, Inc.
- Tesco Mobile Limited
- Virgin Mobile (Virgin Media O2)
- Lycamobile Group
- Lebara Group B.V.
- Boost Mobile LLC
- Cricket Wireless LLC
- Giffgaff Limited
- 1&1 Drillisch AG
- PosteMobile S.p.A.
- Truphone Limited
- Kajeet, Inc.
- Ting Mobile (Dish Wireless)
- Google Fi Wireless
- Altice Mobile (Optimum Mobile)
- Asahi Net, Inc.
- FreedomPop, Inc.
- Airvoice Wireless LLC
- FRiENDi Mobile
- Voiceworks B.V.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Value-Chain Analysis
- 4.3 Market Drivers
- 4.3.1 Rising Mobile-Subscriber Base and Smartphone Penetration
- 4.3.2 Demand for Low-Cost Voice and Data Plans
- 4.3.3 Expansion of IoT, M2M Connections
- 4.3.4 Regulatory Push for Open Wholesale Access and eSIM-Enabled Entry
- 4.3.5 Fintech and Telco Convergence Spawning Bank-Branded MVNOs
- 4.3.6 Satellite-to-Cell Partnerships Enabling Global MVNO Coverage
- 4.4 Market Restraints
- 4.4.1 Margin Squeeze from Intense Price Competition
- 4.4.2 Dependence on Host MNOs for Network Quality and Wholesale Fees
- 4.4.3 Device-OEM Control of eSIM Ownership Bypassing MVNO Model
- 4.4.4 Private-Spectrum Sharing Lets Enterprises Self-Provision Service
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Model
- 5.1.1 Cloud
- 5.1.2 On-Premise
- 5.2 By Operational Mode
- 5.2.1 Reseller
- 5.2.2 Service Operator
- 5.2.3 Full MVNO
- 5.2.4 Light, Brand MVNO
- 5.3 By Subscriber Type
- 5.3.1 Consumer
- 5.3.2 Enterprise
- 5.3.3 IoT-Specific
- 5.4 By Application
- 5.4.1 Discount
- 5.4.2 Business
- 5.4.3 Cellular M2M
- 5.4.4 Media and Entertainment
- 5.4.5 Retail
- 5.4.6 Roaming
- 5.4.7 Migrant
- 5.4.8 Telecom Wholesale
- 5.5 By Network Technology
- 5.5.1 2G, 3G
- 5.5.2 4G, LTE
- 5.5.3 5G
- 5.5.4 Satellite, NTN
- 5.6 By Distribution Channel
- 5.6.1 Online, Digital-Only
- 5.6.2 Traditional Retail Stores
- 5.6.3 Carrier Sub-Brand Stores
- 5.6.4 Third-Party, Wholesale
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank, Share, Products and Services, Recent Developments)
- 6.4.1 TracFone Wireless, Inc.
- 6.4.2 Tesco Mobile Limited
- 6.4.3 Virgin Mobile (Virgin Media O2)
- 6.4.4 Lycamobile Group
- 6.4.5 Lebara Group B.V.
- 6.4.6 Boost Mobile LLC
- 6.4.7 Cricket Wireless LLC
- 6.4.8 Giffgaff Limited
- 6.4.9 1&1 Drillisch AG
- 6.4.10 PosteMobile S.p.A.
- 6.4.11 Truphone Limited
- 6.4.12 Kajeet, Inc.
- 6.4.13 Ting Mobile (Dish Wireless)
- 6.4.14 Google Fi Wireless
- 6.4.15 Altice Mobile (Optimum Mobile)
- 6.4.16 Asahi Net, Inc.
- 6.4.17 FreedomPop, Inc.
- 6.4.18 Airvoice Wireless LLC
- 6.4.19 FRiENDi Mobile
- 6.4.20 Voiceworks B.V.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment