

|
시장보고서
상품코드
2122402
중동 및 아프리카의 전기자동차 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Middle East And Africa Electric Vehicle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 중동 및 아프리카의 전기자동차(EV) 시장 규모는 2025년에 38억 3,000만 달러로 평가되었고, 2026년 50억 6,000만 달러에서 2031년까지 203억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 32.15%를 기록할 전망입니다.
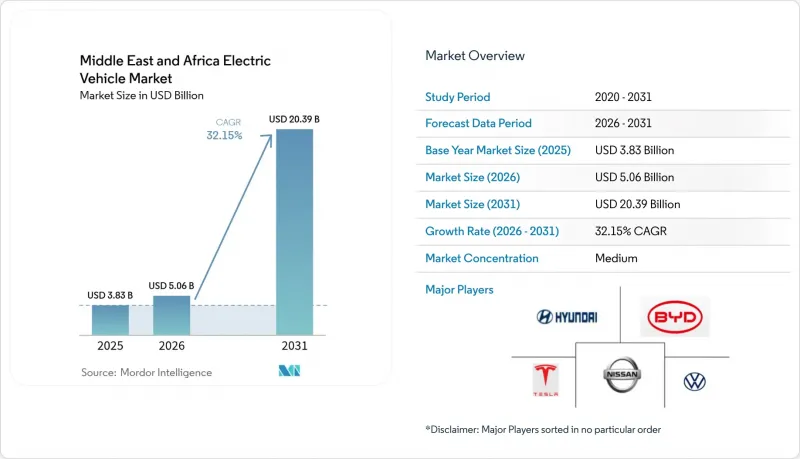
본 보고서는 구동 방식(배터리식 전기차, 플러그인 하이브리드차, 연료전지차), 차종(승용차, 소형 상용차 등), 배터리 화학 조성(리튬이온, 니켈수소, 기타), 충전 수준(7kW 미만의 교류 충전 등) 및 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
중동 및 아프리카 전기차 시장 동향과 인사이트
정부의 탈탄소화 의무화 및 내연기관(ICE) 금지 목표
걸프협력회의(GCC) 회원국들은 전기 모빌리티 할당 목표를 국가 개발 의제에 포함시켜, 자동차 제조업체의 투자 결정의 기반이 되는 수요 하한선을 확립하고 있습니다. 사우디아라비아의 ‘비전 2030’은 2030년까지 리야드 내 차량의 30%를 전기차로 전환할 것을 의무화하고 있는 반면, 아랍에미리트(UAE)의 연방 전략은 2050년까지 전기차 비중을 50%로 높이는 것을 목표로 하고 있습니다. 이러한 지침은 공공 부문의 조달을 무공해 차량으로 유도하고, 민간 부문의 차량 교체를 촉진하는 동시에, 걸프 표준화 기구(GSO)의 규정에 따른 인증 표준화를 추진하고 있어, 이를 통해 국경을 넘는 무역이 원활해집니다. 모로코에서는 2026년까지 2,500곳의 충전소 설치를 의무화하고 있으며, 이는 확고한 정책이 인프라 확장을 어떻게 가속화하는지를 보여줍니다. 법적 구속력이 있는 목표는 COP28의 공약과 밀접하게 연계되어 있으며, 투자자에게 장기적인 전망을 제공하고 초기 수요 변동을 보완하는 역할을 하고 있습니다.
공공 DC 급속 충전 회랑의 신속한 구축
도시 간 고속 충전 회랑의 구축을 통해 전기차는 도시 내 이동 수단에서 지역 전체를 아우르는 이동 수단으로 변모할 것입니다. 리야드-카심 고속도로에 설치된 EVIQ의 주력 150kW 충전 거점은 고속도로에서의 실용성을 입증함과 동시에, 향후 사우디아라비아에서 교통량이 가장 많은 10개 간선 도로를 포괄해 나갈 것임을 시사합니다. 이와 병행하여 UAE는 2030년까지 아부다비 전역에 7만 기의 공공 충전기를 설치할 계획이며, 두바이는 2025년까지 1,000곳을 설치하는 것을 목표로 하고 있어, 이를 통해 에미리트 내 주행 거리에 대한 불안을 사실상 해소하게 될 것입니다. 모로코의 계획에 따르면, 카사블랑카, 라바트, 탕헤르를 30분 이내에 충전이 가능한 재생에너지 구동 직류 충전 장치로 연결할 예정입니다. 나이지리아에서는 2025년에 서아프리카 최대 규모의 충전 허브가 개설되어, 인프라 구축이 신흥 시장으로 확대될 것입니다. 회랑을 따라 충전 거점 밀도가 높아짐에 따라 상용차의 가동 시간이 대폭 향상되어, 제벨 알리 등의 항만을 거점으로 하는 화물 운송 사업자들에게 전기화로의 길이 열리게 됩니다.
차량 초기 구매 가격의 높음과 소비자 대출 제한
배터리 가격이 하락하고 있음에도 불구하고, 높은 구매 가격으로 인해 저소득층을 대상으로 한 대중 시장 보급이 여전히 저해되고 있습니다. 이집트에서는 할부 계획이 제한적이고 환율 변동 위험에 노출되는 경화 통화로 지불해야 하기 때문에 전기차(EV) 신차 판매 점유율은 고작 0.1%에 그치고 있습니다. 중고 수입차의 증권화에 익숙한 기존 금융기관들은 전기차 시장 대출에 대한 잔존가치 벤치마크가 부족하여, 그 결과 금리 스프레드가 확대되고 있습니다. 사하라 이남 아프리카에서는 소액금융 제도가 승용차 구매가 아닌 이륜 택시를 대상으로 하고 있어, 자동차 제조업체의 규모의 경제 달성이 더욱 저해되고 있습니다.
부문 분석
2025년, 배터리식 전기차(BEV)는 전기차 시장 점유율의 78.64%를 차지하여, 해당 지역에서 완전 전기 구동 시스템에 대한 선호도가 입증되었으며, 플러그인 하이브리드차에 수반되는 복잡한 연료세 문제도 회피되었습니다. BEV의 매력은 유지보수의 간편함과 쇼핑몰, 공항, 산업단지 등에 설치된 목적지 충전기의 도입에 있습니다. 이 부문의 견고한 이익률 구조 덕분에 테슬라, BYD, 지리(Geely)는 기존의 딜러를 거치지 않는 소비자 대상 직접 판매 포털을 개설하게 되었습니다.
플릿 사업자들은 야간에 거점에서 충전을 수행하기 위해 BEV를 도입하고 있으며, 이를 통해 주간 업무에 미치는 지장을 줄이고 있습니다. 사우디아라비아가 산업 회랑 주변에서 그린 수소 충전 거점을 확대하고 있는 만큼, 연료전지 전기차(FCEV)는 2031년까지 연평균 성장률(CAGR) 35.90%를 기록하며 장거리 운송 분야에서 그 잠재력을 부각시키고 있습니다. 한편, 플러그인 하이브리드 차량은 여전히 과도기적인 존재로, 전력망의 신뢰성이 낮은 지역에서 주행 거리의 확실성을 제공합니다. 따라서 구동 방식의 구성 비율은 인프라의 성숙도를 반영하고 있으며, 걸프 지역 도시에서는 BEV가 주류를 이루는 반면, 사막 지대의 화물 운송 노선을 따라서는 연료전지차가 부상하고 있습니다.
2025년 매출액 중 승용차가 64.05%를 차지했으나, 중형 및 대형 상용차는 2031년까지 연평균 성장률(CAGR) 35.05%로 성장하여 기업 조달 채널 내 전기차 시장 규모를 확대할 것으로 예측됩니다. 유전 서비스용 트럭이나 라스트 마일 배송용 밴은 하루 주행 거리가 길기 때문에 연료비 절감 효과와 탄소 감사 측면에서의 이점이 더욱 큽니다. 제다 자유무역지역에서는 물류 기업들이 항만 당국의 배기가스 규제를 준수하기 위해 입찰 시 전기차 모델을 지정하고 있습니다. 카이로와 케이프타운에서 진행 중인 버스 전기화 시범 사업은 대중교통에 대한 수요가 증가하고 있음을 보여주고 있으며, 한편 라이드셰어 업체들은 도심부의 대기 정화 규제를 충족하기 위해 소형 해치백형 전기차를 도입하고 있습니다. 각 자동차 제조업체들은 지역에 맞춘 적재량, 개선된 실내 공조 시스템,비포장 도로에 대응한 강화 서스펜션 등을 통해 이에 대응하고 있습니다. 상용차 판매 대수가 증가함에 따라 트럭 차체, 배터리 케이스, 텔레매틱스 서비스를 모두 국내에서 조달할 수 있게 되어, 공급망의 현지화가 더욱 진전되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.03According to Mordor Intelligence, the electric vehicle market size in the Middle East and Africa was valued at USD 3.83 billion in 2025 and estimated to grow from USD 5.06 billion in 2026 to reach USD 20.39 billion by 2031, at a CAGR of 32.15% during the forecast period (2026-2031).
This report is Segmented by Drive Type (Battery-Electric, Plug-In Hybrid, and Fuel-Cell Electric), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Battery Chemistry (Lithium-Ion, Nickel-Metal Hydride, and Others), Charging Level (AC Below 7 KW, and More), and by Country. Market Forecasts are Provided in Terms of Value (USD).
Middle East And Africa Electric Vehicle Market Trends and Insights
Government Decarbonization Mandates and ICE-Ban Targets
Gulf Cooperation Council (GCC) members have embedded electric-mobility quotas into national development agendas, creating demand floors that anchor OEM investment decisions. Saudi Arabia's Vision 2030 compels 30% of Riyadh's vehicles to be electric by 2030, while the UAE's federal strategy targets a 50% electric-vehicle mix by 2050. These directives funnel public-sector procurement toward zero-emission models, catalyze private-sector fleet conversions, and standardize certification under Gulf Standardization Organization (GSO) rules, which ease cross-border trade. Morocco's mandates 2,500 charging points by 2026, illustrating how firm policy anchors accelerate infrastructure scale-up. Binding targets dovetail with COP28 commitments, giving investors long-cycle visibility, compensating for initial demand volatility.
Rapid Rollout of Public DC Fast-Charging Corridors
Intercity fast-charging corridors convert EVs from urban runabouts into region-wide mobility options. EVIQ's flagship 150 kW site on the Riyadh-Qassim motorway demonstrates highway viability and signals forthcoming coverage of the kingdom's 10 busiest arterial routes. In parallel, the UAE plans 70,000 public chargers across Abu Dhabi by 2030, while Dubai targets 1,000 sites by 2025, effectively eliminating intra-emirate range anxiety. Morocco's plan links Casablanca, Rabat, and Tangier with green-energy-powered DC units that supply sub-30-minute stops. Nigeria's 2025 inauguration of West Africa's largest assembled charging hub widens the infrastructure map to frontier markets. Corridor density materially lifts commercial-vehicle uptime, unlocking electrification for freight operators serving ports such as Jebel Ali.
High Upfront Vehicle Price and Limited Consumer Financing
Purchase-price premiums continue to deter mass-market adoption in lower-income segments even as batteries cheapen. Egypt's EV share remains just 0.1% of new-car sales due to limited installment plans and hard-currency outlays that expose buyers to exchange-rate swings. Traditional lenders, accustomed to securitizing used imports, lack residual-value benchmarks for electric vehicle market loans, inflating interest spreads. In Sub-Saharan Africa, microfinance mechanisms target two-wheeler taxis rather than four-wheeler purchases, further stalling scale economics for OEMs.
Other drivers and restraints analyzed in the detailed report include:
- Day-Time Solar-PV Surplus Driving Ultra-Low-Cost Charging Tariffs
- Oil-and-Gas Fleet-Electrification Pledges Unlocking Bulk Orders
- Influx of Cheap Used ICE Imports Undermines EV Demand
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Battery-electric vehicles (BEVs) commanded 78.64% of the electric vehicle market share in 2025, validating the region's preference for fully electric drivetrains and sidestepping the fuel-duty complexity of plug-in hybrids. BEV appeal stems from simpler maintenance and the rollout of destination chargers at malls, airports, and industrial parks. The segment's robust margin structure has enticed Tesla, BYD, and Geely to launch direct-to-consumer sales portals that bypass traditional dealerships.
Fleet operators adopt BEVs for depot-night charging, reducing daytime operational disruptions. Fuel-cell electric vehicles post a 35.90% CAGR through 2031 as Saudi Arabia scales green-hydrogen refueling nodes around its industrial corridors, underscoring their long-haul potential. Meanwhile, plug-in hybrids remain transitional, offering range security where grid reliability lags. The drive-type mix therefore mirrors infrastructure maturity, with BEVs prevailing in the urban Gulf and fuel-cells rising along desert freight links.
Passenger cars controlled 64.05% of 2025 revenue, yet medium and heavy commercial vehicles are forecast to outpace with a 35.05% CAGR to 2031, expanding the electric vehicle market size in corporate procurement channels. Oil-field service trucks and last-mile delivery vans accrue higher daily mileage, magnifying fuel savings and carbon audit benefits. Logistics firms in the Jeddah free zone now specify electric models in tenders to comply with port authority emissions limits. Bus electrification pilots in Cairo and Cape Town indicate growing public-transport appetite, while ride-hailing operators deploy small hatchback EVs to meet city-center clean-air mandates. OEMs are responding with region-tuned payload ratings, enhanced cabin HVAC, and reinforced suspensions for unpaved routes. As commercial volumes climb, supply-chain localization deepens because truck bodies, battery enclosures, and telematics services can all be sourced domestically.
Complete Report Scope:
- By Drive Type
- Battery-Electric (BEV)
- Plug-in Hybrid (PHEV)
- Fuel-Cell Electric (FCEV)
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Buses and Coaches
- Two and Three Wheelers
- By Battery Chemistry
- Lithium-ion (NMC / NCA / LFP)
- Nickel-Metal Hydride
- Others
- By Charging Level
- AC below 7 kW (Slow)
- AC above 7 kW - 22 kW (Semi-fast)
- DC above 22 kW (Fast / Ultra-fast)
- By Country
- Saudi Arabia
- United Arab Emirates
- Israel
- Egypt
- South Africa
- Nigeria
- Kenya
- Qatar
- Oman
- Rest of Middle East and Africa
List of Companies Covered in this Report:
- Tesla Inc.
- BYD Co. Ltd.
- Hyundai Motor Co.
- Kia Corp.
- Volkswagen AG
- Nissan Motor Co. Ltd.
- BMW Group
- Toyota Motor Corp.
- Stellantis N.V.
- Mercedes-Benz Group AG
- Renault Group
- Jaguar Land Rover Ltd.
- Zhejiang Geely Holding
- Lucid Group
- Ceer Motors
- Togg A.S.
- General Motors Co.
- SAIC-MG Motor
- Ford Motor Co.
- Rivian Automotive Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Decarbonizations Mandates and ICE-Ban Targets
- 4.2.2 Subsidies And Zero-Customs Duties on EV Imports (GCC)
- 4.2.3 Rapid Rollout of Public DC Fast-Charging Corridors
- 4.2.4 Declining Battery Pack Prices and Longer Driving Range
- 4.2.5 Oil-and-Gas Fleet Electrification Pledges Unlocking Bulk Orders
- 4.2.6 Day-Time Solar-PV Surplus Driving Ultra-Low-Cost Charging Tariffs
- 4.3 Market Restraints
- 4.3.1 High Upfront Vehicle Price and Limited Consumer Financing
- 4.3.2 Restricted Hot-Climate Model Availability From OEMs
- 4.3.3 Grid Unreliability Curbing Charger Uptime (Sub-Saharan Sites)
- 4.3.4 Influx of Cheap Used ICE Imports Undermines EV Demand
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value, USD Million)
- 5.1 By Drive Type
- 5.1.1 Battery-Electric (BEV)
- 5.1.2 Plug-in Hybrid (PHEV)
- 5.1.3 Fuel-Cell Electric (FCEV)
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles
- 5.2.3 Medium and Heavy Commercial Vehicles
- 5.2.4 Buses and Coaches
- 5.2.5 Two and Three Wheelers
- 5.3 By Battery Chemistry
- 5.3.1 Lithium-ion (NMC / NCA / LFP)
- 5.3.2 Nickel-Metal Hydride
- 5.3.3 Others
- 5.4 By Charging Level
- 5.4.1 AC below 7 kW (Slow)
- 5.4.2 AC above 7 kW - 22 kW (Semi-fast)
- 5.4.3 DC above 22 kW (Fast / Ultra-fast)
- 5.5 By Country
- 5.5.1 Saudi Arabia
- 5.5.2 United Arab Emirates
- 5.5.3 Israel
- 5.5.4 Egypt
- 5.5.5 South Africa
- 5.5.6 Nigeria
- 5.5.7 Kenya
- 5.5.8 Qatar
- 5.5.9 Oman
- 5.5.10 Rest of Middle East and Africa
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 Tesla Inc.
- 6.4.2 BYD Co. Ltd.
- 6.4.3 Hyundai Motor Co.
- 6.4.4 Kia Corp.
- 6.4.5 Volkswagen AG
- 6.4.6 Nissan Motor Co. Ltd.
- 6.4.7 BMW Group
- 6.4.8 Toyota Motor Corp.
- 6.4.9 Stellantis N.V.
- 6.4.10 Mercedes-Benz Group AG
- 6.4.11 Renault Group
- 6.4.12 Jaguar Land Rover Ltd.
- 6.4.13 Zhejiang Geely Holding
- 6.4.14 Lucid Group
- 6.4.15 Ceer Motors
- 6.4.16 Togg A.S.
- 6.4.17 General Motors Co.
- 6.4.18 SAIC-MG Motor
- 6.4.19 Ford Motor Co.
- 6.4.20 Rivian Automotive Inc.


