|
시장보고서
상품코드
2124180
태국의 세라믹 타일 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Thailand Ceramic Tiles - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
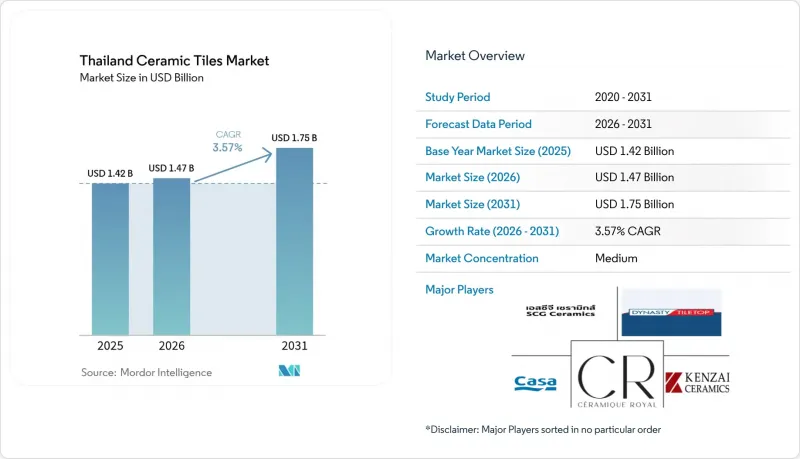
에 의하면, 태국의 세라믹 타일 시장 규모는 2025년에 14억 2,000만 달러로 평가되었고, 2026년 14억 7,000만 달러에서 2031년까지 17억 5,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 3.57%를 기록할 전망입니다.
본 보고서는 제품 유형별(도자기 타일, 유약 도장 세라믹 타일 등), 용도별(바닥, 벽, 지붕), 최종 사용자별(주택, 상업시설), 건설 유형별(신축, 개보수·교체), 유통 채널별(타일·석재 전문점, 홈센터·DIY 매장 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
태국의 세라믹 타일 시장 동향 및 인사이트
도시 지역의 주택 건설 급속한 회복
정부가 주택 담보 대출 우대 조치를 지속하고, 수요를 촉진하기 위해 양도세 감면을 시행함에 따라 신축 주택 분양 건수가 증가하고 있습니다. 동부 경제 회랑(EEC)에서는 개발업자들이 총액 1,570억 바트에 달하는 400건의 프로젝트를 발표했으며, 촌부리 주 및 주변 주에서는 지가가 50% 이상 상승했습니다. 프룩사 홀딩스(Pruksa Holdings)와 산시리(Sansiri)와 같은 대형 건설사들은 착공을 가속화하고 있으며, 이에 따라 중가대 및 고급 주택 모두에서 타일 조달 사이클이 활발해지고 있습니다. 중국과 일본 출신의 외국인 투자자들이 복합 용도 부동산을 공동 개발하고 있으며, 고급 도자기 타일을 선호하는 고사양 인테리어 사양이 추가되고 있습니다. 첫 주택 구매자에 대한 정책 지원과 대중교통망의 급속한 확장이 2027년까지 안정적인 주택 수요를 뒷받침하고 있습니다. 주택 건설의 회복은 팬데믹 기간 동안의 침체에서 근본적인 전환을 보여주고 있으며, 개발사들은 현재 고도의 세라믹 타일 솔루션이 필요한 품질과 지속가능성 요소에 주력하고 있습니다.
관광 주도형 호스피탈리티 프로젝트의 확대
태국은 2025년까지 외국인 관광객 4,000만 명 유치를 목표로 했으며, 호텔 개발 프로젝트에 있어 객실 수 증설 및 기존 시설의 개보수가 시급한 상황입니다. 센트럴 파타나(Central Pattana)는 2024년에 5개의 신규 호텔을 개장하고 468억 바트의 매출을 기록하며, 이 부문의 강력한 회복세를 보여주고 있습니다. 부티크 리조트에서는 국제 체인 브랜드 기준에 부합하는 항균 및 미끄럼 방지 기능을 갖춘 타일이 채택되고 있습니다. 대형 도자기 슬래브는 로비의 매끄러운 미관을 연출하는 동시에, 유동 인구가 많은 구역에서 타일 이음매 유지보수 부담을 줄일 수 있어 선호되고 있습니다. 따라서 관광 산업의 회복은 전문적인 상업용 타일 부문의 판매량 증가로 이어지고 있습니다. 또한, 호스피탈리티 업계의 건설 붐은 상업시설의 운영 효율성을 유지하면서도 독창적인 시각적 경험을 창출할 수 있는 대형 타일과 세련된 표면 처리에 대한 수요도 견인하고 있습니다.
중국 및 베트남산 저가 수입품의 급증
수입품은 현지 공장 출하 가격보다 최대 30% 낮은 가격 책정으로 시장 점유율을 빼앗아 갔으며, 2024년에는 태국의 여러 타일 제조업체가 생산량을 절반으로 줄일 수밖에 없게 되었습니다. 전자상거래 플랫폼은 기존 유통업체의 심사를 우회함으로써 소비자가 더 저렴한 해외산 타일에 직접 접근할 수 있도록 하고 있습니다. 태국 산업 연합은 경쟁의 균형을 되찾기 위해 세이프가드 관세 및 품질 감사 도입을 요구하며 로비 활동을 펼치고 있습니다. 이에 맞서 국내 기업들은 해외 판매자들이 흉내 낼 수 없는 디자인의 정교함, 신속한 물류, 보증 서비스를 강조하며 대응하고 있습니다. 이러한 경쟁은 소규모 생산자들이 시장에서 철수함에 따라 업계 재편을 가속화하고 있습니다. 정부는 국내 생산자들에게 공정한 경쟁 환경을 조성하기 위해, 저가 수입품에 대한 면세 조치 재검토와 보다 엄격한 품질 기준 시행을 포함한 정책 개입을 검토하고 있습니다. 수입 압력으로 인해 중소 제조업체들이 중국이나 베트남의 대규모 생산자들과 경쟁하는 데 필요한 규모의 경제를 실현하는 데 어려움을 겪고 있어, 업계의 재편과 효율화가 시급한 상황입니다.
부문 분석
도자기 타일은 뛰어난 밀도, 0.5% 미만의 흡수율, 그리고 디자인의 다양성을 바탕으로 2025년에 태국 세라믹 타일 시장 점유율의 41.40%를 차지했습니다. 유약을 입힌 세라믹 타일은 예산을 중시하는 건축 프로젝트에서 여전히 중요한 역할을 하고 있는 반면, 유약을 입히지 않은 테크니컬 바디는 R-12 미끄럼 저항 기준을 충족해야 하는 산업용 바닥재로 채택되고 있습니다. 모자이크 타일은 2031년까지 부티크 호텔과 고급 아파트에서 인상적인 백스플래시나 수영장 라이닝을 지정하는 경향이 있어 연평균 성장률(CAGR) 4.33%라는 호재를 누리고 있습니다. 수제 테라코타 등 장식용 ‘기타’ 제품은 소셜 미디어 주도의 인테리어 트렌드를 통해 주목받고 있습니다. 투자는 1,600톤의 압축이 가능한 프레스 기술과 미적 선택의 폭을 넓혀주는 디지털 잉크젯 생산 라인으로 이동하고 있으며, 이를 통해 포셀린 타일의 프리미엄 위상이 공고해지고 있습니다.
가처분 소득 증가와 해외 디자인 사례의 유입으로 인해, 줄눈 폭을 대폭 줄여 시각적으로 방을 넓어 보이게 하는 대형 포세린 패널로 소비자의 전환이 가속화되고 있습니다. 얇은 타일 기술 덕분에 과도한 자중을 추가하지 않고도 파사드 개보수가 가능해져, 상업 분야에 새로운 가능성이 열리고 있습니다. 모자이크의 성장은 복잡한 레이아웃을 단순화하는 맞춤형 메쉬 부착 시트에 힘입고 있습니다. 유약이 없는 무광 타일은 미관보다 내마모성 및 내화학성이 중시되는 EEC(동부 경제 회랑) 지역의 공장 확장에 적합합니다. 이러한 동향이 종합적으로 작용하여, 수입품으로 인한 판매량 압박이 있음에도 불구하고 태국의 세라믹 타일 시장은 고부가가치 제품으로의 전환을 가속화하고 있습니다.
2025년, 태국 세라믹 타일 시장 규모의 58.50%를 바닥 시공이 차지했습니다. 이는 상업시설의 치열한 유동 인구나 주택의 마모에 대한 수요에 기인한 것입니다. 쇼핑몰, 대중교통 허브, 산업 지역에서는 내하중성과 비용의 균형을 맞추기 위해 600×600mm 크기의 포세린 타일이 지정되어 있습니다. 벽면 마감은 2031년까지 디자이너들이 거실이나 호텔 로비에서 대리석이나 목재를 모방한 악센트 벽을 적극 도입함에 따라 연평균 성장률(CAGR) 4.65%로 성장을 지속하고, 있습니다. 지붕재 용도는 틈새 시장이지만, 열대 기후에 적합한 단열성을 갖춘 전통적인 점토 기와가 주류를 이루고 있습니다. 이러한 용도별 구성은 순수하게 기능적인 바닥재에서 장식적인 수직면으로의 다양화를 여실히 보여주고 있습니다.
벽면 용도의 확대는 잉크젯 인쇄의 사실성이 비약적으로 향상되어, 유지보수 부담 없이 석재 느낌의 마감판을 구현할 수 있게 된 데 기인합니다. 개발업체들은 누수 발생 지점을 줄이고 청소 수고를 덜기 위해 욕실 벽면을 바닥부터 천장까지 전면적으로 타일로 시공하는 경향을 보이고 있습니다. 지붕재 시장에서는 내염해성이 중시되는 연안 리조트 지역에서 수요가 서서히 증가하고 있습니다. 바닥재 부문은 공공 부문의 역 건설이나 PEI IV 등급의 내마모성이 요구되는 아파트 복도 등으로 인해 견조한 수요를 유지하고 있습니다. 이러한 균형 변화에 따라 제조업체는 태국 세라믹 타일 시장에서 차별화를 유지하기 위해 이용 사례에 따라 표면 마감, 미끄럼 계수, 시공용 부속품을 최적화해야 합니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the Thailand ceramic tiles market size was valued at USD 1.42 billion in 2025 and estimated to grow from USD 1.47 billion in 2026 to reach USD 1.75 billion by 2031, at a CAGR of 3.57% during the forecast period (2026-2031).
This report is Segmented by Product Type (Porcelain Tiles, Glazed Ceramic Tiles, and More), Application (Floor, Wall, Roofing), End-User (Residential, Commercial), Construction Type (New Construction, Renovation and Replacement), Distribution Channel (Specialty Tile & Stone Stores, Home Improvement & DIY Stores, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Thailand Ceramic Tiles Market Trends and Insights
Rapid Urban Residential Construction Rebound
New-home launches are climbing as the government sustains mortgage incentives and transfers fees reductions to stimulate demand. In the EEC, developers unveiled 400 projects worth THB 157 billion, pushing land prices up more than 50% in Chon Buri and satellite provinces. Leading builders such as Pruksa Holding and Sansiri are accelerating groundbreaks, which amplifies tile procurement cycles for both mid-market and luxury units. Foreign investors from China and Japan are co-developing mixed-use estates, adding higher-spec finish schedules that favor premium porcelain. Policy support for first-time buyers and rapid mass-transit extensions underpin steady residential demand through 2027. The residential construction rebound represents a fundamental shift from the pandemic-era slowdown, with developers now focusing on quality and sustainability features that require advanced ceramic tile solutions.
Tourism-Led Expansion of Hospitality Projects
Thailand targets 40 million foreign arrivals in 2025, pressuring hotel pipelines to add keys and refurbish legacy stock. Central Pattana opened five new hotels in 2024 and reported revenue of THB 46.8 billion, signaling strong sector recovery. Boutique resorts are specifying antimicrobial, slip-resistant tiles that comply with international chains' brand standards. Large-format porcelain slabs are favored to craft seamless lobby aesthetics while reducing grout maintenance in high-traffic zones. The tourism upswing therefore channels incremental volumes into specialized commercial-grade tile categories. The hospitality construction boom is also driving demand for large-format tiles and sophisticated surface treatments that can create distinctive visual experiences while maintaining operational efficiency in commercial settings.
Surge of Low-Cost Imports from China & Vietnam
Imports captured share by undercutting local ex-factory prices by up to 30%, forcing several Thai kilns to halve output in 2024. E-commerce platforms expedite direct consumer access to cheaper foreign tiles, bypassing traditional distributor vetting. The Federation of Thai Industries lobbies for safeguard duties and quality audits to restore competitive balance. Domestic firms respond by emphasizing design complexity, faster logistics, and warranty service impossible to replicate for overseas sellers. The dispute accelerates industry consolidation as sub-scale producers exit. The government is considering policy interventions including review of tax waivers on low-value imports and enforcement of stricter quality standards to level the competitive playing field for domestic producers. The import pressure is forcing industry consolidation and efficiency improvements as smaller manufacturers struggle to achieve economies of scale necessary for competing against large-scale Chinese and Vietnamese producers.
Other drivers and restraints analyzed in the detailed report include:
- Government EEC Infrastructure Build-Out
- Shift Toward Premium Porcelain & Large-Format Tiles
- Volatile Natural-Gas & Electricity Kiln Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Porcelain tiles claimed 41.40% of Thailand's ceramic tile market share in 2025 on the back of superior density, water absorption below 0.5%, and design versatility. Glazed ceramic remains relevant for budget-focused builds, whereas unglazed technical bodies fill industrial floors requiring R-12 slip standards. Mosaic variants enjoy a 4.33% CAGR tailwind as boutique hotels and high-end condos specify statement backsplashes and pool linings through 2031. Decorative "others" such as handmade terracotta gain visibility through social-media-driven interior trends. Investments pivot toward pressing technology capable of 1600-ton compaction and digital inkjet lines that widen aesthetic offerings, cementing porcelain's premium status.
Growing disposable income and imported design references accelerate consumer migration to large-format porcelain panels that slash grout lines and visually enlarge rooms. Thin-tile technology enables facade retrofits without adding excessive dead load, opening new commercial frontiers. Mosaic's growth benefits from customizable mesh-mounted sheets simplifying complex layouts. Unglazed bodies align with EEC factory expansions where abrasion and chemical resistance outweigh aesthetics. Altogether these dynamics propel Thailand ceramic tiles market toward higher value mix despite volume pressure from imports.
Floor installations represented 58.50% of the Thailand ceramic tiles market size in 2025 thanks to heavy commercial foot traffic and residential wear demands. Shopping malls, mass-transit hubs, and industrial corridors specify 600X600-millimeter porcelain pieces to balance load-bearing with cost. Wall cladding posts a 4.65% CAGR as designers push feature walls in living rooms and hotel lobbies that mimic marble and wood through 2031. Roofing applications, though niche, rely on traditional clay tiles for thermal insulation suited to tropical climates. The application split underscores diversification from purely functional flooring toward decorative vertical surfaces.
Wall expansion owes to technological leaps in inkjet realism, enabling stone-look veneers without maintenance burdens. Developers embrace full-height bathroom clads to reduce leak points and cleaning labor. Roofing sees incremental uplift in coastal resorts where salt-spray resistance is prized. Floor segments remain resilient via public-sector station builds and condominium corridors requiring PEI IV wear ratings. The evolving balance means manufacturers must tailor surface finishes, slip coefficients, and installation accessories per use case to sustain differentiation within Thailand ceramic tiles market.
Complete Report Scope:
- By Product Type
- Porcelain Tiles
- Glazed Ceramic Tiles
- Unglazed Ceramic Tiles
- Mosaic Tiles
- Others (Decorative, Patterned, Handmade)
- By Application
- Floor
- Wall
- Roofing
- By End-User
- Residential
- Commercial
- Hospitality (Hotels, Resorts)
- Retail Spaces
- Offices & Institutions
- Healthcare
- Educational Facilities
- Transport Hubs (Airports, Metro, Bus Terminals)
- Other Commercial Users
- By Construction Type
- New Construction
- Renovation and Replacement
- By Distribution Channel
- Specialty Tile & Stone Stores
- Home Improvement & DIY Stores
- Online Retail
- Direct Sales to Contractors
- By Geography
- Bangkok Metropolitan
- Central Thailand (ex-Bangkok)
- Northern Thailand
- Northeastern (Isan)
- Eastern Seaboard
- Western Thailand
- Southern Thailand
List of Companies Covered in this Report:
- SCG Ceramics (COTTO, Campana, Sosuco)
- Dynasty Ceramic Public Co.
- Royal Ceramic Industry (RCI)
- Kenzai Ceramic
- Casa Tiles
- Mogen Ceramic
- Tiger Ceramic
- RAK Ceramics Thailand
- Johnson Tiles (Thailand)
- Nitco (Thai distribution)
- Marazzi Group (Siam distribution)
- Kajaria Ceramics (Thai presence)
- Mohawk Industries (Daltile)
- Inax (LIXIL)
- Cera Cotto
- Thai Ceramic Coating
- Panthera Tiles
- Supreme Tile
- Campine Tiles
- STC Ceramic
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Urban Residential Construction Rebound
- 4.2.2 Tourism-Led Expansion Of Hospitality Projects
- 4.2.3 Government EEC Infrastructure Build-Out
- 4.2.4 Shift Toward Premium Porcelain & Large-Format Tiles
- 4.2.5 Adoption of Antimicrobial & Easy-Clean Glazes
- 4.2.6 Thin-Tile Overlay Solutions Boosting Renovation Demand
- 4.3 Market Restraints
- 4.3.1 Surge of Low-Cost Imports From China & Vietnam
- 4.3.2 Volatile Natural-Gas & Electricity Kiln Costs
- 4.3.3 Shortage of Skilled Tile Installers
- 4.3.4 ESG-Driven Kiln Decarbonisation Cap-Ex Burden
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Insights into the Latest Trends and Innovations in the Market
- 4.7 Insights on Recent Developments (New Product Launches, Strategic Initiatives, Investments, Partnerships, JVs, Expansion, M&As, etc.) in the Industry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product Type
- 5.1.1 Porcelain Tiles
- 5.1.2 Glazed Ceramic Tiles
- 5.1.3 Unglazed Ceramic Tiles
- 5.1.4 Mosaic Tiles
- 5.1.5 Others (Decorative, Patterned, Handmade)
- 5.2 By Application
- 5.2.1 Floor
- 5.2.2 Wall
- 5.2.3 Roofing
- 5.3 By End-User
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.2.1 Hospitality (Hotels, Resorts)
- 5.3.2.2 Retail Spaces
- 5.3.2.3 Offices & Institutions
- 5.3.2.4 Healthcare
- 5.3.2.5 Educational Facilities
- 5.3.2.6 Transport Hubs (Airports, Metro, Bus Terminals)
- 5.3.2.7 Other Commercial Users
- 5.4 By Construction Type
- 5.4.1 New Construction
- 5.4.2 Renovation and Replacement
- 5.5 By Distribution Channel
- 5.5.1 Specialty Tile & Stone Stores
- 5.5.2 Home Improvement & DIY Stores
- 5.5.3 Online Retail
- 5.5.4 Direct Sales to Contractors
- 5.6 By Geography
- 5.6.1 Bangkok Metropolitan
- 5.6.2 Central Thailand (ex-Bangkok)
- 5.6.3 Northern Thailand
- 5.6.4 Northeastern (Isan)
- 5.6.5 Eastern Seaboard
- 5.6.6 Western Thailand
- 5.6.7 Southern Thailand
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 SCG Ceramics (COTTO, Campana, Sosuco)
- 6.4.2 Dynasty Ceramic Public Co.
- 6.4.3 Royal Ceramic Industry (RCI)
- 6.4.4 Kenzai Ceramic
- 6.4.5 Casa Tiles
- 6.4.6 Mogen Ceramic
- 6.4.7 Tiger Ceramic
- 6.4.8 RAK Ceramics Thailand
- 6.4.9 Johnson Tiles (Thailand)
- 6.4.10 Nitco (Thai distribution)
- 6.4.11 Marazzi Group (Siam distribution)
- 6.4.12 Kajaria Ceramics (Thai presence)
- 6.4.13 Mohawk Industries (Daltile)
- 6.4.14 Inax (LIXIL)
- 6.4.15 Cera Cotto
- 6.4.16 Thai Ceramic Coating
- 6.4.17 Panthera Tiles
- 6.4.18 Supreme Tile
- 6.4.19 Campine Tiles
- 6.4.20 STC Ceramic
7 Market Opportunities & Future Outlook
- 7.1 Expansion of Exports to ASEAN and Global Markets
- 7.2 Boost in Renovation-Driven Tile Consumption Nationwide