

|
시장보고서
상품코드
2125278
인도네시아의 중고차 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Indonesia Used Car - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 인도네시아의 중고차 시장 규모는 2025년 718억 달러로 평가되었습니다. 2026년에는 765억 5,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 6.62%로 성장을 지속하여, 2031년에는 1,055억 달러에 이를 것으로 예측됩니다.
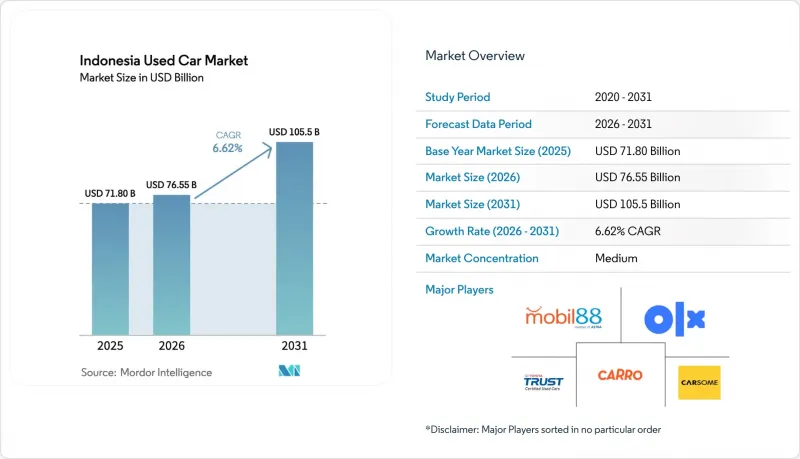
본 보고서는 차종별(해치백, 세단, 기타), 연료 유형별(가솔린, 디젤, 기타), 가격대별(5,500달러 미만, 5,500-1만 999달러, 기타),유통 채널별(온라인 디지털 분류 광고 포털, 전문 전자상거래 사업자, 기타), 벤더 유형별(조직화, 비조직화), 차량 연식별, 자금 제공업체별, 주별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
인도네시아의 중고차 시장 동향 및 인사이트
온라인 분류 광고 및 전자상거래 활동의 확대
디지털 포털 사이트를 통해 소비자는 가격, 주행 거리, 사진을 비교할 수 있게 되어 판매자에게 연락하기 전에 거래 과정을 효율화할 수 있습니다. 플랫폼 운영자는 차량 검사, 대출, 서류 절차를 통합하여 딜러 밀도가 낮은 지방 도시에서의 검색 번거로움을 덜어주고 있습니다. SEVA가 2024년에 달성한 1만 7,500대의 거래 대수와 8조 2,000억 루피아의 총 거래액은 이 비즈니스 모델의 유효성을 입증했으며, 자본 유입과 유니콘 기업의 탄생을 뒷받침했습니다. 기존 대기업들도 이에 대응하고 있습니다. 아스트라(Astra)의 OLX 인수는 자사 계열 금융사, 차량 검사 센터, 물류를 단일 서비스 체계로 통합했습니다. OJK(인도네시아 금융감독원)가 플랫폼 내 디지털 대출에 대한 규제 측면에서 지원함으로써 마찰 없는 경험을 완성했으며, 이는 인도네시아의 중고차 시장의 온라인 침투를 더욱 가속화하고 있습니다.
은행의 중고차 전용 대출 상품에 대한 집중
BCA 등 대형 은행들은 2024년에 자동차 대출 잔액을 65조 3,000억 루피아(41억 달러)까지 확대했습니다. 대출 기관들이 더 높은 수익률을 추구하는 가운데, 중고차가 차지하는 비중은 증가 추세를 보이고 있습니다. 독자적인 신용 평가 시스템은 기존 대출자의 소득에 대한 평가에 그치지 않고, 주행 거리대, 상세한 검사 평가, 예상 재판매 가격 등 다양한 중요한 요소를 반영하도록 발전했습니다. 이러한 혁신적인 접근 방식 덕분에 온라인 마켓플레이스 내에서 즉시 사전 승인이 가능해졌으며, 승인 소요 시간이 불과 몇 시간으로 대폭 단축되었습니다. 그 결과, 이 효율화된 프로세스는 전환율을 향상시킬 뿐만 아니라 인도네시아의 중고차 시장의 유동성을 활성화하여 구매자와 판매자 모두에게 역동적인 기회를 창출하고 있습니다.
주행거리계 조작이나 사고 이력 위조는 여전히 만연합니다.
각 주의 STNK 및 BPKB 시스템은 서로 연동되지 않아, 차량이 주 경계를 넘을 때 악의적인 업자가 주행 거리를 재설정하거나 침수 피해를 은폐하는 것이 가능해졌습니다. 첫 차를 구매하는 분이나 온라인 구매자는 문제가 있는 차량을 터무니없는 가격에 사게 되는 피해를 입고 있습니다. 신뢰 부족은 대출 리스크 프리미엄을 상승시키고, AI 기반 검사와 통합된 데이터 관리가 주류가 될 때까지 인도네시아의 중고차 시장의 거래 속도를 둔화시키고 있습니다.
부문별 분석
2025년, SUV는 인도네시아의 중고차 시장 점유율의 37.62%를 차지했습니다. 이는 높은 최저 지상고와 혼잡한 도로에서의 안전성에 대한 기대에 힘입은 결과입니다. MPV는 연평균 성장률(CAGR) 7.05%로 성장하고 있으며, 슬라이딩 도어와 유연한 좌석 배치를 중시하는 다세대 가구로부터 지지를 받고 있습니다. 세단은 연비 효율을 추구하는 통근자들을, 해치백은 좁은 주차 공간에 대응해야 하는 첫 차 구매자들을 대상으로 합니다. 인도네시아의 중고차 시장에서 SUV의 규모는 차량 교체에 따른 견조한 공급에 따라 성장할 것으로 예상되지만, 자바 섬 교외 지역에서는 통학 수요가 증가함에 따라 MPV의 판매까지 걸리는 기간이 더 짧아지고 있습니다. 중국의 자동차 제조업체들은 경쟁력 있는 하이브리드 모델로 두 부문에 진출하고 있으며, 이로 인해 일본의 기존 제조업체들은 라인업을 더욱 빈번하게 갱신해야 하는 압박을 받고 있습니다.
자카르타와 수라바야에서는 신에너지 SUV가 꿈을 품은 구매자들 수요를 충족시키는 반면, 도로 상황이 제각각인 외곽 섬 지역에서는 소형 MPV가 주류를 이루고 있습니다. 디지털 플랫폼은 알고리즘을 활용해 라이드셰어 잠재 고객에게는 SUV를, 가족 구성원이 늘어나는 계층에게는 MPV를 추천함으로써 매칭 효율을 높이고 있습니다. 인증 중고차 프로그램에서는 보증 서비스 업셀을 통한 수익성이 세단보다 높기 때문에 SUV와 MPV의 비중이 높아지고 있습니다.
2025년 시점에서도 인도네시아의 중고차 시장 규모의 63.10%를 가솔린 차량이 차지했지만, 부가가치세(VAT) 인하와 사치세 면제를 바탕으로 하이브리드 차량과 전기차는 연평균 성장률(CAGR) 12.34%로 성장을 지속하고 있습니다. 한편, 보조금 삭감 논의와 배기가스 규제 강화가 진행되는 가운데, 디젤차의 점유율은 축소되는 추세입니다. 인도네시아의 중고차 시장에서 전기차의 규모는 여전히 작지만, 급속 충전기의 도입과 정부의 로드맵이 향후 중고차 판매를 촉진할 것으로 보입니다. 2024년 이후 자카르타 경매에서 하이브리드차의 잔존 가치는 가솔린차에 비해 6-8% 더 높은 것으로 나타나, 구매자의 판단 기준이 변화하고 있음을 시사합니다.
배터리 성능 저하에 대한 불확실성이 보급 확대를 저해하고 있습니다. 딜러들은 OEM의 테스트를 거치지 않은 구형 BEV를 재고로 보유하는 것을 주저하고 있습니다. 은행들은 배터리 보증이 확정될 때까지 BEV에 대해 더 짧은 대출 기간과 더 높은 담보 평가 감액률을 적용하고 있습니다. 그러나 충전 인프라가 여전히 부족한 지방의 거래 시장에서는 가솔린 차량이 유동성 측면에서 우위를 유지하고 있습니다.
2025년, 인도네시아의 중고차 시장 매출액 중 1만 1,000-2만 1,999달러 가격대의 차량이 39.05%를 차지했으며 연평균 성장률(CAGR) 7.33%로 성장할 전망입니다. 이는 가구의 구매력 중앙값 및 은행의 대출 한도와 일치합니다. 5,500달러 미만의 엔트리 모델은 3급 도시의 현금 구매자들을 끌어들이고 있는 반면, 2만 2,000달러를 초과하는 프리미엄 가격대는 고급 브랜드를 선호하는 도시 부유층을 대상으로 하고 있습니다. 인도네시아 중형차 중고차 시장 점유율은 풍부한 트레이드인 차량과 1년 보증이 포함된 인증 프로그램의 혜택을 받고 있습니다.
할부 시뮬레이션을 보여주는 온라인 계산 도구는 중가대 차량의 인지도 향상에 기여하고 있습니다. 주요 포털 사이트에서는 계약금 20%, 상환 기간 48개월인 ‘아반자’(1만 5,000달러)가 여전히 가장 많이 검색되는 조합으로 나타납니다. 프리미엄 부문의 성장은 주재원의 교체와 기업의 출장용 차량 처분에 힘입고 있지만, 가성비를 중시하는 핵심 부문에 비하면 여전히 틈새 시장에 머물러 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the Indonesia used car market size is expected to grow from USD 71.80 billion in 2025 to USD 76.55 billion in 2026 and is forecast to reach USD 105.5 billion by 2031 at 6.62% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (Hatchbacks, Sedans, and More), Fuel Type (Petrol, Diesel, and More), Price Segment (Below USD 5, 500, USD 5, 500-10, 999, and More), Sales Channel (Online Digital Classified Portals, Pure-Play E-Retailers, and More), Vendor Type (Organized and Unorganized), Vehicle Age, Financing Providers, and Province. The Market Forecasts are Provided in Terms of Value (USD).
Indonesia Used Car Market Trends and Insights
Growing Online Classified and E-retail Activity
Digital portals empower consumers to compare prices, mileage, and photos, streamlining their transactions before reaching out to sellers. Platform operators integrate inspection, financing, and documentation, reducing search friction in secondary cities where dealer density is low. SEVA's 17,500-unit throughput and IDR 8.2 trillion gross transaction value in 2024 validated the model, encouraging capital inflows and unicorn creation . Traditional conglomerates have reacted: Astra's OLX acquisition aligned captive financing, inspection centers, and logistics into a single stack. Regulatory support from OJK for in-platform digital lending completes a frictionless experience, propelling the Indonesian used car market toward deeper online penetration.
Banks' Pivot to Used-car Specific Loan Products
Major banks such as BCA expanded vehicle loan books to IDR 65.3 trillion (USD 4.1 billion) in 2024, with used cars forming an increasing share as lenders chase higher yields . Proprietary scorecards have evolved to incorporate a range of crucial factors, including mileage bands, detailed inspection grades, and projected resale values, moving beyond the traditional focus on borrower income. This innovative approach allows for instant pre-approval within online marketplaces, significantly reducing approval times to just a few hours. As a result, this streamlined process not only enhances conversion rates but also invigorates liquidity in the Indonesian used car market, creating dynamic opportunities for both buyers and sellers.
Odometer and Accident-history Fraud Remains Pervasive
Provincial STNK and BPKB systems operate in silos, letting bad actors reset mileage or hide flood damage when vehicles cross borders. First-time buyers and online shoppers bear the brunt, paying inflated prices for compromised cars. Trust deficits raise financing risk premiums, dampening the Indonesia used car market velocity until AI inspection and centralized data become mainstream.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Organized Dealer Networks Outside Java
- Ride-hailing Fleet Renewal Cycles (Grab and Gojek)
- Fragmented Provincial Registration Databases
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
SUVs owned 37.62% of the Indonesia used car market share in 2025, buoyed by high ground clearance and perceived safety in congested streets. MPVs, climbing at 7.05% CAGR, appeal to multi-generational households that prize sliding doors and flexible seating. Sedans cater to commuters seeking fuel efficiency, and hatchbacks target first-time owners navigating tight parking norms. The Indonesia used car market size for SUVs is projected to keep pace with robust supply from fleet replacements, yet MPVs fetch quicker days-to-sale in suburban Java as school-run demand rises. Chinese OEMs have entered both segments with competitive hybrid trims, pushing Japanese incumbents to refresh line-ups more frequently.
New-energy SUVs feed aspirational buyers in Jakarta and Surabaya, while compact MPVs dominate outer-island lanes where road quality varies. Digital platforms algorithmically recommend SUVs to ride-hailing prospects and MPVs to growing families, increasing match efficiency. Certified programs overweight SUVs and MPVs because warranty upsells monetize better than sedans.
Petrol models still command 63.10% of the Indonesia used car market size in 2025, yet hybrids and electric models exhibit a 12.34% CAGR, propelled by VAT cuts and zero luxury tax. The diesel share erodes amid rising subsidy talk and emissions scrutiny. The Indonesia used car market size for electric models remains small, but fast-charger rollouts and government roadmaps catalyze future secondary sales. Residual values of hybrids have outperformed petrol peers in Jakarta auctions by 6-8% since 2024, hinting at shifting buyer calculus.
Battery degradation uncertainty curbs wider uptake. Dealers hesitate to stock older BEVs without OEM testing. Banks apply shorter tenures and higher collateral haircuts for BEVs pending battery warranties. Petrol cars, however, keep liquidity advantages in rural exchanges where charging remains scarce.
Units priced USD 11,000-21,999 held 39.05% of the Indonesia used car market revenue in 2025 and expanded at 7.33% CAGR, aligning with median household affordability and bank lending brackets. Entry models under USD 5,500 attract cash buyers in tier-3 cities, while premium brackets above USD 22,000 serve affluent urbanites eyeing luxury badges. The Indonesia used car market share of mid-range vehicles benefits from abundant trade-ins and certified programs bundling one-year warranties.
Online calculators showcasing installment scenarios boost mid-range visibility: a USD 15,000 Avanza with a 20% down payment and a 48-month tenor remains the most-searched combination on leading portals. Growth in premium slices rides on expatriate turnovers and corporate fleet disposals, but remains niche relative to value-centric core segments.
Complete Report Scope:
- By Vehicle Type
- Hatchbacks
- Sedans
- SUVs
- MPVs
- By Fuel Type
- Petrol
- Diesel
- Hybrid and Electric
- Others (LPG, CNG, etc.)
- By Price Segment
- Below USD 5,500
- USD 5,500 - 10,999
- USD 11,000 - 21,999
- >= USD 22,000
- By Sales Channel
- Online Digital Classified Portals
- Pure-play e-Retailers
- Dealer/OEM Online Platforms
- Physical Franchise Dealerships
- Independent Used-Car Lots
- Auction Houses (Physical and Online Hybrid)
- Peer-to-Peer (Private) Sales
- By Vendor Type
- Organized
- Unorganized
- By Vehicle Age
- 0 - 2 Years
- 3 - 5 Years
- 6 - 8 Years
- Above 8 Years
- By Financing Providers
- Original Equipment Manufacturers (OEMs)
- Banks
- Non-Banking Financial Companies
- By Province
- West Java
- East Java
- Central Java
- North Sumatra
- Banten
- Jakarta
- Other Provinces
List of Companies Covered in this Report:
- Mobil88 (PT Serasi Auto Raya (SERA))
- Toyota Astra Motor (Toyota Trust)
- PT Tunas Ridean Tbk.
- PT Inchcape Indomobil Distribution Indonesia (IIDI) (Mercedes Certified)
- BMW Premium Selection (BME Eurokars)
- OLX Indonesia
- Carro Indonesia (Trusty Cars Ltd )
- Carsome Indonesia
- Broom.id
- Carmudi Indonesia
- Moladin
- Mobil123
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Online Classified and E-retail Activity
- 4.2.2 Banks' Pivot to Used-car Specific Loan Products
- 4.2.3 Expanding Organized Dealer Networks Outside Java
- 4.2.4 Ride-hailing Fleet Renewal Cycles (Grab and Gojek)
- 4.2.5 OEM Buy-back Schemes Boosting Residual Values
- 4.2.6 AI-led Condition Grading Platforms Reducing Price Dispersion
- 4.3 Market Restraints
- 4.3.1 Odometer and Accident-history Fraud Remains Pervasive
- 4.3.2 Fragmented Provincial Registration Databases
- 4.3.3 High Inter-island Logistics Cost Discourages Non-Java Trade
- 4.3.4 Limited Certified-battery Health Checks for Used EVs
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Vehicle Type
- 5.1.1 Hatchbacks
- 5.1.2 Sedans
- 5.1.3 SUVs
- 5.1.4 MPVs
- 5.2 By Fuel Type
- 5.2.1 Petrol
- 5.2.2 Diesel
- 5.2.3 Hybrid and Electric
- 5.2.4 Others (LPG, CNG, etc.)
- 5.3 By Price Segment
- 5.3.1 Below USD 5,500
- 5.3.2 USD 5,500 - 10,999
- 5.3.3 USD 11,000 - 21,999
- 5.3.4 >= USD 22,000
- 5.4 By Sales Channel
- 5.4.1 Online Digital Classified Portals
- 5.4.2 Pure-play e-Retailers
- 5.4.3 Dealer/OEM Online Platforms
- 5.4.4 Physical Franchise Dealerships
- 5.4.5 Independent Used-Car Lots
- 5.4.6 Auction Houses (Physical and Online Hybrid)
- 5.4.7 Peer-to-Peer (Private) Sales
- 5.5 By Vendor Type
- 5.5.1 Organized
- 5.5.2 Unorganized
- 5.6 By Vehicle Age
- 5.6.1 0 - 2 Years
- 5.6.2 3 - 5 Years
- 5.6.3 6 - 8 Years
- 5.6.4 Above 8 Years
- 5.7 By Financing Providers
- 5.7.1 Original Equipment Manufacturers (OEMs)
- 5.7.2 Banks
- 5.7.3 Non-Banking Financial Companies
- 5.8 By Province
- 5.8.1 West Java
- 5.8.2 East Java
- 5.8.3 Central Java
- 5.8.4 North Sumatra
- 5.8.5 Banten
- 5.8.6 Jakarta
- 5.8.7 Other Provinces
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Mobil88 (PT Serasi Auto Raya (SERA))
- 6.4.2 Toyota Astra Motor (Toyota Trust)
- 6.4.3 PT Tunas Ridean Tbk.
- 6.4.4 PT Inchcape Indomobil Distribution Indonesia (IIDI) (Mercedes Certified)
- 6.4.5 BMW Premium Selection (BME Eurokars)
- 6.4.6 OLX Indonesia
- 6.4.7 Carro Indonesia (Trusty Cars Ltd )
- 6.4.8 Carsome Indonesia
- 6.4.9 Broom.id
- 6.4.10 Carmudi Indonesia
- 6.4.11 Moladin
- 6.4.12 Mobil123
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


