|
시장보고서
상품코드
2125468
중동 및 아프리카의 통신 MNO 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Middle East And Africa Telecom MNO - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
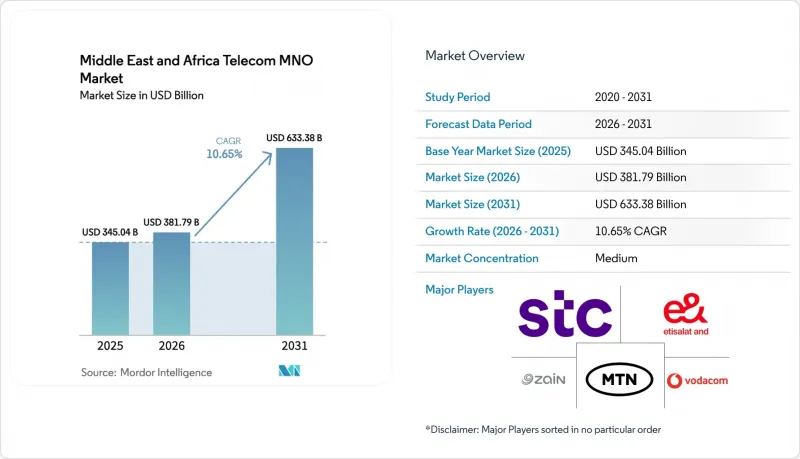
에 의하면, 2026년 중동 및 아프리카의 통신 MNO 시장 규모는 3,817억 9,000만 달러로 추정되고, 2025년 3,450억 4,000만 달러에서 확대해, 2031년에는 6,333억 8,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 10.65%가 될 것으로 전망됩니다.
본 보고서는 서비스 유형별(음성 서비스, 데이터·인터넷 서비스, 메시징 서비스, IoT·M2M 서비스, OTT·유료 TV 서비스, 기타 서비스), 최종 사용자별(기업, 일반 소비자) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 및 규모(가입자 수)로 제시되어 있습니다.
중동 및 아프리카의 통신 MNO 시장 동향 및 인사이트
동영상 중심 앱에 의한 모바일 데이터 트래픽의 폭발적인 증가
사용자들이 음성 통화나 SMS에서 고화질 스트리밍으로 전환함에 따라, 동영상 시청이 통신 사업자의 수익 구조를 혁신하고 있습니다. 걸프 국가들의 SMS 수익은 2013년 43억 달러에서 2018년 32억 달러(예측치)로 감소한 반면, 같은 기간 모바일 데이터 트래픽은 180% 증가했습니다. 이에 대응하여 통신 사업자들은 5G 스몰셀의 고밀도화를 추진하고 있으며, MENA 지역의 스몰셀 시장은 2030년까지 4억 1,254만 달러에 달하고 연평균 성장률(CAGR)은 40.9%에 이를 것으로 예측됩니다. 월 약 70달러의 FWA(고정 무선 접속) 계약은 새로운 광섬유 설치를 필요로 하지 않으면서 가정 내 스트리밍 트래픽을 수익화하고 있습니다. 네트워크 기획 담당자들은 현재 매시브 MIMO로 업그레이드하는 데 드는 비용과 기가비트 요금제를 기꺼이 지불하는 프리미엄 사용자 증가 추세를 저울질하며 검토하고 있습니다. 사하라 사막 이남의 아프리카에서는 2030년까지 사용자 1인당 월간 데이터 사용량이 3배인 14GB에 달할 것으로 예측되어, 주파수 대역과 백홀 모두에 대한 병행 투자가 요구되고 있습니다.
주파수 경매 지원으로 가속화되는 4G 및 5G 구축
걸프 국가 및 북아프리카의 규제 당국은 현재 경매를 통한 일시적 수입보다 통신 서비스 지역 커버리지 목표에 더 중점을 두고 있습니다. 사우디아라비아의 ‘2025-2027년 주파수 전망’에서는 비지상파 네트워크 및 FWA를 위한 새로운 주파수 대역을 확보하고, 간소화된 라이선싱 제도를 통해 사업자 시장 출시 기간을 대폭 단축하고 있습니다. 남아프리카공화국의 ‘2025년 국가 무선 주파수 계획(중)’ 역시 산업용 5G를 촉진하기 위한 전용 사설 네트워크 주파수 대역을 확보하고 있습니다. UAE에서는 이미 7,000곳의 5G 기지국이 가동 중이며, 2025년까지 500개의 캠퍼스 내 전용 네트워크 구축을 목표로 하는 정책을 내걸고 있습니다. 바레인, 요르단, 쿠웨이트, 사우디아라비아에서는 2G 및 3G의 동시 폐지로 인해 5G용 저주파 대역이 확보되어 주파수 이용 효율이 더욱 향상되고 있습니다. 이러한 노력의 결과, 지방 지역의 광대역 보급이 가속화되고 1비트당 전송 비용이 감소하고 있으며, 이는 중동 및 아프리카 통신 MNO 시장의 수익 기반을 유지하는 데 매우 중요합니다.
치열한 경쟁과 SIM 등록 의무화로 인한 ARPU 억제
케냐나 가나 등 시장에서는 신규 진입 사업자들에 의한 가격 경쟁이 격화되는 한편, 생체 인증을 통한 SIM 등록 의무화로 인해 규정 준수 비용이 증가하고 있습니다. 인플레이션은 소비자의 구매력을 저하시켜 추가적인 압박 요인이 되고 있는 반면, 규제 당국은 가계를 보호하기 위해 요금 인상에 상한선을 설정하고 있습니다. 통신 사업자들은 컨텐츠 번들링이나 로열티 앱으로 대응하고 있지만, 규제 환경이 분산되어 있어 시행 현황에 편차가 발생하고 있으며, 이는 중동 및 아프리카 통신 MNO 시장의 수익 창출을 제약하고 있습니다.
부문 분석
데이터 및 인터넷 요금제는 2025년 매출의 39.35%를 차지했으며, 중동 및 아프리카 이동통신사(MNO) 시장에서 가장 큰 수익원입니다. IoT/M2M은 특히 두드러지며, 2031년까지 중동 및 아프리카 통신 MNO 시장 규모에서 연평균 성장률(CAGR) 10.74%로 확대될 것으로 전망됩니다. OTT 플랫폼 간의 이용자 유치 경쟁으로 인해 음성 통화 및 메시징을 합친 비율은 25% 미만으로 떨어질 전망입니다. 이에 대응해 통신 사업자들은 이용자 유지율을 높이기 위해 동영상 서비스의 제로레이팅 및 유료 TV(PayTV) 번들 제공에 주력하고 있습니다. 엣지 컴퓨팅 노드 및 API의 수익화는 데이터 요금제를 보완하는 새로운 수익원으로 부상하고 있습니다.
예측 기간 동안 ‘Apps-as-a-Service’ 모델은 5G 독립형 코어에 의존하며, 게임 및 원격 의료 분야에서 저지연 이용 사례를 개척할 것입니다. 과거에는 경기 변동의 영향을 받기 쉬웠던 로밍 및 도매 트래픽은 아프리카 내 무역 흐름이 확대됨에 따라 안정화될 것입니다. 평균 데이터 요금은 하락 추세를 이어가겠지만, 수요의 높은 탄력성에 의해 상쇄되어 중동 및 아프리카 이동통신사(MNO) 시장 규모의 확대를 지속적으로 뒷받침할 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, Middle East and Africa telecom MNO market size in 2026 is estimated at USD 381.79 billion, growing from 2025 value of USD 345.04 billion with 2031 projections showing USD 633.38 billion, growing at 10.65% CAGR over 2026-2031.
This report is Segmented by Service Type (Voice Services, Data and Internet Services, Messaging Services, Iot and M2M Services, OTT and PayTV Services, and Other Services), End User (Enterprises, Consumer), and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Subscribers).
Middle East And Africa Telecom MNO Market Trends and Insights
Explosive growth in mobile data traffic from video-centric apps
Video viewing reshapes operator revenue architecture as users pivot from voice and SMS to high-definition streaming. SMS revenue in the Gulf fell from USD 4.3 billion in 2013 to a projected USD 3.2 billion in 2018, while mobile data volumes rose 180% in the same span . Operators respond by densifying 5G small cells; the MENA small-cell market is projected to reach USD 412.54 million by 2030, a 40.9% CAGR . FWA subscriptions, priced near USD 70 each month, monetize in-home streaming traffic without fresh fiber builds. Network planners now weigh the cost of massive-MIMO upgrades against the rising willingness of premium users to pay for gigabit packages. In Sub-Saharan Africa, monthly data usage is forecast to triple to 14 GB per user by 2030, demanding parallel investment in both spectrum and backhaul.
Accelerated 4G and 5G roll-outs enabled by supportive spectrum auctions
Regulators across the Gulf and North Africa now favor coverage targets over windfall auction fees. Saudi Arabia's 2025-2027 Spectrum Outlook sets aside new bands for non-terrestrial networks and FWA via light licensing, slashing time-to-market for operators. South Africa's draft 2025 National Radio Frequency Plan similarly carves out dedicated private-network spectrum that encourages industrial 5G . The UAE already operates 7,000 5G sites, with a policy aiming for 500 on-campus private networks by 2025. Concurrent 2G/3G switch-offs in Bahrain, Jordan, Kuwait, and Saudi Arabia release low-band spectrum for 5G, further boosting spectral efficiency. The collective result is faster rural broadband coverage and lower per-bit delivery cost, crucial for sustaining the Middle East and Africa telecom MNO market's profit pool.
Aggressive price competition and SIM registration curbing ARPU
Mandatory biometric SIM registration raises compliance costs even as new entrants trigger price wars in markets like Kenya and Ghana. Inflation adds a second squeeze by eroding consumer spend capacity, while regulators cap tariff hikes to protect households. Operators counter with content bundles and loyalty apps, but execution is uneven in fragmented regulatory environments, restraining monetization in the Middle East and Africa telecom MNO market.
Other drivers and restraints analyzed in the detailed report include:
- Enterprise digitization fueling IoT/M2M connectivity demand
- Youth-driven smartphone adoption across Sub-Saharan Africa
- Geopolitical instability delaying infrastructure investment
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Data and Internet plans accounted for 39.35% of 2025 revenue, making them the single largest contributor to the Middle East and Africa telecom MNO market. IoT/M2M is the standout, expanding at a CAGR of 10.74% in the Middle East and Africa telecom MNO market size by 2031. Voice and messaging together will slip below 25% as OTT platforms cannibalize usage. Operators respond by zero-rating video services and bundling PayTV to sustain stickiness. Edge computing nodes and API monetization emerge as adjacent revenue streams that complement data plans.
Over the forecast horizon, Apps-as-a-Service models will lean on 5G standalone cores, opening low-latency use cases in gaming and telemedicine. Roaming and wholesale traffic, once cyclical, stabilize as intra-Africa trade flows broaden. Average data pricing will continue its southward drift but remain offset by strong volume elasticity, supporting the Middle East and Africa telecom MNO market size expansion.
Complete Report Scope:
- Overall Telecom Revenue and ARPU
- Service Type
- Voice Services
- Data and Internet Services
- Messaging Services
- IoT and M2M Services
- OTT and PayTV Services
- Other Services (VAS, Roaming, Enterprise and Wholesale, etc.)
- End-user
- Enterprises
- Consumer
- Geography
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of the Middle East (Qatar, Kuwait, Bahrain, Oman, Jordan, Iraq, Lebanon, Israel, and Others)
- Africa
- South Africa
- Nigeria
- Rest of Africa (Egypt, Morocco, Algeria, Tunisia, Ghana, Tanzania, Senegal, Ethiopia, Uganda, Kenya, and Others)
- Middle East
List of Companies Covered in this Report:
- e& (Etisalat Group)
- STC Group
- Ooredoo Group
- Zain Group
- MTN Group
- Vodacom Group
- Orange Middle East and Africa
- Airtel Africa
- Safaricom PLC
- Maroc Telecom SA
- Telecom Egypt (WE)
- Globacom Limited (Glo Mobile)
- 9mobile (EMTS)
- Telkom SA SOC Limited
- Cell C
- Omantel
- Batelco (Beyon Group)
- du (EITC)
- Sudan Telecom Group Limited (Sudatel)
- Ethio Telecom
- AXIAN Telecom
- Econet Wireless Zimbabwe
- MTC Namibia
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Regulatory and Policy Framework
- 4.3 Spectrum Landscape and Competitive Holdings
- 4.4 Telecom Industry Ecosystem
- 4.5 Macroeconomic and External Drivers
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Competitive Rivalry
- 4.6.2 Threat of New Entrants
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Bargaining Power of Buyers
- 4.6.5 Threat of Substitutes
- 4.7 Key MNO KPIs (2020-2025)
- 4.7.1 Unique Mobile Subscribers and Penetration Rate
- 4.7.2 Mobile Internet Users and Penetration Rate
- 4.7.3 SIM Connections by Access Technology and Penetration
- 4.7.4 Cellular IoT / M2M Connections
- 4.7.5 Broadband Connections (Mobile and Fixed)
- 4.7.6 ARPU (Average Revenue Per User)
- 4.7.7 Average Data Usage per Subscription (GB/month)
- 4.8 Market Drivers
- 4.8.1 Explosive growth in mobile data traffic from video-centric apps
- 4.8.2 Accelerated 4G and 5G roll-outs enabled by supportive spectrum auctions
- 4.8.3 Enterprise digitization fueling IoT/M2M connectivity demand
- 4.8.4 Youth-driven smartphone adoption across Sub-Saharan Africa
- 4.8.5 Cross-border mobile-money interoperability boosting ARPU
- 4.8.6 Private 5G network slicing for mega-projects and smart cities
- 4.9 Market Restraints
- 4.9.1 Aggressive price competition and SIM registration curbing ARPU
- 4.9.2 Geopolitical instability delaying infrastructure investment
- 4.9.3 LEO satellite broadband emerging as rural substitute
- 4.9.4 Limited fiber backhaul in land-locked African nations
- 4.10 Technological Outlook
- 4.11 Analysis of key business models in Telecom Sector
- 4.12 Analysis of Pricing Models and Pricing
5 MARKET SIZE AND GROWTH FORECASTS (VALUE AND VOLUME)
- 5.1 Overall Telecom Revenue and ARPU
- 5.2 Service Type
- 5.2.1 Voice Services
- 5.2.2 Data and Internet Services
- 5.2.3 Messaging Services
- 5.2.4 IoT and M2M Services
- 5.2.5 OTT and PayTV Services
- 5.2.6 Other Services (VAS, Roaming, Enterprise and Wholesale, etc.)
- 5.3 End-user
- 5.3.1 Enterprises
- 5.3.2 Consumer
- 5.4 Geography
- 5.4.1 Middle East
- 5.4.1.1 Saudi Arabia
- 5.4.1.2 United Arab Emirates
- 5.4.1.3 Rest of the Middle East (Qatar, Kuwait, Bahrain, Oman, Jordan, Iraq, Lebanon, Israel, and Others)
- 5.4.2 Africa
- 5.4.2.1 South Africa
- 5.4.2.2 Nigeria
- 5.4.2.3 Rest of Africa (Egypt, Morocco, Algeria, Tunisia, Ghana, Tanzania, Senegal, Ethiopia, Uganda, Kenya, and Others)
- 5.4.1 Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Investments by key vendors, 2023-2025
- 6.3 Market share analysis for MNOs, 2024
- 6.4 Product Benchmarking Analysis for mobile network services
- 6.5 MNO snapshot (subscribers, churn rate, ARPU, etc.)
- 6.6 Company Profiles* of MNOs (Includes Business Overview | Service Portfolio | Financials | Business Strategy and Recent Developments | SWOT Analysis)
- 6.6.1 e& (Etisalat Group)
- 6.6.2 STC Group
- 6.6.3 Ooredoo Group
- 6.6.4 Zain Group
- 6.6.5 MTN Group
- 6.6.6 Vodacom Group
- 6.6.7 Orange Middle East and Africa
- 6.6.8 Airtel Africa
- 6.6.9 Safaricom PLC
- 6.6.10 Maroc Telecom SA
- 6.6.11 Telecom Egypt (WE)
- 6.6.12 Globacom Limited (Glo Mobile)
- 6.6.13 9mobile (EMTS)
- 6.6.14 Telkom SA SOC Limited
- 6.6.15 Cell C
- 6.6.16 Omantel
- 6.6.17 Batelco (Beyon Group)
- 6.6.18 du (EITC)
- 6.6.19 Sudan Telecom Group Limited (Sudatel)
- 6.6.20 Ethio Telecom
- 6.6.21 AXIAN Telecom
- 6.6.22 Econet Wireless Zimbabwe
- 6.6.23 MTC Namibia
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment