

|
시장보고서
상품코드
2119569
아프리카의 구독형 주문형 비디오(SVOD) : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Africa SVOD - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
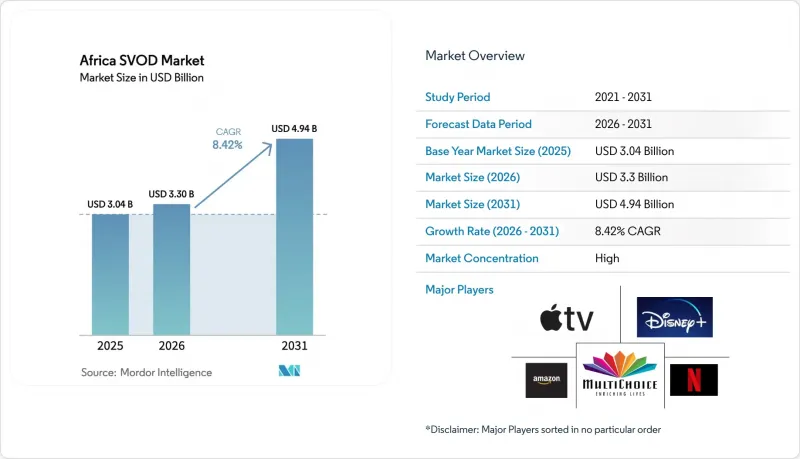
에 의하면, 아프리카의 구독형 주문형 비디오(SVOD) 시장 규모는 2025년에 30억 4,000만 달러로 평가되었습니다. 2026년 33억 달러에서 2031년까지 49억 4,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 8.42%를 나타낼 전망입니다.
본 보고서는 컨텐츠 장르(드라마, 음악, 스포츠 등), 수익 모델(구독형 비디오 온 디맨드, 거래형 비디오 온 디맨드), 기기 유형(스마트폰,스마트 TV, 태블릿, PC 또는 노트북 등), 연령대(18-24세, 25-34세, 35-44세, 45세 이상), 지역(케냐, 남아프리카공화국, 나이지리아 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
아프리카의 구독형 주문형 비디오(SVOD) 시장 동향 및 인사이트
세계 기업의 진입에 따른 경쟁 심화
각 세계 플랫폼 기업들은 오리지널 작품 제작 및 배포 제휴 체결을 통해 아프리카 시장에 대한 집중도를 높이고 있습니다. 넷플릭스만 해도 나이지리아 작품 283편에 대한 라이선스를 확보하고, 추가 컨텐츠 개발을 위해 2,360만 달러를 배정하는 등 현지 시장에 대한 지속적인 투자를 보여주고 있습니다. 적극적인 현지화를 통해 어필력은 확대되고 있지만, 가격에 민감한 시장에서 거듭되는 가격 인상은 수익화 어려움을 여실히 드러내고 있습니다. Disney+는 남아프리카공화국 시장 진출에 주력하는 한편, Amazon Prime Video는 전자상거래 혜택과 스트리밍 서비스를 결합하여 차별화를 꾀하고 있습니다. Canal+는 MultiChoice 인수를 발판 삼아 50개국, 약 5,000만 명의 가입자로 규모를 확대하며 프리미엄 컨텐츠를 둘러싼 경쟁을 격화시키고 있습니다.
저렴한 모바일 데이터 번들의 확대
통신 사업자가 주도하는 데이터 번들 및 제로 레이팅이 스트리밍 서비스의 보급을 뒷받침하고 있습니다. 사파리콤은 광섬유 통신 속도를 2배로 높이고, 모바일과 유선 회선을 통합한 패밀리 공유 요금제를 도입하여 스타링크 시장 진입에 직접 대응하고 있습니다. M-PESA Ratiba의 정기 이체 기능은 구독료 결제를 자동화하여 해지율을 최소화하고 있습니다. 에어텔(Airtel)의 가상 마스터카드를 통해 1억 5,000만 명의 모바일 머니 이용자가 국제 서비스에 가입할 수 있게 되어, 결제 장벽이 낮아지고 대상 고객층이 확대되고 있습니다. 이러한 선불 번들 및 소액 결제는 진입 장벽을 낮추고, 아프리카의 구독형 주문형 비디오(SVOD) 시장 전체에서 수요를 지속시키고 있습니다.
높은 가입비와 ARPU 간의 갈등
가격 인상은 보급을 저해하고, 규제 당국의 감시를 강화하는 요인이 됩니다. 멀티초이스 나이지리아는 2025년에 DStv 요금을 22% 이상 인상하여 월 이용료를 44,500 나이라(50.3 달러)로 올렸고, 이로 인해 소비자들의 반발을 샀습니다. 가나 당국은 요금을 30% 인하하지 않으면 면허를 취소하겠다고 경고했습니다. 넷플릭스는 2년 동안 나이지리아에서 3차례에 걸쳐 가격 인상을 단행하며, 아프리카의 구독형 주문형 비디오(SVOD) 시장에서 비용 회수와 합리적인 가격 사이의 긴장 관계를 여실히 드러냈습니다. 결국, 이러한 높은 가격 대 소득 비율은 저소득층 및 농촌 지역 사용자들의 서비스 보급을 제한하고 있습니다.
부문 분석
2025년에는 드라마가 매출의 44.76%를 차지하며 아프리카의 구독형 주문형 비디오(SVOD) 시장의 핵심으로서의 입지를 공고히 했습니다. ‘Blood and Water’와 같은 크로스오버 히트작의 성공으로 아프리카 드라마에 대한 세계적 수요가 확대된 한편, 멀티초이스(Multichose)가 2024 회계연도에 4개 주요 지역에서 제작한 59편의 현지 오리지널 작품은 프리미엄 스토리텔링 분야에서 아프리카의 구독형 주문형 비디오(SVOD) 시장 내 해당 기업의 입지를 강화했습니다. 라이브 이벤트와 라이프스타일 프로그램도 수요를 뒷받침하고 있지만, 드라마는 모든 연령층에서 장기적인 인기를 유지하고 있습니다. 스포츠는 2025년 매출에서 차지하는 비중이 13.28%에 그쳤지만, 2025년 FIFA 클럽 월드컵 중계권과, AFCON 준결승에서 사상 최대인 1,030만 명의 순 시청자를 기록한 것이 뒷받침되어, 2031년까지의 연평균 성장률(CAGR)은 10.05%로 전망됩니다. Showmax가 제공하는월69랜드(3.73달러)의 모바일 전용 프리미어리그 요금제는 스포츠 구독을 주도하는 ‘스마트폰 우선’ 전략을 강조하고 있습니다.
이 부문의 성장 여지는 아프리카의 방대한 축구 팬층과, 고가의 일반 엔터테인먼트 요금제는 피하더라도 주요 토너먼트에는 기꺼이 비용을 지불하는 팬들의 태도를 반영하고 있습니다. 아프리카의 구독형 주문형 비디오(SVOD) 시장에서는 각 애그리게이터들이 정기 과금 모델과 트랜잭션형 모델을 융합하기 위해 페이-퍼-뷰(PPV) 애드온을 점점 더 많이 도입하고 있습니다. 예측 기간 동안, 지역 리그 및 여자 스포츠 중계권을 확보한 제공업체는 사용자 참여도를 확대할 것이며, 한편 저지연 스트리밍과 인터랙티브한 ‘워치 파티’는 고객 유지율을 높여갈 것입니다. 드라마는 계속해서 주도적인 위치를 유지할 것으로 예상되지만, 모바일 네트워크를 통한 라이브 이벤트 접근이 용이해지고 있다는 점을 감안할 때, 스포츠, 다큐멘터리, 음악에 일부 점유율을 양보하게 될 것입니다.
2025년에는 SVOD 모델이 매출의 91.12%를 차지했으며, 이는 아프리카의 구독형 주문형 비디오(SVOD) 시장에서 소비자들이 정액제 서비스를 선호한다는 점을 보여줍니다. 일괄 데이터 요금제, 모바일 결제 자동 이체, 통신사와의 번들 계약이 지속적인 매출을 뒷받침하고 해지율을 낮추고 있습니다. 24개 프랑스어권 국가에서 Canal+ 패키지에 Netflix가 통합된 것은 배포망 활용을 상징하는 사례입니다. 한편, Showmax의 Peacock을 활용한 리뉴얼은 4K 스트리밍과 컨텐츠 탐색 기능을 강화하여 구독 요금의 정당성을 높이고 있습니다. 지배적인 위치를 차지하고 있음에도 불구하고, SVOD는 가격 측면의 제약에 직면해 있으며, 모바일 전용 요금제나 가구 공유 요금제의 도입이 시도되고 있습니다.
TVOD의 연평균 성장률(CAGR) 9.25%는 가격에 민감한 사용자나 장기 계약을 원치 않으면서도 프리미엄 독점 컨텐츠를 찾는 사용자에게 매력적인 ‘일회성 결제’ 방식에 기인합니다. 이 모델은 대히트 영화 개봉이나 스포츠 결승전 등을 지원하며, 플랫폼이 수요의 정점을 수익화할 수 있게 해줍니다. 하이브리드형 수익화 모델-카탈로그 컨텐츠를 위한 정액제와 고가치 이벤트를 위한 종량제를 융합한 방식은 아프리카의 구독형 주문형 비디오(SVOD) 시장의 수익 변동에 대한 실용적인 헤지 수단으로 부상하고 있습니다. 향후에는 광고 수익형 요금제가 TVOD 성장의 일부를 흡수할 가능성이 있지만, 주목도가 높은 이벤트나 조기 공개 타이틀에 대해서는 종량제 옵션이 계속해서 존재할 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the Africa SVOD market size was valued at USD 3.04 billion in 2025 and estimated to grow from USD 3.3 billion in 2026 to reach USD 4.94 billion by 2031, at a CAGR of 8.42% during the forecast period (2026-2031).
This report is Segmented by Content Genre (Drama, Music, Sports, and More), Revenue Model (Subscription Video On Demand, and Transactional Video On Demand), Device Type (Smartphone, Smart TV, Tablet, PC or Laptop, and More), Age Group (18-24 Years, 25-34 Years, 35-44 Years, and 45 Years and Above), and Geography (Kenya, South Africa, Nigeria, and More). The Market Forecasts are Provided in Terms of Value (USD).
Africa SVOD Market Trends and Insights
Intensification of Competition with Global Entrants
Global platforms deepen their African focus by commissioning originals and striking distribution alliances. Netflix alone licensed 283 Nigerian titles and earmarked USD 23.6 million for further content development, signalling sustained local investment. Aggressive localization broadens appeal, yet recurring price hikes in price-sensitive markets highlight monetization complexities. Disney + concentrates its rollout on South Africa, whereas Amazon Prime Video packages streaming with e-commerce perks to differentiate. Canal+ leverages its MultiChoice acquisition to scale across 50 countries and nearly 50 million subscribers, intensifying the fight for premium.
Expansion of Affordable Mobile Data Bundles
Operator-led data bundles and zero-rating propel streaming uptake. Safaricom doubled fiber speeds and introduced family share plans that merge mobile and fixed-line access, directly confronting Starlink's entry. M-PESA Ratiba's standing-order feature automates subscription payments and minimizes churn. Airtel's virtual Mastercard lets 150 million mobile-money users subscribe to international services, reducing payment friction and expanding addressable wallets. Such prepaid bundles and micropayments lower entry barriers and sustain demand across the Africa SVOD market.
Persistently High Subscription Fees Versus ARPU
Price hikes strain adoption and amplify regulatory scrutiny. MultiChoice Nigeria raised DStv premiums by more than 22% in 2025, pushing monthly fees to NGN 44,500 (USD 50.3) and sparking consumer backlash. Ghana's authorities threatened to revoke licenses unless fees dropped by 30% Netflix enacted three Nigerian price increases in two years, highlighting the tension between cost recovery and affordability within the Africa SVOD market. Ultimately, these high price-to-income ratios limit penetration among lower-income and rural users.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Smartphone Penetration Across Africa
- Rising Local Content Investment Incentives
- Patchy Broadband Infrastructure Outside Metros
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Drama accounted for 44.76% of revenue in 2025, cementing its place as the cornerstone of the Africa SVOD market share. The success of crossover hits such as "Blood and Water" expanded global appetite for African drama, while MultiChoice's 59 local originals across four core territories in fiscal 2024 increased its Africa SVOD market size footprint in premium storytelling. Live-event genres and lifestyle shows supplement demand, yet dramas retain longer shelf life across demographics. Sports, although only 13.28% of 2025 revenue, exhibits a 10.05% CAGR to 2031, powered by rights to FIFA Club World Cup 2025 and AFCON's record-shattering 10.3 million unique-viewer semifinal.Showmax's mobile-only Premier League tier at ZAR 69 (USD 3.73) monthly underscores the smartphone-first positioning that drives sports subscriptions.
The segment's upside reflects Africa's vast football fandom and the willingness of fans to pay for marquee tournaments even if they avoid higher-priced general-entertainment tiers. Aggregators increasingly deploy pay-per-view add-ons within the Africa SVOD market to blend recurring and transactional models. Over the forecast period, providers that secure local leagues and women's sports will widen engagement, while low-latency streaming and interactive watch-parties will deepen retention. Drama is expected to hold leadership but cede some share to sports, documentaries and music, given the rising accessibility of live events on mobile networks.
The SVOD model captured 91.12% of receipts in 2025, illustrating consumer preference for flat-rate access in the Africa SVOD market. Bulk data top-ups, standing-order mobile payments and telco-bundling agreements sustain recurring revenues and reduce churn. Netflix bundles within Canal+ packages across 24 Francophone countries exemplify distribution leverage, whereas Showmax's Peacock-powered relaunch enhances 4K streaming and content discovery to justify subscription price points. Despite dominance, SVOD faces affordability constraints, prompting experimentation with mobile-only plans and shared-household tiers.
TVOD's 9.25% CAGR stems from its pay-as-you-go appeal to price-sensitive users or those seeking premium exclusives without long-term commitments. The model supports blockbuster movie releases alongside sports finals, enabling platforms to monetize peaks in demand. Hybrid monetization-merging subscription for catalog content and transactional for high-value events-emerges as a practical hedge against income volatility in the Africa SVOD market. Over time, ad-supported tiers may absorb part of TVOD growth, yet transactional options will persist for marquee events and early-release titles.
Complete Report Scope:
- By Content Genre
- Drama
- Music
- Sports
- Other Content Genres
- By Revenue Model
- Subscription Video on Demand
- Transactional Video on Demand
- By Device Type
- Smartphone
- Smart TV
- Tablet
- PC or Laptop
- Other Device Types
- By Age Group
- 18-24 Years
- 25-34 Years
- 35-44 Years
- 45 Years and above
- By Country
- Kenya
- South Africa
- Nigeria
- Egypt
- Morocco
- Rest of Africa
List of Companies Covered in this Report:
- Amazon.com Inc.
- Netflix Inc.
- MultiChoice Group Ltd.
- Walt Disney Company (Disney+)
- Apple Inc. (Apple TV+)
- Canal+ Group (MyCanal)
- PCCW Media Group (Viu)
- iROKO Partners Ltd. (iROKOtv)
- Google LLC (YouTube Premium)
- MTN Group Ltd. (Ayoba)
- Huawei Technologies Co. Ltd. (Huawei Video)
- StarTimes Group (StarTimes ON)
- Orange S.A. (Orange VOD)
- StarTimes Media
- Telkom SA SOC Ltd. (TelkomONE)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Intensification of competition with global entrants
- 4.2.2 Expansion of affordable mobile data bundles
- 4.2.3 Surge in smartphone penetration across Africa
- 4.2.4 Rising local content investment incentives
- 4.2.5 Telco-OTT hybrid bundling strategies
- 4.2.6 Introduction of cloud-native streaming architectures
- 4.3 Market Restraints
- 4.3.1 Persistently high subscription fees vs ARPU
- 4.3.2 Patchy broadband infrastructure outside metros
- 4.3.3 Increasing piracy via illicit streaming devices
- 4.3.4 Local currency volatility impacting pricing power
- 4.4 Industry Ecosystem Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Average Revenue per User Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Content Genre
- 5.1.1 Drama
- 5.1.2 Music
- 5.1.3 Sports
- 5.1.4 Other Content Genres
- 5.2 By Revenue Model
- 5.2.1 Subscription Video on Demand
- 5.2.2 Transactional Video on Demand
- 5.3 By Device Type
- 5.3.1 Smartphone
- 5.3.2 Smart TV
- 5.3.3 Tablet
- 5.3.4 PC or Laptop
- 5.3.5 Other Device Types
- 5.4 By Age Group
- 5.4.1 18-24 Years
- 5.4.2 25-34 Years
- 5.4.3 35-44 Years
- 5.4.4 45 Years and above
- 5.5 By Country
- 5.5.1 Kenya
- 5.5.2 South Africa
- 5.5.3 Nigeria
- 5.5.4 Egypt
- 5.5.5 Morocco
- 5.5.6 Rest of Africa
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level Overview, Core Segments, Financials as available, Strategic Information, Market Rank or Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amazon.com Inc.
- 6.4.2 Netflix Inc.
- 6.4.3 MultiChoice Group Ltd.
- 6.4.4 Walt Disney Company (Disney+)
- 6.4.5 Apple Inc. (Apple TV+)
- 6.4.6 Canal+ Group (MyCanal)
- 6.4.7 PCCW Media Group (Viu)
- 6.4.8 iROKO Partners Ltd. (iROKOtv)
- 6.4.9 Google LLC (YouTube Premium)
- 6.4.10 MTN Group Ltd. (Ayoba)
- 6.4.11 Huawei Technologies Co. Ltd. (Huawei Video)
- 6.4.12 StarTimes Group (StarTimes ON)
- 6.4.13 Orange S.A. (Orange VOD)
- 6.4.14 StarTimes Media
- 6.4.15 Telkom SA SOC Ltd. (TelkomONE)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and unmet-need assessment


