|
시장보고서
상품코드
2120402
동남아시아의 석유 및 가스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Southeast Asia Oil And Gas - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
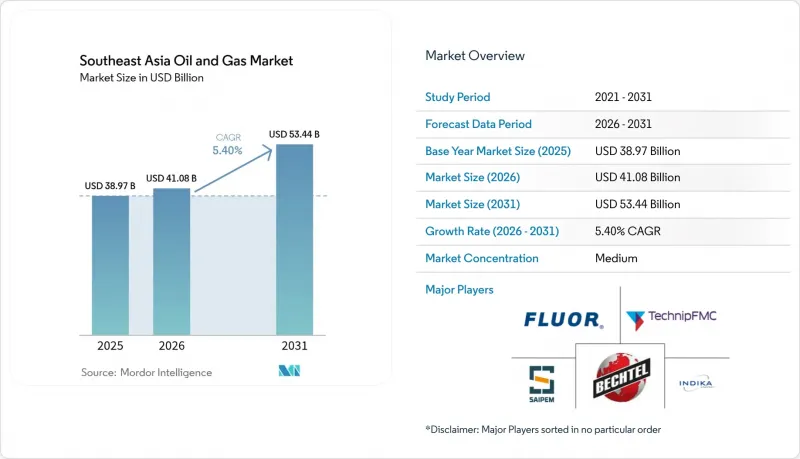
에 의하면, 동남아시아의 석유 및 가스 시장 규모는 2025년에 389억 7,000만 달러로 평가되었습니다. 2026년 410억 8,000만 달러에서 2031년까지 534억 4,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 5.40%를 나타낼 전망입니다.
본 보고서는 부문(업스트림, 중류, 하류), 위치(육상 및 해상), 서비스(건설, 유지보수·턴어라운드, 해체), 지역(인도네시아, 말레이시아, 태국, 베트남, 필리핀, 싱가포르, 미얀마 및 기타 동남아시아 국가)별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
동남아시아의 석유 및 가스 시장 동향 및 인사이트
팬데믹 이후 투자 회복이 업스트림 부문의 회복을 가속화
동남아시아의 업스트림 프로젝트에 대한 설비 투자는 사업자들이 연기되었던 탐사 및 개발 프로그램을 재개함에 따라 2024년에 34% 증가하여 285억 달러에 달했습니다. 페트로나스(PETRONAS)는 말레이시아 해양 사업에 82억 달러를 투자했고, PT 페르타미나(PT Pertamina)는 인도네시아 사업 확장에 47억 달러를 배정하여 수요 증가에 대한 신뢰가 회복되고 있음을 보여주고 있습니다. 그중 약 40%는 확인된 LNG 공급망에 투자되었으며, 말레이시아의 부유식 LNG(FLNG) 및 인도네시아의 육상 액화 시설이 가장 큰 수혜를 입고 있습니다. 이러한 급속한 지출로 인해 2020년부터 2022년에 걸쳐 연기되었던 프로젝트의 적체가 해소되었으며, 이 지역은 아시아 전역에 걸쳐 스윙 LNG 공급원으로서의 입지를 확고히 하고 있습니다. 실시간 저류층 분석 및 해저 타이백을 통해 투자 회수 기간이 단축되어 업스트림 부문에 대한 투자 의욕이 더욱 높아지고 있습니다.
에너지 안보의 필요성이 국내 자원 개발을 촉진
각국 정부는 수입 의존도를 낮추기 위한 노력을 강화하고 있습니다. 필리핀은 2024년에 30일 분공급량을 확보하는 전략적 석유 비축 프로그램을 시작했으며, 베트남은 가스 저장 용량을 25% 늘렸습니다. 태국의 PTT는 성숙한 유전의 생산량 감소를 상쇄하기 위해 태국만에서의 탐사 지출을 45% 증액했으며, 미얀마는 정치적 리스크가 있음에도 불구하고 12개의 신규 광구를 배정했습니다. 개정된 재정 조건-비용 회수 상한선 인상 및 가속 상각-으로 인해 프로젝트의 경제성이 향상되어 국내외 자본을 유치하고 있습니다. 이러한 노력은 변동성이 심한 세계 시장에서 공급의 회복력을 확보하려는 아세안 전체의 목표와 부합합니다.
기존 유전의 감산 속도가 매장량 보충 노력을 앞지르고 있습니다.
인도네시아 분지에서는 2024년에 연간 8-12%의 고갈률이 기록되어 세계 평균인 5-7%를 상회했습니다. 말레이시아의 노후화된 해양 자산은 생산량을 현재 수준으로 유지하기 위해 2026년까지 23억 달러의 유지 관리 비용이 필요하며, 이는 운영사의 현금 흐름에 부담을 주고 있습니다. 이 지역의 매장량 보충률은 0.7배로 하락하여, 신규 발견 건수가 불충분하다는 사실을 여실히 보여주고 있습니다. 인필 시추 및 증산 기술은 어디까지나 일시적인 구제책에 불과합니다. 운영사는 채굴 비용의 급등과 폐광 관련 부채 증가에 직면해 있으며, 이로 인해 자본 관리가 엄격해지고 프론티어 탐사가 지연될 우려가 있습니다.
부문별 분석
업스트림 부문의 활동은 2025년 수익의 72.15%를 차지했으며, 해당 부문은 2031년까지 연평균 5.67%의 성장이 예상되어 동남아시아의 석유 및 가스 시장에서 최대 점유율을 유지할 것으로 전망됩니다. 인도네시아의 아바디 LNG 및 말레이시아의 카사와리 가스 개발과 같은 대규모 프로젝트가 지출의 기반을 이루고 있는 반면, 새로운 생산량을 수송하기 위해 중류 부문의 네트워크도 병행하여 확대되고 있습니다. 다운스트림 생산 능력 증가는 배출 기준이 엄격해짐에 따라 신규 정유시설 건설이 억제되고 있어 뒤처지고 있습니다.
디지털 저류층 모델과 첨단 해저 처리 기술로 회수율이 향상되면서 업스트림 부문의 주도적 입지가 더욱 공고해지고 있습니다. 각국 정부는 에너지 안보 강화를 목적으로 국내 생산을 중시하고 있으며, 새로운 재정적 인센티브로 인해 자본은 정유시설 현대화보다는 탐사에 유입되는 경향을 보이고 있습니다. 증산 기술(EOR) 및 비전통 자원 시범 사업을 통해 업스트림 부문은 앞으로도 동남아시아의 석유 및 가스 산업의 최전선에 서 있을 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the Southeast Asia oil and gas market size was valued at USD 38.97 billion in 2025 and estimated to grow from USD 41.08 billion in 2026 to reach USD 53.44 billion by 2031, at a CAGR of 5.40% during the forecast period (2026-2031).
This report is Segmented by Sector (Upstream, Midstream, and Downstream), Location (Onshore and Offshore), Service (Construction, Maintenance and Turn-Around, and Decommissioning), and Geography (Indonesia, Malaysia, Thailand, Vietnam, Philippines, Singapore, Myanmar, and Rest of Southeast Asia). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Southeast Asia Oil And Gas Market Trends and Insights
Post-pandemic investment rebound accelerates upstream recovery
Capital spending on Southeast Asian upstream projects increased by 34% in 2024 to USD 28.5 billion, as operators reinstated delayed exploration and development programs. PETRONAS dedicated USD 8.2 billion to Malaysian offshore work, and PT Pertamina allocated USD 4.7 billion for Indonesian expansions, signaling restored confidence in demand growth. Approximately 40% of that is spent on targeted LNG supply chains, with Malaysia's floating LNG and Indonesia's onshore liquefaction benefiting most. The rapid outlays clear a project backlog dating from 2020-2022 deferrals and position the region as a swing LNG supplier for wider Asia. Real-time reservoir analytics and subsea tie-backs are compressing payback periods, further stimulating upstream commitments.
Energy-security imperatives drive domestic resource development
Governments are intensifying efforts to cut import dependence. The Philippines initiated a strategic petroleum reserve program in 2024, which provides 30 days of coverage, while Vietnam increased its gas storage capacity by 25%. Thailand's PTT boosted exploration spending 45% in the Gulf of Thailand to offset mature-field decline, and Myanmar awarded 12 new blocks despite political risks. Revised fiscal terms-higher cost-recovery ceilings and accelerated depreciation-have improved project economics, drawing both local and foreign capital. These actions align with broader ASEAN goals of supply resiliency amid volatile global markets.
Legacy field decline outpaces reserve-replacement efforts
Indonesian basins recorded 8-12% annual depletion in 2024, exceeding the global 5-7% norm.Malaysia's aging offshore assets need USD 2.3 billion of maintenance by 2026 to sustain plateau output, straining operator cash flow. The regional reserve-replacement ratio fell to 0.7 times, underscoring the insufficient number of discoveries. Infill drilling and enhanced recovery provide only tactical relief. Operators face steeper lift costs and heightened abandonment liabilities, which intensify capital discipline and can delay frontier exploration.
Other drivers and restraints analyzed in the detailed report include:
- LNG-terminal construction transforms regional gas infrastructure
- Biofuel integration pilots transform gas-network utilization
- Regulatory fragmentation creates investment uncertainty
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Upstream activities generated 72.15% of 2025 revenue, and the segment is projected to grow at a rate of 5.67% through 2031, maintaining its largest share of the Southeast Asia oil and gas market. Massive projects such as Indonesia's Abadi LNG and Malaysia's Kasawari gas development underpin spending, while midstream networks expand in tandem to evacuate new volumes. Downstream capacity growth lags because stricter emission standards curb new refinery builds.
Digital reservoir models and advanced subsea processing are elevating recovery factors, reinforcing upstream leadership. Governments favor domestic production to enhance energy security, and new fiscal incentives tend to direct capital toward exploration rather than refining upgrades. Enhanced oil recovery and unconventional resource pilots will keep the upstream segment at the forefront of the Southeast Asia oil and gas industry.
Complete Report Scope:
- By Sector
- Upstream
- Midstream
- Downstream
- By Location
- Onshore
- Offshore
- By Service
- Construction
- Maintenance and Turn-around
- Decommissioning
- By Geography
- Indonesia
- Malaysia
- Thailand
- Vietnam
- Philippines
- Singapore
- Myanmar
- Rest of Southeast Asia
List of Companies Covered in this Report:
- PETRONAS
- PT Pertamina Persero
- PTT Exploration & Production PLC
- ExxonMobil Corp.
- Shell PLC
- Chevron Corp.
- TotalEnergies SE
- Harbour Energy PLC
- ConocoPhillips
- BP PLC
- Sinopec Engineering Group
- TechnipFMC PLC
- Saipem SpA
- Bechtel Corp.
- Fluor Corp.
- John Wood Group PLC
- Petrofac Ltd.
- Samsung Engineering Co. Ltd.
- PT Indika Energy Tbk
- PT Rekayasa Industri
- PT Meindo Elang Indah
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Post-pandemic investment rebound in upstream & LNG supply chains
- 4.2.2 Energy-security push for domestic production & storage
- 4.2.3 Rapid build-out of LNG import terminals & regas capacity
- 4.2.4 CCS deployment unlocking high-CO2 gas fields
- 4.2.5 Biofuel / hydrogen blending pilots in existing gas networks
- 4.2.6 Digitalisation enabling marginal field commercialisation
- 4.3 Market Restraints
- 4.3.1 Declining legacy fields & reserve replacement gap
- 4.3.2 Regulatory & fiscal uncertainty across ASEAN members
- 4.3.3 ESG-driven capital flight from fossil assets
- 4.3.4 South China Sea maritime disputes delaying drilling
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Crude-Oil Production & Consumption Outlook
- 4.8 Natural-Gas Production & Consumption Outlook
- 4.9 Installed Pipeline Capacity Analysis
- 4.10 Unconventional Resources CAPEX Outlook (tight oil, oil sands, deep-water)
- 4.11 Porters Five Forces
- 4.11.1 Bargaining Power of Suppliers
- 4.11.2 Bargaining Power of Buyers
- 4.11.3 Threat of New Entrants
- 4.11.4 Threat of Substitutes
- 4.11.5 Industry Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Sector
- 5.1.1 Upstream
- 5.1.2 Midstream
- 5.1.3 Downstream
- 5.2 By Location
- 5.2.1 Onshore
- 5.2.2 Offshore
- 5.3 By Service
- 5.3.1 Construction
- 5.3.2 Maintenance and Turn-around
- 5.3.3 Decommissioning
- 5.4 By Geography
- 5.4.1 Indonesia
- 5.4.2 Malaysia
- 5.4.3 Thailand
- 5.4.4 Vietnam
- 5.4.5 Philippines
- 5.4.6 Singapore
- 5.4.7 Myanmar
- 5.4.8 Rest of Southeast Asia
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 PETRONAS
- 6.4.2 PT Pertamina Persero
- 6.4.3 PTT Exploration & Production PLC
- 6.4.4 ExxonMobil Corp.
- 6.4.5 Shell PLC
- 6.4.6 Chevron Corp.
- 6.4.7 TotalEnergies SE
- 6.4.8 Harbour Energy PLC
- 6.4.9 ConocoPhillips
- 6.4.10 BP PLC
- 6.4.11 Sinopec Engineering Group
- 6.4.12 TechnipFMC PLC
- 6.4.13 Saipem SpA
- 6.4.14 Bechtel Corp.
- 6.4.15 Fluor Corp.
- 6.4.16 John Wood Group PLC
- 6.4.17 Petrofac Ltd.
- 6.4.18 Samsung Engineering Co. Ltd.
- 6.4.19 PT Indika Energy Tbk
- 6.4.20 PT Rekayasa Industri
- 6.4.21 PT Meindo Elang Indah
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment