|
시장보고서
상품코드
2121678
이탈리아의 석유 및 가스 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Italy Oil And Gas - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
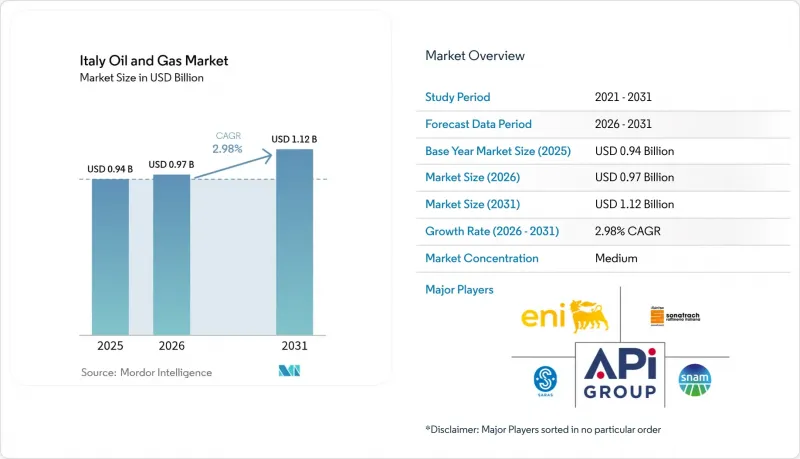
에 의하면, 이탈리아의 석유 및 가스 시장 규모는 2025년에 9억 4,000만 달러로 평가되었고, 2026년 9억 7,000만 달러에서 2031년까지 11억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 2.98%를 기록할 전망입니다.
본 보고서는 부문(업스트림, 미드스트림, 다운스트림), 지역(육상 및 해상), 서비스(건설, 유지보수·턴어라운드, 해체)별로 분류되어 있습니다. 시장 규모 및 예측치는 금액(달러)으로 표시되어 있습니다.
이탈리아의 석유 및 가스 시장 동향 및 인사이트
러시아산 가스 공급 위기에 따른 다각화 움직임
2021년에는 이탈리아 가스 공급량의 40%를 러시아가 차지했으나, 긴급 법안을 통해 LNG 터미널 프로젝트의 신속한 승인 및 알제리, 아제르바이잔과의 대체 파이프라인 계약이 가능해진 결과, 2024년까지 이 비중은 5% 미만으로 떨어졌습니다. 40억 유로 규모의 국가 안보 패키지를 통해 2기의 FSRU(부유식 저장 재기화 설비(FSRU))에 자금이 지원되었으며, 이를 합치면 연간 100억 m³공급 능력이 추가되어 공급 유연성이 강화되었습니다. 알제리로부터의 파이프라인 공급량은 2024년 수입량의 32%로 증가한 반면, 미국 및 카타르에서 새로운 LNG 화물이 피온비노와 라벤나에 도착하면서 중부 유럽의 가스 관문으로서 이탈리아의 역할이 확고해졌습니다. 2025년 겨울을 앞두고 저장 시설의 충전률이 90%를 넘어선 것은 회복력 향상을 여실히 보여주고 있으며, 중류 부문의 계약업체들은 압축 스테이션 및 계량 설비의 업그레이드가 가속화된 혜택을 누리고 있습니다. 공급망의 구조적 재편을 통해 이탈리아는 지중해 내 다양한 가스 흐름의 요충지로서의 입지를 공고히 했으며, 그 영향은 당면한 위기를 넘어 훨씬 더 멀리까지 미치고 있습니다.
발전용 천연가스 수요의 급증
석탄 화력 발전소의 폐쇄와 재생에너지의 간헐성으로 인해 신속한 출력 조정이 가능한 발전 용량의 필요성이 높아진 결과, 2024년 국내 발전량에서 가스 화력 발전소가 차지하는 비율은 2019년의 43%에서 48%로 상승했습니다. 복합 사이클 터빈의 효율 향상으로 한계 비용이 낮아짐에 따라, 특히 겨울철 피크 시간대-산업용 난방 수요가 증가하는 반면 태양광 발전 출력이 떨어지는 시기-에 가스는 우선적인 조정용 연료로 자리 잡고 있습니다. 풀리아주와 캄파니아주의 데이터센터에 대한 투자가 추가적인 베이스로드 수요를 견인하고 있으며, 개발업자들은 가격 변동 위험을 헤지하기 위해 장기 가스 공급 계약을 체결하는 사례가 늘고 있습니다. 이러한 동향으로 인해, 장기적인 탈탄소화 목표가 있음에도 불구하고 이탈리아의 석유 및 가스 시장의 추가 성장을 뒷받침할 중기적인 수요 하한선이 확립되었습니다.
재생에너지의 경쟁력 향상
2024년에는 태양광 및 풍력 발전 용량이 60GW에 달하고, 발전량의 35%를 공급하는 한편, 시칠리아 섬에서는 균등화 비용이 40유로/MWh를 달성했습니다. 계통 규모의 축전지 도입으로 시간 단위 변동이 완화되기 시작했으며, 주간 태양광 발전 피크 시간대의 가스 발전(피크 대응) 가동량이 감소하고 있습니다. ‘국가 부흥·복원력 계획’에서는 2026년까지 추가 재생에너지 원천에 150억 유로를 배정하고 있으며, 이는 전력 구성에서 가스에 대한 경쟁이 격화될 것임을 시사합니다. 그러나 계절적 변동성과 장기 저장 수단의 부재로 인해 유연성이 높은 가스 발전소는 여전히 예비 전원으로의 역할을 유지하고 있으며, 이탈리아의 석유 및 가스 시장에서 당면한 대체 위험은 완화되고 있습니다.
부문별 분석
미드스트림 사업은 2031년까지 연평균 성장률(CAGR) 4.27%를 나타낼 것으로 예측되며, 이는 이탈리아의 석유 및 가스 시장 내 다른 어떤 부문보다 빠른 속도입니다. Snam사의 81억 유로 규모의 자본 계획에는 1,200킬로미터의 수소 대응 파이프라인과 40억 입방미터 규모의 신규 저장 시설이 포함되어 있으며, 요금 제도에 기반한 수익과 더불어 이탈리아의 석유 및 가스 시장 내 미드스트림 서비스 시장 규모를 확대할 것입니다. 아드리아틱 라인(Adriatic Line)과 같은 국경을 넘는 상호 연결은 남북 간 유연성을 높이고, 수송 수익을 강화하며, 미래의 수소 혼합 연료에 대한 선택지를 창출합니다. 업스트림 부문은 여전히 최대의 수익원이지만, 생산량 증가세가 주춤하고 있어 서비스 제공업체들은 예측 가능하지만 수익 증가세가 완만한 유지보수 및 기존 시설 개선 프로젝트로 점차 전환하고 있습니다.
하류 부문에서도 견조한 전환 추세가 관찰됩니다. 바이오리파이너리는 기존 제품보다 높은 마진을 창출하는 프리미엄 연료를 공급함으로써, 유럽의 연료 규격 기준 강화로 인한 영향을 완화하고 있습니다. 따라서 이 부문은 양 중심 처리 방식에서 마진 중심의 특수 연료 생산으로 진화하고 있으며, 이러한 전환을 통해 이탈리아의 석유 및 가스 시장의 참여자들은 밸류체인 전반에 지속적으로 관여하는 동시에, 지속 가능한 사업 운영에 관한 EU의 택소노미 기준도 충족할 수 있게 됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the Italy oil and gas market size was valued at USD 0.94 billion in 2025 and estimated to grow from USD 0.97 billion in 2026 to reach USD 1.12 billion by 2031, at a CAGR of 2.98% during the forecast period (2026-2031).
This report is Segmented by Sector (Upstream, Midstream, and Downstream), Location (Onshore and Offshore), and Service (Construction, Maintenance and Turn-Around, and Decommissioning). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Italy Oil And Gas Market Trends and Insights
Diversification Push After Russian-Gas Supply Crisis
Russia supplied 40% of Italy's gas in 2021, but this share fell to under 5% by 2024, as emergency legislation enabled the rapid approval of LNG terminal projects and alternative pipeline deals with Algeria and Azerbaijan. The EUR 4 billion national security package funded two FSRUs, which together add 10 billion m3 of annual capacity, thereby strengthening supply flexibility. Algerian pipeline flows rose to 32% of 2024 imports, while new U.S. and Qatari LNG cargoes reached Piombino and Ravenna, anchoring Italy's role as a Central European gas gateway. Storage fill rates above 90% ahead of winter 2025 underscore improved resiliency, and midstream contractors benefit from accelerated compression-station and metering upgrades. The structural reshaping of supply chains solidifies Italy's position as the Mediterranean conduit for diversified gas flows, extending well beyond the immediate crisis horizon.
Surging Natural-Gas Demand for Power Generation
Gas-fired plants accounted for 48% of national electricity in 2024, up from 43% in 2019, as coal closures and renewable energy intermittency necessitated the need for fast-ramping capacity. Efficiency gains in combined-cycle turbines lowered marginal costs, making gas the preferred balancing fuel, especially during winter peaks when industrial heating coincides with subdued solar output. Data-center investments in Apulia and Campania drive additional baseload requirements, and developers are increasingly signing long-term gas supply contracts to hedge against price volatility. These dynamics establish a medium-term demand floor that supports further growth in Italy's oil and gas market, despite long-term decarbonization targets.
Accelerating Renewable-Energy Competitiveness
Solar and wind capacity reached 60 GW in 2024, supplying 35% of generation and achieving EUR 40/MWh levelized costs in Sicily. Grid-scale battery deployments begin to smooth hourly volatility, trimming gas peaker dispatch during midday solar peaks. The National Recovery and Resilience Plan allocates EUR 15 billion for additional renewable energy sources through 2026, signaling an intensification of competition for gas in the power mix. Yet seasonal variability and the absence of long-duration storage maintain a reserve role for flexible gas plants, mitigating immediate displacement risks for the Italy oil and gas market.
Other drivers and restraints analyzed in the detailed report include:
- LNG Import Expansion (Piombino & Ravenna FSRUs)
- Refinery Upgrades & Bio-Refinery Conversions
- Mature Domestic Reserves and Declining Production
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Midstream activities are projected to account for a 4.27% CAGR to 2031, a faster pace than any other sector within the Italian oil and gas market. Snam's EUR 8.1 billion capital plan includes 1,200 kilometers of hydrogen-ready pipelines and 4 billion cubic meters of new storage, expanding Italy's oil and gas market size for midstream services alongside tariff-backed earnings. Cross-border interconnections such as the Adriatic Line enhance north-south flexibility, reinforce transit revenue, and create optionality for future hydrogen blends. Upstream remains the largest revenue source but faces plateauing production volumes, prompting service providers to shift toward maintenance and brownfield enhancement projects that generate predictable, albeit slower, revenue streams.
A robust downstream conversion trend also manifests. Bio-refineries supply premium fuels that fetch higher margins than traditional products, moderating the impact of tightening European fuel-spec standards. The sector therefore evolves from volume-driven processing to margin-driven specialty fuels, a shift that keeps Italy oil and gas market players engaged across the full value chain while meeting EU taxonomy criteria for sustainable operations.
Complete Report Scope:
- By Sector
- Upstream
- Midstream
- Downstream
- By Location
- Onshore
- Offshore
- By Service
- Construction
- Maintenance and Turn-around
- Decommissioning
List of Companies Covered in this Report:
- Eni SpA
- Snam SpA
- Saras SpA
- Sonatrach Raffineria Italiana Srl
- API Anonima Petroli Italiana SpA
- Edison SpA
- TotalEnergies SE
- Shell PLC
- BP PLC
- Saipem SpA
- Maire SpA
- Italgas SpA
- Engie SA (Italy)
- GOI Energy (ISAB Priolo)
- Raffineria di Milazzo ScpA
- SGS Italia SpA
- Zenith Energy Ltd
- Schlumberger NV
- Baker Hughes Italy Srl
- ERG SpA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging natural-gas demand for power generation
- 4.2.2 Diversification push after Russian-gas supply crisis
- 4.2.3 Refinery upgrades & bio-refinery conversions
- 4.2.4 LNG import expansion (Piombino & Ravenna FSRUs)
- 4.2.5 Offshore CO?-storage hubs enabling blue-hydrogen clusters
- 4.2.6 Growth in small-scale LNG bunkering for Adriatic shipping
- 4.3 Market Restraints
- 4.3.1 Accelerating renewable-energy competitiveness
- 4.3.2 Mature domestic reserves & declining production
- 4.3.3 Strict offshore drilling moratoria & seismic rules
- 4.3.4 Slow permitting for midstream expansions
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Crude-Oil Production & Consumption Outlook
- 4.8 Natural-Gas Production & Consumption Outlook
- 4.9 Installed Pipeline Capacity Analysis
- 4.10 Unconventional Resources CAPEX Outlook (tight oil, oil sands, deep-water)
- 4.11 Porter's Five Forces
- 4.11.1 Bargaining Power of Suppliers
- 4.11.2 Bargaining Power of Buyers
- 4.11.3 Threat of New Entrants
- 4.11.4 Threat of Substitutes
- 4.11.5 Industry Rivalry
- 4.12 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Sector
- 5.1.1 Upstream
- 5.1.2 Midstream
- 5.1.3 Downstream
- 5.2 By Location
- 5.2.1 Onshore
- 5.2.2 Offshore
- 5.3 By Service
- 5.3.1 Construction
- 5.3.2 Maintenance and Turn-around
- 5.3.3 Decommissioning
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Eni SpA
- 6.4.2 Snam SpA
- 6.4.3 Saras SpA
- 6.4.4 Sonatrach Raffineria Italiana Srl
- 6.4.5 API Anonima Petroli Italiana SpA
- 6.4.6 Edison SpA
- 6.4.7 TotalEnergies SE
- 6.4.8 Shell PLC
- 6.4.9 BP PLC
- 6.4.10 Saipem SpA
- 6.4.11 Maire SpA
- 6.4.12 Italgas SpA
- 6.4.13 Engie SA (Italy)
- 6.4.14 GOI Energy (ISAB Priolo)
- 6.4.15 Raffineria di Milazzo ScpA
- 6.4.16 SGS Italia SpA
- 6.4.17 Zenith Energy Ltd
- 6.4.18 Schlumberger NV
- 6.4.19 Baker Hughes Italy Srl
- 6.4.20 ERG SpA
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment