

|
시장보고서
상품코드
2122228
그래픽 프로세서 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Graphic Processors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 그래픽 프로세서 시장 규모는 2025년 734억 6,000만 달러로 평가되었고, 2026년 750억 8,000만 달러에서 2031년까지 1,170억 1,000만 달러로 확대될 전망이며, 2026-2031년 CAGR 9.28%를 나타낼 것으로 예측됩니다.
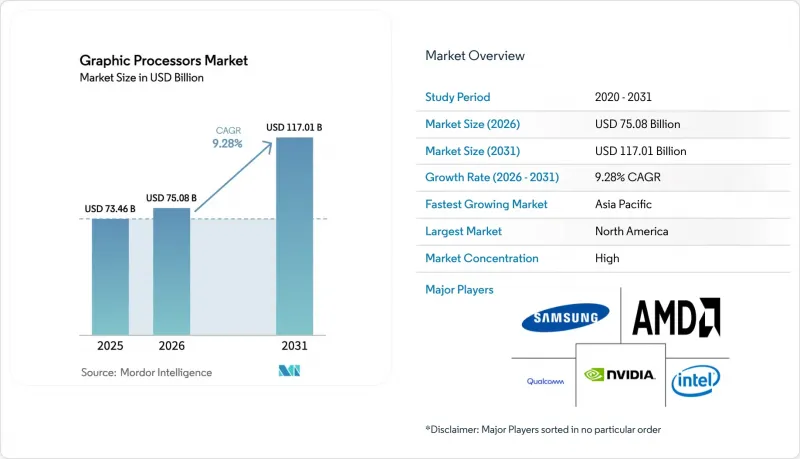
본 보고서는 GPU 유형별(전용, 통합형, 하이브리드, 외부), 도입 모델별(온프레미스, Cloud-As-A-Service), 디바이스 플랫폼별(스마트폰, 태블릿, 게이밍 PC 및 게임기 등), 최종 사용자 산업별(소비자 가전, IT 및 통신, 기타), GPU 아키텍처별(x86, ARM, RISC-V, 독자 사양), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 그래픽 프로세서 시장 동향 및 인사이트
AAA급 게임 및 실시간 레이 트레이싱에 대한 수요 급증
실시간 레이 트레이싱은 이제 기본적인 요구 사항이 되었으며, 주요 벤더들은 다이 면적의 최대 절반을 4K 해상도에서 초당 60프레임 출력을 유지하는 레이 트라이앵글 교차 연산 유닛에 할당하고 있습니다. 2025년 게임기 세대 교체를 계기로 2세대 레이 트레이싱 코어가 도입되고 성능의 최저 기준이 상향 조정됨에 따라, 2027년까지 디스크리트 GPU 로드맵은 네이티브 8K 렌더링을 향해 추진되고 있습니다. e스포츠 스튜디오에서는 아티스트의 작업 부담을 줄이기 위해 패스 트레이싱을 통한 세계 일루미네이션을 채택하고 있으며, 이로 인해 래스터라이즈 파이프라인에 비해 연산 요구 사항이 3배로 증가하여 400-700달러 가격대의 미드티어 부문이 확대되고 있습니다. 구독형 클라우드 게임 플랫폼에서는 50밀리초 미만의 지연 시간을 유지하기 위해 동시 접속 사용자 1명당 1.2개의 GPU를 할당하게 되었습니다(2024년의 0.8개에서 증가). 이로 인해 하이퍼스케일 GPU 풀용 하이엔드 제품공급이 부족해지고 있습니다. 2025년에는 프리미엄 스마트폰에 하이브리드 레이 트레이싱 블록이 탑재되면서, 플래그십 모델의 GPU 탑재율이 전년 대비 18% 상승했습니다.
AI/딥러닝 워크로드의 급증
2025년에는 프론티어 모델 훈련 시 부동소수점 연산 횟수가 10^25회를 초과했으며, 400 Gb/s 패브릭을 통해 연결된 1만 6,384개의 가속기를 갖춘 클러스터가 90일 이내에 처리를 완료하게 되었습니다. 추론은 배치 처리에서 실시간 스트림으로 전환되고 있으며, 범용 벡터 유닛보다 INT8 및 FP16에 최적화된 텐서 코어가 선호되고 있습니다. 병원에서는 50-100곳의 거점에 페더레이티드 러닝 프레임워크를 도입하고, 개인정보를 보호하면서 진단을 수행하기 위해 거점당 필요한 GPU 대수를 2대에서 8대로 늘렸습니다. 자동차 제조업체는 무선 업데이트(OTA)를 지원하기 위해 초당 200테라오퍼레이션의 처리량을 가진 차량용 모듈을 탑재하여 부품 원가를 800-1,200달러 증가시키는 한편, 프리미엄 등급의 세분화를 강화했습니다. 정량 거래 부문은 GPU 기반 강화 학습을 통해 전략 개발 주기를 6개월에서 3주로 단축했으며, 이로 인해 2025년 그래픽 프로세서 시장에서의 도입이 22% 증가할 것으로 전망됩니다.
첨단 노드(5nm 이하)공급 병목 현상
2025년에도 5nm 이하 파운드리 생산 능력은 여전히 핍박한 상태가 지속되었습니다. TSMC가 N3 공정의 웨이퍼 생산량의 60%를 스마트폰용 프로세서에 할당함에 따라, GPU 대량 주문의 리드타임은 26주로 늘어났습니다. 삼성의 3nm 공정 수율은 70% 전후로 유지되며 비용 경쟁력 기준치를 밑돌았기 때문에 와트당 성능이 20% 낮은 5nm 노드로 전환할 수밖에 없었습니다. 인텔의 애리조나 공장 양산 개시는 6개월 지연되었고, 미국 설계 회사를 위한 국내 생산 능력 확보가 늦어지면서 대만 제조에 대한 의존이 장기화되었습니다. 듀얼 소싱 확대에는 12-18개월의 공정 공동 개발이 필요하여, 단기적인 공급원 다각화를 제한하고 있습니다. 웨이퍼 가격의 8% 상승은 이익률 압박을 더욱 심화시켜, 그래픽 프로세서 시장에서의 적극적인 확장을 억제했습니다.
부문별 분석
2025년, 그래픽 프로세서 시장에서 전용 디스크리트 보드는 40.22%의 점유율을 유지했습니다. 이는 유지보수 기간을 간소화하는 핫스왑 지원 데이터센터용 카드가 주도한 결과입니다. 하이브리드 가속기는 PCIe 병목 현상을 해소하고 시스템 전력 소비를 25-30% 절감하는 통합 메모리에 대한 수요를 배경으로 연평균 성장률(CAGR) 9.83%를 나타낼 것으로 예측됩니다. 통합형 GPU는 열 설계에 제약이 있는 노트북 시장에서 계속해서 지배적인 위치를 차지하고 있는 반면, 외부 인클로저는 일시적인 성능 향상을 원하는 모바일 크리에이터를 타겟으로 하고 있습니다. 다만, 썬더볼트의 대역폭 상한으로 인해 활용도가 70-80%로 제한된다는 과제를 안고 있습니다.
칩렛 기반 하이브리드 제품은 3nm CPU 코어와 5nm GPU 타일을 결합하여 수율과 비용의 균형을 맞추면서도 경쟁사 수준의 처리량을 유지하고 있습니다. 디스크리트 추론 보드에는 스파스성 엔진이 도입되어, 면적 증가 없이 트랜스포머 모델의 유효 처리량을 최대 60% 향상시켰습니다. 외부 GPU 생태계에서는 썬더볼트 5의 제약을 극복하기 위해 독자적인 커넥터 채택이 모색되고 있습니다.
온프레미스 부문은 지연 시간에 민감한 워크로드와 주권적 워크로드가 여전히 로컬 클러스터에 묶여 있었기 때문에 2025년 그래픽 프로세서 시장 매출의 72.91%를 차지했습니다. ‘서비스형 클라우드(Cloud-as-a-Service)’는 딥러닝 실험 및 버스트 용량 활용을 촉진하는 초 단위 과금 체계에 힘입어 연평균 10.02%의 성장이 예상됩니다. 금융 및 의료 분야의 사업자들은 규정 준수상의 이유로 주요 훈련을 온프레미스에서 수행하면서, 피크 부하를 코로케이션 지역으로 분산함으로써 하이브리드 오케스트레이션에 대한 수요를 창출하고 있습니다.
스팟 GPU 가격은 존(zone) 간에 50-80%의 편차가 나타나며, 워크로드 스케줄러는 비용 최적화를 위해 작업 이전을 추진하고 있습니다. 하드웨어 교체 주기가 3.2년에서 4.5년으로 연장된 것은 신중한 설비 투자와 소프트웨어 측면의 효율화 진전을 반영합니다. 예약 용량 계약에는 35-45%의 할인이 적용되지만, 새로운 칩이 시장에 출시될 경우 고객은 세대 락인(generation lock-in) 위험에 노출될 수 있습니다.
지역별 분석
북미는 2025년 매출의 37.81%를 차지했으며, 버지니아주, 오리건주, 텍사스주의 하이퍼스케일 시설 확장이 주요 견인 역할을 했습니다. 이 지역들은 전 세계 하이엔드 제품 출하량의 절반 이상을 차지하고 있습니다. 아시아태평양은 국산 실리콘과 현지화된 모델 훈련을 우선시하는 중국 및 인도의 국가 주도 AI 프로그램에 힘입어 연평균 성장률(CAGR) 11.52%로 확대될 것으로 예측됩니다. 유럽에서는 에너지 요금 급등으로 운영비가 18-22% 증가함에 따라 그래픽 프로세서 시장의 리프레시가 연기되면서 완만한 성장에 그쳤습니다.
중동에서는 AI 프리존 구축을 위한 투자가 이루어졌으며, 아랍에미리트(UAE)와 사우디아라비아는 아랍어 LLM(대규모 언어 모델)을 구축하기 위해 1만 대 이상의 가속기로 구성된 클러스터를 가동했습니다. 아프리카와 남미의 합산 기여도는 5% 미만에 그쳤으나, 브라질, 나이지리아, 남아프리카공화국에서는 통신 사업자의 대출 확대에 따라 스마트폰의 GPU 탑재율이 25-30% 상승했습니다.
중국에서는 고대역폭 상호 연결에 관한 규제로 인해 수입이 12% 감소했으며, 이에 따라 알리바바의 ‘T-Head’와 ‘Biren’에서는 2025년 말까지 NVIDIA A100 성능의 70-80%를 달성하기 위한 국내 개발이 진행되고 있습니다. 일본은 미국의 클라우드 서비스에 의존하지 않고 언어 모델을 학습시키기 위해, 총 1만 5,000대의 GPU를 보유한 국가 AI 클러스터에 23억 달러를 배정했습니다. 인도의 반도체 인센티브 정책은 18억 달러의 투자 약속을 이끌어냈지만, 프런트엔드 팹이 가동을 시작하기까지는 아직 3년이 더 걸립니다. 독일과 프랑스는 GPU 연구개발 프로젝트에 공동 투자했으나, 전력 효율 측면에서는 시판 제품보다 18-24개월 뒤처져 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the graphic processors market size is projected to expand from USD 73.46 billion in 2025 and USD 75.08 billion in 2026 to USD 117.01 billion by 2031, registering a CAGR of 9.28% between 2026 to 2031.
This report is Segmented by GPU Type (Dedicated, Integrated, Hybrid, and External), Deployment Model (On-Premise, and Cloud-As-A-Service), Device Platform (Smartphones, Tablets, Gaming PCs and Consoles, and More), End-User Industry (Consumer Electronics, IT and Telecom, and More), GPU Architecture (x86, ARM, RISC-V, and Proprietary), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Graphic Processors Market Trends and Insights
Surging Demand for AAA Gaming and Real-Time Ray Tracing
Real-time ray tracing has become a baseline expectation, leading vendors to devote up to half of the die area to ray-triangle intersection units that sustain 60 frames-per-second output at 4K resolution. Console refreshes in 2025 injected second-generation ray-tracing cores, lifting the performance floor and pushing discrete GPU roadmaps toward native 8K rendering by 2027. Esports studios are adopting path-traced global illumination to curb artist workloads, tripling compute requirements over raster pipelines and expanding the mid-tier segment priced between USD 400 and USD 700. Subscription cloud gaming platforms now reserve 1.2 GPUs per concurrent user to preserve sub-50-millisecond latency, up from 0.8 in 2024, tightening high-end supply for hyperscale GPU pools. Premium smartphones integrated hybrid ray-tracing blocks in 2025, lifting flagship handset GPU attach rates by 18% year over year.
Proliferation of AI/Deep Learning Workloads
Frontier model training exceeded 10^25 floating-point operations in 2025, prompting clusters with 16,384 accelerators linked via 400 Gb/s fabrics to complete runs within 90 days. Inference is moving from batch to real-time streams, favoring tensor cores optimized for INT8 and FP16 over generic vector units. Hospitals deployed federated learning frameworks across 50-100 sites, raising per-site GPU needs from 2 to 8 units for privacy-preserving diagnostics. Automakers fitted on-vehicle modules with 200-tera-operations-per-second throughput to support over-the-air updates, adding USD 800-USD 1,200 to bill-of-materials and reinforcing premium-trim segmentation. Quantitative trading desks cut strategy development cycles from 6 months to 3 weeks through GPU-based reinforcement learning, triggering 22% deployment growth in 2025 in the graphic processors market.
Advanced-Node Supply Bottlenecks (<=5 nm)
Foundry capacity at 5 nm and below remained tight in 2025, as TSMC allocated 60% of N3 wafer starts to smartphone processors, pushing GPU lead times to 26 weeks for volume orders. Samsung's 3 nm yields hovered near 70%, below cost-competitive thresholds, forcing fallback to 5 nm nodes at 20% lower performance per watt. Intel's Arizona ramp slipped six months, delaying domestic capacity for U.S. designers and prolonging reliance on Taiwan fabrication. Dual-sourcing expansions require 12-18 months of process-co-development, limiting near-term diversification. Wafer price inflation of 8% compounded margin compression and curbed aggressive expansion in the graphic processors market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Cloud Gaming and GPU-as-a-Service
- Chiplet and Advanced Packaging Breakthroughs
- High ASPs Limiting Mainstream Adoption
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dedicated discrete boards retained a 40.22% stake in 2025 in the graphic processors market, driven by hot-swappable data center cards that simplify maintenance windows. Hybrid accelerators are forecast to grow at a 9.83% CAGR amid demand for unified memory that eliminates PCIe bottlenecks and cuts system power by 25-30%. Integrated GPUs continue to dominate thermally constrained laptops, whereas external enclosures target mobile creatives seeking episodic boosts but are hampered by Thunderbolt bandwidth ceilings that cap utilization at 70-80%.
Chiplet-based hybrids combine 3 nm CPU cores with 5 nm GPU tiles, balancing yield and cost while sustaining competitive throughput. Discrete inference boards introduced sparsity engines that raise effective throughput by up to 60% on transformer models without area penalties. External GPU ecosystems are exploring proprietary connectors to overcome Thunderbolt 5 constraints.
The on-premise segment captured 72.91% of 2025 revenue in the graphic processors market, as latency-sensitive or sovereign workloads remained tethered to local clusters. Cloud-as-a-service is projected to grow 10.02% annually, driven by second-based billing that attracts deep learning experimentation and burst capacity. Financial and healthcare operators keep primary training on site for compliance but burst peak loads to co-located regions, creating hybrid orchestration demand.
Spot GPU prices have varied by 50-80% across zones, prompting workload schedulers to migrate jobs to optimize costs. Lengthening hardware refresh cycles from 3.2 to 4.5 years reflects cautious capital expenditure and software-side efficiency gains. Reserved-capacity contracts offer 35-45% discounts but expose clients to generation-lock-in risk as new silicon lands.
Complete Report Scope:
- By GPU Type
- Dedicated (Discrete) GPUs
- Integrated GPUs
- Hybrid GPUs (APUs)
- External GPUs (eGPU Enclosures)
- By Deployment Model
- On-Premise
- Cloud-as-a-service
- By Device Platform
- Smartphones
- Tablets
- Gaming PCs and Consoles
- Workstations
- Data-center Servers
- Automotive Infotainment and ADAS
- By End-User Industry
- Consumer Electronics
- IT and Telecom
- Media and Entertainment
- Automotive
- Defense and Intelligence
- Healthcare and Life Sciences
- By GPU Architecture
- x86-based GPUs
- ARM-based GPUs
- RISC-V-based GPUs
- Proprietary/Other ISAs
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America contributed 37.81% of 2025 revenue, driven by hyperscale build-outs in Virginia, Oregon, and Texas, which accounted for over half of global high-end shipments. Asia-Pacific is projected to expand at an 11.52% CAGR, underpinned by sovereign-AI programs in China and India that prioritize domestic silicon and localized model training. Europe registered moderate growth, as energy tariffs inflated operating expenses by 18-22%, prompting delays in refreshes in the graphic processors market.
Middle East investments established AI-free zones, where the United Arab Emirates and Saudi Arabia commissioned clusters of more than 10,000 accelerators to build Arabic LLMs. Africa and South America contributed under 5% combined, though smartphone GPU attachment in Brazil, Nigeria, and South Africa rose 25-30% with carrier financing expansion.
China's imports fell 12% after high-bandwidth interconnect restrictions, prompting domestic efforts at Alibaba's T-Head and Biren to achieve 70-80% of NVIDIA A100 performance by late-2025. Japan allocated USD 2.3 billion to national AI clusters totaling 15,000 GPUs to train language models without relying on U.S. cloud services. India's semiconductor incentive attracted USD 1.8 billion commitments, though front-end fabs remain three years out. Germany and France co-funded GPU R&D projects but trailed commercial offerings by 18-24 months in power efficiency.
- NVIDIA Corporation
- Advanced Micro Devices, Inc.
- Intel Corporation
- Samsung Electronics Co., Ltd.
- Qualcomm Incorporated
- Apple Inc.
- Arm Ltd.
- Imagination Technologies Limited
- MediaTek Inc.
- VIA Technologies, Inc.
- Taiwan Semiconductor Manufacturing Company Limited
- IBM Corporation
- Sony Group Corporation
- Graphcore Limited
- Tenstorrent Inc.
- ZOTAC Technology Limited
- Micro-Star International Co., Ltd.
- ASUSTeK Computer Inc.
- Giga-Byte Technology Co., Ltd.
- EVGA Corporation
- Blaize, Inc.
- Cerebras Systems Inc.
- Alibaba Group Holding Limited (T-Head)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Demand For AAA Gaming and Real-Time Ray Tracing
- 4.2.2 Proliferation Of AI/Deep Learning Workloads
- 4.2.3 Expansion Of Cloud Gaming and GPU-As-A-Service
- 4.2.4 Chiplet and Advanced Packaging Breakthroughs
- 4.2.5 Govt-Backed Exascale Supercomputing Programs
- 4.2.6 Arm/Risc-V Automotive-Grade Custom GPUs
- 4.3 Market Restraints
- 4.3.1 Advanced-Node Supply Bottlenecks (Less than or Equal to 5 Nm)
- 4.3.2 High ASPs Limiting Mainstream Adoption
- 4.3.3 Export Controls On High-End GPUs
- 4.3.4 Thermal Envelope (Greater than 600 W) Deployment Limits
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By GPU Type
- 5.1.1 Dedicated (Discrete) GPUs
- 5.1.2 Integrated GPUs
- 5.1.3 Hybrid GPUs (APUs)
- 5.1.4 External GPUs (eGPU Enclosures)
- 5.2 By Deployment Model
- 5.2.1 On-Premise
- 5.2.2 Cloud-as-a-service
- 5.3 By Device Platform
- 5.3.1 Smartphones
- 5.3.2 Tablets
- 5.3.3 Gaming PCs and Consoles
- 5.3.4 Workstations
- 5.3.5 Data-center Servers
- 5.3.6 Automotive Infotainment and ADAS
- 5.4 By End-User Industry
- 5.4.1 Consumer Electronics
- 5.4.2 IT and Telecom
- 5.4.3 Media and Entertainment
- 5.4.4 Automotive
- 5.4.5 Defense and Intelligence
- 5.4.6 Healthcare and Life Sciences
- 5.5 By GPU Architecture
- 5.5.1 x86-based GPUs
- 5.5.2 ARM-based GPUs
- 5.5.3 RISC-V-based GPUs
- 5.5.4 Proprietary/Other ISAs
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 ASEAN
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 NVIDIA Corporation
- 6.4.2 Advanced Micro Devices, Inc.
- 6.4.3 Intel Corporation
- 6.4.4 Samsung Electronics Co., Ltd.
- 6.4.5 Qualcomm Incorporated
- 6.4.6 Apple Inc.
- 6.4.7 Arm Ltd.
- 6.4.8 Imagination Technologies Limited
- 6.4.9 MediaTek Inc.
- 6.4.10 VIA Technologies, Inc.
- 6.4.11 Taiwan Semiconductor Manufacturing Company Limited
- 6.4.12 IBM Corporation
- 6.4.13 Sony Group Corporation
- 6.4.14 Graphcore Limited
- 6.4.15 Tenstorrent Inc.
- 6.4.16 ZOTAC Technology Limited
- 6.4.17 Micro-Star International Co., Ltd.
- 6.4.18 ASUSTeK Computer Inc.
- 6.4.19 Giga-Byte Technology Co., Ltd.
- 6.4.20 EVGA Corporation
- 6.4.21 Blaize, Inc.
- 6.4.22 Cerebras Systems Inc.
- 6.4.23 Alibaba Group Holding Limited (T-Head)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


