|
시장보고서
상품코드
2124533
미국의 데이터센터 건설 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)United States Data Center Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 미국의 데이터센터 건설 시장 규모는 2025년에 143억 5,000만 달러로 평가되었습니다. 2026년 155억 1,000만 달러에서 2031년까지 237억 4,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) 기간 중, CAGR 8.89%로 성장한다고 추정되고 있습니다.
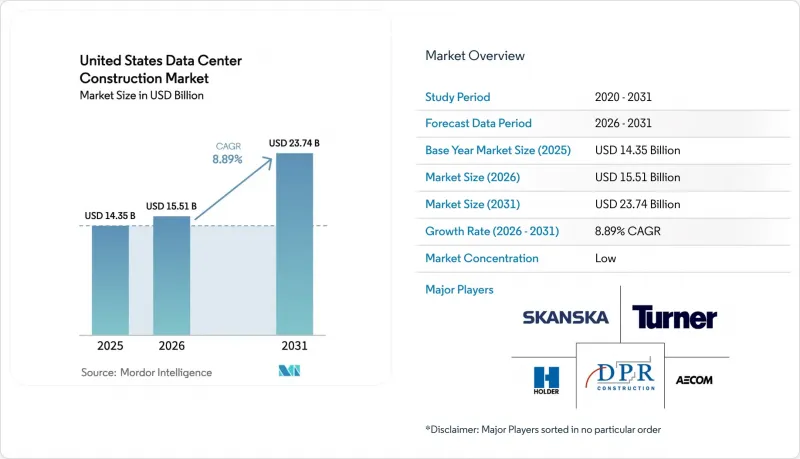
본 보고서는 티어 유형(Tier 1·2, Tier 3, 티어 4), 데이터센터 규모(소규모, 중규모, 대규모, 하이퍼스케일), 데이터센터 유형(코로케이션, 하이퍼스케일러/클라우드 서비스 제공업체, 엔터프라이즈·엣지),인프라(전기, 기계, 종합 건설, 서비스)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
미국의 데이터센터 건설 시장 동향 및 인사이트
클라우드, AI, 빅데이터 워크로드의 급증
생성형 AI 추론 클러스터로 인해 평균 랙 부하가 2배로 증가하며, 설계 밀도는 2026년에 15kW에 도달하고 2028년까지 25kW에 이를 것으로 예측됩니다. 사업자들은 리어 도어 방식의 열교환기 및 직접 투 칩 루프(Direct-to-Chip Loop) 개조를 추진하고 있으며, 이로 인해 예산은 1메가와트당 150만-200만 달러 증가하고 있습니다. 아마존 웹 서비스(AWS)는 펜실베이니아 주 거점에 110억 달러를 투자하고, 마이크로소프트는 AI에 최적화된 캠퍼스를 위해 전 세계적으로 800억 달러를 확보하고 있는데, 이는 하이퍼스케일러들의 자본 재분배를 보여줍니다. 전 세계 하이퍼스케일 시설의 절반 이상이 미국에 집중되어 있기 때문에 수요는 훈련용 100메가와트 규모의 캠퍼스와 저지연 추론용 1메가와트 미만의 엣지 노드 사이에서 양극화되고 있습니다.
10기가와트를 초과하는 하이퍼스케일 자체 건설 파이프라인
Amazon Web Services, Microsoft Azure, Google Cloud, Meta 등 4개사는 총 10기가와트를 초과하는 진행 중인 프로젝트를 보유하고 있습니다. 메타는 루이지애나주에 100억 달러 규모의 캠퍼스를 건설할 것을 확정했으며, 구글도 텍사스주 확장 계획에 10억 달러를 추가로 투입했습니다. 이는 토지 및 전력망 연결 비용이 Tier 1 허브에 비해 최대 60% 저렴한 2차 시장으로의 이동을 시사합니다. 각 하이퍼스케일러 기업들은 현재 토목 공사를 자체적으로 수행하고, 기계·전기 분야 전문가를 고용하여 공사 기간을 24개월에서 18개월로 단축하고 있으며, 이로 인해 종합 건설사가 확보할 수 있는 가치를 약 25% 줄이고 있습니다.
전력망 연결 지연(3-6년)
전미의 대기 목록은 2,600기가와트를 초과하며, 승인까지 걸리는 기간의 중앙값은 5년에 달할 전망입니다. 도미니언 에너지(Dominion Energy) 한 곳만 해도 버지니아주 북부에서 47기가와트 규모의 데이터센터 수요가 보류 중입니다. 애리조나 퍼블릭 서비스(Arizona Public Service)는 2024년 하반기에 신규 데이터센터의 전력망 연결 신청을 동결하고, 프로젝트를 텍사스주와 오하이오주로 전환하고 있습니다. 개발업체들은 1메가와트당 300만-500만 달러의 추가 비용이 드는 대기 목록의 위험을 피할 수 있는 현장 피크 발전소나 소형 모듈형 원자로에 대한 자금 지원을 추진하고 있습니다. 한편, 2027년에 예정된 연방에너지규제위원회(FERC)의 개혁은 승인 절차의 효율화를 목표로 하고 있습니다.
부문별 분석
2025년에는 Tier 3 사이트가 56.43%의 점유율을 차지했습니다. 이는 티어 4 설계에 비해 20%-30%의 비용 절감이 가능하며, 동시 유지보수성이 높다는 점에서 지지를 받고 있습니다. 그러나 내결함성을 갖춘 티어 4 시설은 연평균 성장률(CAGR) 9.12%로 성장을 지속하고 있으며, 이는 미국의 데이터센터 건설 시장에서 가장 높은 성장률입니다. 은행, 의료, 정부 기관 등의 입주사는 99.995%의 가동률을 요구하고 있으며, 이에 따라 코로케이션 사업자들은 Tier 3 시설에 이중 유틸리티 공급 라인과 2N 구성의 무정전 전원 장치(UPS) 랙을 도입하는 개보수를 진행하고 있습니다. 업타임 인스티튜트(Uptime Institute)의 2024년 조사에 따르면, 미국 건설 프로젝트의 38%가 티어 4 인증을 획득했으며, 이는 2022년의 29%에서 증가한 수치입니다. 이러한 급증의 한 가지 요인은 사이버 보험 인수사의 지원입니다.
코로케이션 업계의 선두주자인 에퀴닉스(Equinix)와 디지털 리얼티(Digital Realty)는 프리미엄 워크로드를 확보하기 위해 기존 캠퍼스에 티어 4 기능을 단계적으로 도입하고 있습니다. 한편, 아마존 웹 서비스(AWS)는 GovCloud 고객을 지원하기 위해 110억 달러 규모의 펜실베이니아주 프로그램에 여러 개의 Tier 4 캠퍼스를 포함시켰습니다. 내결함성 호스팅을 요구하는 기업이 늘어남에 따라, 중복된 전력 경로와 액체 냉각식 백업 모듈에 주력하는 계약업체들이 Tier 4 관련 지출에서 가장 큰 점유율을 차지할 전망입니다.
10메가와트를 초과하는 하이퍼스케일 캠퍼스는 2025년 건설량의 64.31%를 차지했으며, 연평균 9.45%의 성장률이 예상되어 미국의 데이터센터 건설 시장에서 그 중요성이 부각되고 있습니다. 전력 조달, 모듈식 냉각 및 인건비 측면에서의 규모의 경제로 인해 중규모 시설에 비해 1메가와트당 비용이 최대 40% 절감되므로, 클라우드 제공업체들은 100-200메가와트 규모의 종합 계획형 사이트를 선호하는 추세입니다.
1메가와트에서 10메가와트 규모의 중규모 시설은 여전히 하이브리드 코로케이션 테넌트에 의해 이용되고 있지만, 워크로드가 클라우드로 이전됨에 따라 성장 속도는 둔화되고 있습니다. 1메가와트 미만의 소규모 시설은 폐쇄되는 엔터프라이즈 룸과 증가 추세에 있는 엣지 노드, 이 두 가지로 나뉩니다. 광대역에 대한 보조금과 5G의 고밀도화로 인해 Tier 2 도시나 지방 도시권에서도 엣지 시설 건설이 경제적으로 실현 가능해졌으며, 이 틈새 시장에서는 모텐슨(Mortenson)이나 발포어 비티(Balfour Beatty)와 같은 모듈식 전문 기업들이 45일 이내에 턴키 방식의 인클로저를 제공합니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the United States (US) data center construction market size was valued at USD 14.35 billion in 2025 and is estimated to grow from USD 15.51 billion in 2026 to reach USD 23.74 billion by 2031, at a CAGR of 8.89% during the forecast period (2026-2031).
This report is Segmented by Tier Type (Tier 1 and 2, Tier 3, and Tier 4), Data Center Size (Small, Medium, Large, and Hyperscale), Data Center Type (Colocation, Hyperscalers/Cloud Service Providers, and Enterprise and Edge), Infrastructure (Electrical, Mechanical, General Construction, and Services). The Market Forecasts are Provided in Terms of Value (USD).
United States Data Center Construction Market Trends and Insights
Cloud, AI and Big-Data Workload Boom
Generative AI inference clusters have doubled average rack loads, pushing design densities to 15 kilowatts in 2026 and an expected 25 kilowatts by 2028. Operators are retrofitting rear-door heat exchangers and direct-to-chip loops, which add USD 1.5 million to USD 2 million per megawatt to budgets. Amazon Web Services committed USD 11 billion to Pennsylvania sites, and Microsoft reserved USD 80 billion globally for AI-optimized campuses, illustrating hyperscaler capital redeployment. With the United States hosting more than half of the world's hyperscale inventory, demand is bifurcating between 100-megawatt campuses for training and sub-1-megawatt edge nodes for low-latency inference.
Hyperscale Self-Build Pipelines Above 10 GW
Amazon Web Services, Microsoft Azure, Google Cloud, and Meta together hold over 10 gigawatts of active projects. Meta confirmed a USD 10 billion Louisiana campus, and Google added USD 1 billion in Texas expansion, signaling migration to secondary markets where land and utility interconnection costs are up to 60% lower than tier-1 hubs. Hyperscalers now self-perform civil work, hire specialists for mechanical and electrical scopes, and compress schedules from 24 months to 18 months, reducing general-contractor addressable value by roughly 25%.
Power-Grid Interconnection Delays (3-6 Years)
National queues exceed 2,600 gigawatts, stretching median approvals to five years. Dominion Energy alone lists 47 gigawatts of pending data-center load in Northern Virginia. Arizona Public Service froze new data-center hookups in late 2024, redirecting projects to Texas and Ohio. Developers are funding on-site peaker plants and small modular reactors that add USD 3 million to USD 5 million per megawatt but avoid queue risk, while Federal Energy Regulatory Commission reforms, slated for 2027, aim to streamline approvals.
Other drivers and restraints analyzed in the detailed report include:
- AI-Optimized Liquid-Cooling Retrofits Drive Rebuild Spend
- Edge and 5G Densification of Metro Clusters
- Transformer and Switch-Gear Supply-Chain Choke Points
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tier 3 sites held 56.43% share in 2025, favored for concurrent maintainability at a 20%-30% cost discount versus Tier 4 designs. However, fault-tolerant Tier 4 builds are on track for a 9.12% CAGR, the fastest within the United States data center construction market size. Banking, healthcare, and government tenants demand 99.995% uptime, prompting colocation operators to retrofit Tier 3 halls with dual utility feeds and 2N uninterruptible power supply racks. Uptime Institute's 2024 survey showed 38% of U.S. builds sought Tier 4 certification, up from 29% in 2022, a jump driven partly by cyber-insurance underwriters.
Colocation leaders Equinix and Digital Realty are layering Tier 4 features onto existing campuses to secure premium workloads, while Amazon Web Services included multiple Tier 4 campuses in its USD 11 billion Pennsylvania program to support GovCloud clients. As more enterprises require fault-tolerant hosting, contractors focused on redundant electrical paths and liquid-cooled backup modules stand to gain the largest share of Tier 4 spending.
Hyperscale campuses above 10 megawatts controlled 64.31% of 2025 build volume and are projected to grow at 9.45% annually, underscoring their weight in the United States data center construction market. Economies of scale in power procurement, modular cooling, and labor reduce per-megawatt costs by as much as 40% against medium-sized halls, prompting cloud providers to favor 100-200 megawatt master-planned sites.
Medium facilities between 1 megawatt and 10 megawatts still serve hybrid colocation tenants but face slower growth as workloads shift to cloud. Small sub-1 megawatt facilities bifurcate into decommissioned enterprise rooms and rising edge nodes. Broadband subsidies and 5G densification make edge builds financially viable in tier-2 and rural metros, a niche where modular specialists like Mortenson and Balfour Beatty deliver turnkey enclosures in under 45 days.
Complete Report Scope:
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Size
- Small
- Medium
- Large
- Hyperscale
- By Data Center Type
- Colocation Data Center
- Hyperscalers/Cloud Service Provider (CSPs)
- Enterprise and Edge Data Center
- By Infrastructure
- Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Services - Design and Consulting, Integration, Support and Maintenance
- Electrical Infrastructure
List of Companies Covered in this Report:
- AECOM
- Turner Construction
- DPR Construction
- Holder Construction
- Skanska USA
- Whiting-Turner Contracting
- Jacobs Solutions
- Balfour Beatty US
- Gilbane Building Company
- Hensel Phelps
- McCarthy Building Companies
- Brasfield and Gorrie
- JE Dunn Construction
- Mortenson Construction
- Kiewit Corporation
- Fluor Corporation
- Corgan Associates (AEC)
- Black and Veatch
- QTS Construction Services
- PowerHouse Data Centers (Tener Technologies)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud, AI and Big-Data Workload Boom
- 4.2.2 Hyperscale Self-Build Pipelines Above 10 GW
- 4.2.3 Edge and 5G Densification of Metro Clusters
- 4.2.4 Federal and State Tax-Incentive Packages
- 4.2.5 AI-Optimised Liquid-Cooling Retrofits Drive Rebuild Spend
- 4.2.6 On-Site Micro-Nuclear SMR Approvals Accelerate Greenfield Sites
- 4.3 Market Restraints
- 4.3.1 Soaring Land Prices Around Tier-1 Metros
- 4.3.2 Power-Grid Interconnection Delays (3-6 Years)
- 4.3.3 Transformer and Switch-Gear Supply-Chain Choke Points
- 4.3.4 ESG-Driven Municipal Moratoria on Water-Intensive Cooling
- 4.4 Industry Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Key Data Center Statistics
- 4.8.1 Exhaustive Data Center Operators in United States (in MW)
- 4.8.2 List of Major Upcoming Data Center Projects in United States (2025-2030)
- 4.8.3 CAPEX and OPEX For United States Data Center Construction
- 4.8.4 Data Center Power Capacity Absorption In MW, United States, 2023 and 2024
- 4.9 Artificial Intelligence (AI) Inclusion in Data Center Construction in United States
- 4.10 Regulatory and Compliance Framework
- 4.11 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Tier Type
- 5.1.1 Tier 1 and 2
- 5.1.2 Tier 3
- 5.1.3 Tier 4
- 5.2 By Data Center Size
- 5.2.1 Small
- 5.2.2 Medium
- 5.2.3 Large
- 5.2.4 Hyperscale
- 5.3 By Data Center Type
- 5.3.1 Colocation Data Center
- 5.3.2 Hyperscalers/Cloud Service Provider (CSPs)
- 5.3.3 Enterprise and Edge Data Center
- 5.4 By Infrastructure
- 5.4.1 Electrical Infrastructure
- 5.4.1.1 Power Distribution Solution
- 5.4.1.2 Power Backup Solutions
- 5.4.2 Mechanical Infrastructure
- 5.4.2.1 Cooling Systems
- 5.4.2.2 Racks and Cabinets
- 5.4.2.3 Servers and Storage
- 5.4.2.4 Other Mechanical Infrastructure
- 5.4.3 General Construction
- 5.4.4 Services - Design and Consulting, Integration, Support and Maintenance
- 5.4.1 Electrical Infrastructure
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Data Center Infrastructure Investment Based on Megawatt (MW) Capacity, 2024 vs 2030
- 6.5 Data Center Construction Landscape (Key Vendors Listings)
- 6.6 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.6.1 AECOM
- 6.6.2 Turner Construction
- 6.6.3 DPR Construction
- 6.6.4 Holder Construction
- 6.6.5 Skanska USA
- 6.6.6 Whiting-Turner Contracting
- 6.6.7 Jacobs Solutions
- 6.6.8 Balfour Beatty US
- 6.6.9 Gilbane Building Company
- 6.6.10 Hensel Phelps
- 6.6.11 McCarthy Building Companies
- 6.6.12 Brasfield and Gorrie
- 6.6.13 JE Dunn Construction
- 6.6.14 Mortenson Construction
- 6.6.15 Kiewit Corporation
- 6.6.16 Fluor Corporation
- 6.6.17 Corgan Associates (AEC)
- 6.6.18 Black and Veatch
- 6.6.19 QTS Construction Services
- 6.6.20 PowerHouse Data Centers (Tener Technologies)
- 6.7 List of Data Center Construction Companies
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment