|
시장보고서
상품코드
2125683
말레이시아의 데이터센터 건설 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Malaysia Data Center Construction - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
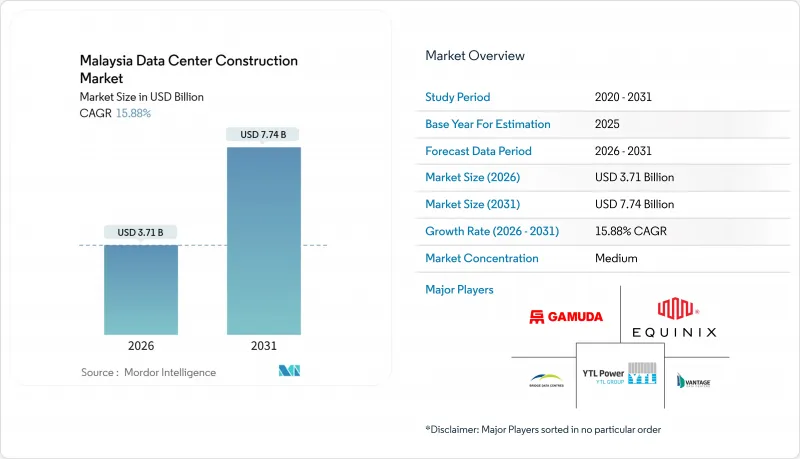
에 의하면, 말레이시아 데이터센터 건설 시장 규모는 2026년에 37억 1,000만 달러에 이르고, 2031년까지 77억 4,000만 달러에 이를 것으로 예측되며, 예측 기간 전체를 통해서 CAGR 15.88%라고 하는 견고성장을 나타내고 있습니다.
본 보고서는 티어 유형(Tier 1 및 2, Tier 3, Tier 4), 데이터센터 규모(소규모, 중규모, 대규모, 하이퍼스케일),데이터센터 유형(코로케이션 데이터센터, 하이퍼스케일러/클라우드 서비스 제공업체, 엔터프라이즈 및 엣지 데이터센터), 그리고 인프라(전기 인프라, 기계 인프라 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
말레이시아 데이터센터 건설 시장 동향 및 인사이트
싱가포르의 신규 허가 동결에 따른 파급 수요
2019년 싱가포르가 신규 허가 동결 조치를 취함에 따라, 200-300메가와트에 달하는 충족되지 못한 하이퍼스케일 수요가 해협을 넘어 유입되었고,조호르 주의 사업자들은 해협 건너편보다 40-60% 저렴한 토지 가격으로, 싱가포르 대비 2밀리초 미만의 지연 시간을 실현할 수 있게 되었습니다. 2025년 11월 Vantage Data Centers가 16억 달러에 300메가와트 규모의 캠퍼스를 인수한 것과, 그 전년에 Bridge Data Centres가 400메가와트 규모의 송전망 계약을 체결한 것은 앞으로도 계속될 수요 유출을 예상한 사전 준비를 보여줍니다. 말레이시아 투자개발청(MIDA)의 기록에 따르면, 2024년 데이터센터 분야의 외국인 직접투자(FDI) 규모는 200억 링깃에 달하고, 2022년 대비 5배로 급증했으며, 이는 지역 내 용량의 구조적 재분배를 뒷받침하고 있습니다.
하이퍼스케일 클라우드 및 AI 확장
마이크로소프트는 2024년 5월, 멀티사이트 캠퍼스 및 인재 양성 프로그램에 22억 달러를 투자하겠다고 밝혔으며, 한편 구글도 같은 달 말레이시아 최초의 클라우드 리전에 20억 달러를 배정했습니다. 이어 바이트댄스는 브리지 데이터센터(Bridge Data Centers)의 MY06 사이트를 핵심으로 하는 100억 링깃(21억 달러) 규모의 AI 허브를 계획하며, 말레이시아가 주요 가용성 구역으로 격상되었음을 보여주었습니다. YTL 파워의 500메가와트 규모 ‘그린 DC 파크’는 NVIDIA GB200 NVL72 랙과 부지 내 태양광 발전 시설을 통합하여 PUE 1.3을 달성함으로써, AI에 최적화된 지속가능성 측면에서 지역적 벤치마크를 확립했습니다.
송전망 용량 및 피크 시간대 요금 인상
테나가 나시오날 베르하드는 변전소 업그레이드 비용을 충당하기 위해 2025년 7월 상업용 전기 요금을 14% 인상했습니다. 이로 인해 10메가와트 규모의 시설에서 연간 전기 요금은 약 20만 달러 증가하게 됩니다. 사업자들은 C-RESS 기반의 20년 태양광 발전 PPA를 통해 리스크를 헤지하고 있으며, 밴티지(Vantage)사가 ib vogt사와 체결한 30메가와트 규모의 가상 PPA는 이러한 변화를 상징하는 사례입니다.
부문 분석
2025년 매출 중 Tier 3 시설이 56.04%를 차지했으나, 티어 4 용량은 연평균 성장률(CAGR) 16.87%를 기록하며 다른 모든 등급을 상회할 것으로 예측됩니다. 따라서 각 하이퍼스케일러 기업들이 병렬 유지보수가 가능한 전원 및 냉각 체인을 도입함에 따라, 말레이시아의 티어 4 프로젝트를 대상으로 한 데이터센터 건설 시장 규모는 급격히 확대될 것으로 전망됩니다. 에퀴닉스는 2027년에 JH2 캠퍼스에 2N 전원 공급 장치를 갖춘 캐비닛 2,225기를 증설할 예정입니다.
Tier 1 및 Tier 2 사이트는 엣지 및 재해 복구 워크로드에서 여전히 중요한 역할을 하고 있지만, 2023년부터 2025년까지 신규 수주에서 AI 훈련 및 추론이 차지하는 비율은 10% 미만에서 25% 가까이 상승했습니다. NTT의 조호르 캠퍼스에서는 사업 연속성 요건을 충족하기 위해 2계통의 전력 공급과 72시간의 연료 자급 공급을 계획하고 있습니다. 이러한 방향 전환은 최종 사용자가 미세한 온도나 전력 변동조차도 용납하지 않는다는 점을 반영하며, 말레이시아 데이터센터 건설 시장을 더 높은 사양의 시설로 이끌고 있습니다.
2025년에는 대규모 시설이 55.46%의 점유율을 차지했으나, 그럼에도 불구하고 단일 사이트의 건설 규모가 100메가와트를 초과하는 ‘하이퍼스케일 캠퍼스’는 연평균 성장률(CAGR) 16.34%로 성장할 전망입니다. Vantage사의 256메가와트 규모 ‘KUL2’와 Bridge Data Centres사의 400메가와트 전력 공급 계약이 가동을 시작함에 따라, 말레이시아 데이터센터 건설 시장에서 하이퍼스케일 시설의 점유율은 확대될 전망입니다.
캠퍼스형 모델은 부지 확보, 전력 공급 계약 협상 및 단계적 인도를 효율화합니다. Vantage사의 300메가와트 규모 ‘JHB1’은 임차인이 수년에 걸쳐 단계적으로 운영을 확대할 수 있도록 하는 반면, Bridge사의 ‘MY07’은 추가로 200메가와트 분량의 부지를 확보하고 있습니다. 중소규모 시설은 계속해서 관리형 서비스 제공업체와 엣지 캐싱을 뒷받침하고 있지만, 말레이시아 데이터센터 건설 시장에서의 점유율은 축소되는 추세입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the Malaysia data center construction market size reached USD 3.71 billion in 2026 and is projected to reach USD 7.74 billion by 2031, reflecting a robust 15.88% CAGR across the forecast horizon.
This report is Segmented by Tier Type (Tier 1 and 2, Tier 3, and Tier 4), Data Center Size (Small, Medium, Large, and Hyperscale), Data Center Type (Colocation Data Center, Hyperscalers/Cloud Service Provider, and Enterprise and Edge Data Center), and Infrastructure (Electrical Infrastructure, Mechanical Infrastructure, and More). The Market Forecasts are Provided in Terms of Value (USD).
Malaysia Data Center Construction Market Trends and Insights
Spill-Over Demand From Singapore Moratorium
Singapore's 2019 freeze on new permits pushed 200-300 megawatts of unmet hyperscale demand across the causeway, enabling operators in Johor to deliver sub-2-millisecond latency to Singapore at land prices 40-60% lower than across the Strait. Vantage Data Centers' USD 1.6 billion acquisition of a 300-megawatt campus in November 2025 and Bridge Data Centres' 400-megawatt grid agreement the previous year illustrate pre-positioning for continued overflow. Malaysia's Investment Development Authority recorded RM 20 billion in data-center FDI during 2024, a five-fold jump from 2022, confirming the structural re-allocation of regional capacity.
Hyperscale Cloud and AI Build-Outs
Microsoft committed USD 2.2 billion in May 2024 for multi-site campuses and workforce programs, while Google earmarked USD 2 billion for its first Malaysian cloud region in the same month. ByteDance followed with a RM 10 billion (USD 2.1 billion) AI hub anchored by Bridge Data Centres' MY06 site, signifying Malaysia's elevation to a primary availability zone. YTL Power's 500-megawatt Green DC Park integrates Nvidia GB200 NVL72 racks and on-site solar to achieve a 1.3 PUE, setting a regional benchmark for AI-optimized sustainability.
Grid Capacity and Peak Tariff Escalation
Tenaga Nasional Berhad lifted commercial tariffs 14% in July 2025 to finance substation upgrades, raising a 10-megawatt facility's annual electricity bill by roughly USD 200,000. Operators hedge exposure through 20-year solar PPAs under C-RESS; Vantage's 30-megawatt virtual PPA with ib vogt exemplifies this shift.
Other drivers and restraints analyzed in the detailed report include:
- Malaysia Digital Tax and Incentive Schemes
- Sub-Sea Cable Landings Elevating Connectivity
- Shortage of Certified Data-Center Technicians
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tier 3 installations controlled 56.04% of 2025 revenue, yet Tier 4 capacity is forecast to post a 16.87% CAGR, outpacing all other classes. The Malaysia data center construction market size for Tier 4 projects is therefore projected to rise sharply as hyperscalers deploy concurrent-maintainable power and cooling chains. Equinix will add 2,225 cabinets with 2N electrical feeds at its JH2 campus in 2027.
Tier 1 and Tier 2 sites remain relevant for edge and disaster-recovery workloads, but the share of AI training and inference rose from under 10% to nearly 25% of new bookings between 2023 and 2025. NTT's Johor campus plans dual utility feeds and 72-hour fuel autonomy to meet business-continuity mandates. The pivot reflects end-user intolerance for even brief thermal or power excursions, pushing the Malaysia data center construction market toward higher-spec builds.
Large facilities held 55.46% share in 2025; nevertheless, hyperscale campuses, defined as single-site builds exceeding 100 megawatts, are poised to expand at a 16.34% CAGR. The Malaysia data center construction market share for hyperscale sites is thus set to grow as Vantage's 256-megawatt KUL2 and Bridge Data Centres' 400-megawatt electricity deal come online.
Campus models improve land acquisition, utility negotiation, and phased delivery. Vantage's 300-megawatt JHB1 enables multi-year tenant ramp-ups, while Bridge's MY07 reserves acreage for 200 additional megawatts. Medium and small facilities continue to support managed service providers and edge caching, but they capture a shrinking slice of the Malaysia data center construction market.
Complete Report Scope:
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Size
- Small
- Medium
- Large
- Hyperscale
- By Data Center Type
- Colocation Data Center
- Hyperscalers/Cloud Service Provider (CSPs)
- Enterprise and Edge Data Center
- By Infrastructure
- Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Services - Design and Consulting, Integration, Support and Maintenance
- Electrical Infrastructure
List of Companies Covered in this Report:
- Aurecon Group Pty Ltd
- AECOM
- DSCO Group Pte Ltd
- Turner and Townsend Holdings Ltd
- Jacobs Engineering Group Inc.
- Gaw Capital Partners
- JLand Group Bhd
- Cyclect Group Pte Ltd
- Basis Bay Sdn Bhd
- Mah Sing Group Bhd
- Equinix Inc.
- Vantage Data Centers LLC
- Bridge Data Centres Malaysia Sdn Bhd
- YTL Power International Bhd (Green DC Park)
- Gamuda Bhd
- Telekom Malaysia Berhad
- Exabytes Capital Group Sdn Bhd
- GDS Holdings Ltd
- AIMS Data Centre (Time dotCom Bhd)
- Gamuda Engineering Sdn Bhd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Spill-Over Demand From Singapore Moratorium
- 4.2.2 Malaysia Digital Tax and Incentive Schemes (MyDIGITAL, DTax)
- 4.2.3 Hyperscale Cloud and AI Build-Outs (Microsoft, Google, AWS)
- 4.2.4 Affordable Land and Power in Johor and Cyberjaya
- 4.2.5 Corporate Renewable Energy Supply Scheme (C-RESS) Enabling 20-Yr Green PPAs
- 4.2.6 Sub-Sea Cable Landings (MIST, Apricot, Bifrost) Elevating Connectivity
- 4.3 Market Restraints
- 4.3.1 Grid Capacity and Peak Tariff Escalation
- 4.3.2 Shortage of Certified Data-Center Technicians
- 4.3.3 Fragmented Multi-Tier Land-Use Approvals Causing Delays
- 4.3.4 Rising Water-Stress Risk in Johor Cooling Corridor
- 4.4 Industry Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Key Data Center Statistics
- 4.8.1 Exhaustive Data Center Operators in Malaysia (in MW)
- 4.8.2 List of Major Upcoming Data Center Projects in Malaysia (2025-2030)
- 4.8.3 CAPEX and OPEX For Malaysia Data Center Construction
- 4.8.4 Data Center Power Capacity Absorption In MW, Malaysia, 2023 and 2024
- 4.9 Artificial Intelligence (AI) Inclusion in Data Center Construction in Malaysia
- 4.10 Regulatory and Compliance Framework
- 4.11 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Tier Type
- 5.1.1 Tier 1 and 2
- 5.1.2 Tier 3
- 5.1.3 Tier 4
- 5.2 By Data Center Size
- 5.2.1 Small
- 5.2.2 Medium
- 5.2.3 Large
- 5.2.4 Hyperscale
- 5.3 By Data Center Type
- 5.3.1 Colocation Data Center
- 5.3.2 Hyperscalers/Cloud Service Provider (CSPs)
- 5.3.3 Enterprise and Edge Data Center
- 5.4 By Infrastructure
- 5.4.1 Electrical Infrastructure
- 5.4.1.1 Power Distribution Solution
- 5.4.1.2 Power Backup Solutions
- 5.4.2 Mechanical Infrastructure
- 5.4.2.1 Cooling Systems
- 5.4.2.2 Racks and Cabinets
- 5.4.2.3 Servers and Storage
- 5.4.2.4 Other Mechanical Infrastructure
- 5.4.3 General Construction
- 5.4.4 Services - Design and Consulting, Integration, Support and Maintenance
- 5.4.1 Electrical Infrastructure
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Data Center Infrastructure Investment Based on Megawatt (MW) Capacity, 2024 vs 2030
- 6.5 Data Center Construction Landscape (Key Vendors Listings)
- 6.6 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, Recent Developments)
- 6.6.1 Aurecon Group Pty Ltd
- 6.6.2 AECOM
- 6.6.3 DSCO Group Pte Ltd
- 6.6.4 Turner and Townsend Holdings Ltd
- 6.6.5 Jacobs Engineering Group Inc.
- 6.6.6 Gaw Capital Partners
- 6.6.7 JLand Group Bhd
- 6.6.8 Cyclect Group Pte Ltd
- 6.6.9 Basis Bay Sdn Bhd
- 6.6.10 Mah Sing Group Bhd
- 6.6.11 Equinix Inc.
- 6.6.12 Vantage Data Centers LLC
- 6.6.13 Bridge Data Centres Malaysia Sdn Bhd
- 6.6.14 YTL Power International Bhd (Green DC Park)
- 6.6.15 Gamuda Bhd
- 6.6.16 Telekom Malaysia Berhad
- 6.6.17 Exabytes Capital Group Sdn Bhd
- 6.6.18 GDS Holdings Ltd
- 6.6.19 AIMS Data Centre (Time dotCom Bhd)
- 6.6.20 Gamuda Engineering Sdn Bhd
- 6.7 List of Data Center Construction Companies
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment